DiaMedica Heads Into Q3 Near Highs As Stroke Enrollment And Cash Runway Face Scrutiny
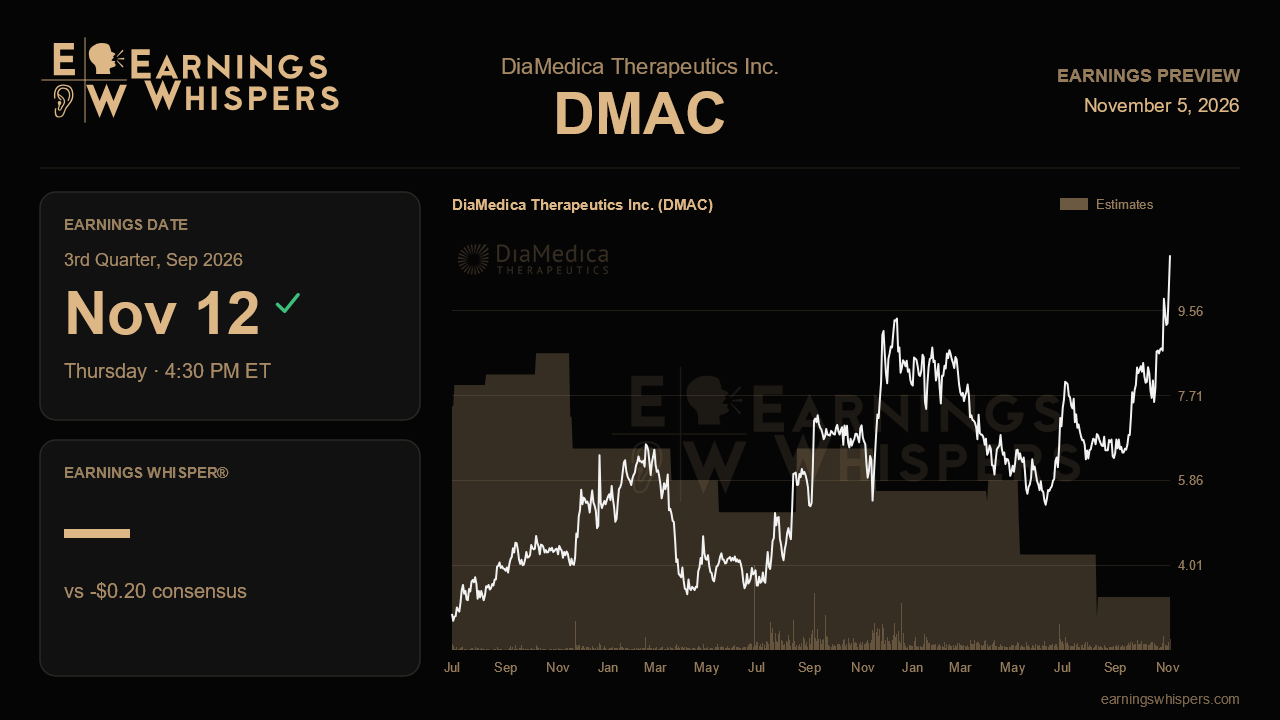
DiaMedica Therapeutics arrives at its third-quarter report with a stock that has rallied more than 60% since its last update and a calendar crowded with milestones it promised to hit before year end. For a clinical-stage company with no revenue, the November 12 release, due after the close, is less about the loss per share than about whether the timelines management laid out in August are holding. The rally suggests the market has started to price in a more confident story, which raises the cost of any slippage.
The Street expects a loss of $0.20 per share. That compares with $0.19 last quarter and $0.17 a year ago, which works out to a roughly 18% wider year-over-year loss. That is consistent with what the company has shown: operating cash burn over the first half of 2026 rose to $17.2 million from $14.7 million a year earlier as Remedy 2 expanded to around 70 sites across North America, the UK and six European countries. A modestly larger loss would not be alarming. The more telling figure is cash. The balance fell from $59.9 million at the end of 2025 to $43.5 million in June. At the recent burn pace of roughly $8 million to $9 million a quarter, that would put September cash somewhere in the mid-$30 million range. Management has guided to a runway through 2027, and any softening of that language, or a sharper jump in spending, would matter more than a penny on EPS.
The stroke program is the central test. Enrollment toward the 200-patient interim analysis for Remedy 2 climbed from about half to roughly 70% and then to more than 85% over successive calls. Last quarter, however, management acknowledged that enrollment slowed in July and pushed the interim readout from the end of 2026 into the first quarter of 2027. This report should show whether that was a summer lull or a sign of something more stubborn. If enrollment is complete or nearly complete, the Q1 2027 timeline gains credibility. If it is stuck in the high 80s, the market may start to doubt the new date, especially after an earlier enrollment reset in 2025.
The women's-health franchise supplied much of last quarter's optimism, and several of those catalysts should have advanced by now. The first fetal growth restriction cohort, the first time DM-199 has been dosed in early-onset patients, was slated for top-line data at a September KOL event. Management's interpretation of that data, and what it means for dosing in the early-onset preeclampsia trial, will be closely parsed. That Health Canada-authorized study targeted first patient dosing in the fourth quarter. The US regulatory path is another checkpoint. FDA indicated the rat pharmacology study, due to report in October, was the final piece needed before an IND submission. Confirmation that the report is in hand and a submission is imminent would validate the improving narrative. Any request for more work would revive concerns raised when the earlier rabbit model was abandoned. Investors should also look for any further comment on dosing in late-onset preeclampsia, where receptor desensitization has already narrowed the strategy to the mid-dose range.
Sentiment has warmed noticeably, with bearish readings easing from about 38% to roughly 22%, though it remains net negative. The stock sits at $10.77, well above its 200-day average of $7.14 and within about 2% of its post-earnings high of $11.00. That puts it in position to test a breakout. A breakout attempt into the print, after a range that has shifted sharply higher from the prior quarter's $5.24 to $8.53, means good news may already be partly reflected in the price.
Ultimately, the narrative stays intact if DiaMedica can show that Remedy 2 enrollment has regained momentum, the US IND is on track, and cash still comfortably covers 2027. A second stroke delay or a thinner runway would undercut the case that justified this rally.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-22 | |
| Oct-19 | |
| Sep-30 | |
| Sep-02 | |
| Aug-11 | |
| Aug-10 | |
| Aug-04 | |
| Jul-17 | |
| Jun-23 | |
| Jun-16 | |
| May-27 | |
| May-20 | |
| May-12 |
