DiaMedica's Narrow Miss Matters Less Than Its Shrinking Runway And Slipping Timelines Ahead Of Two Binary Catalysts
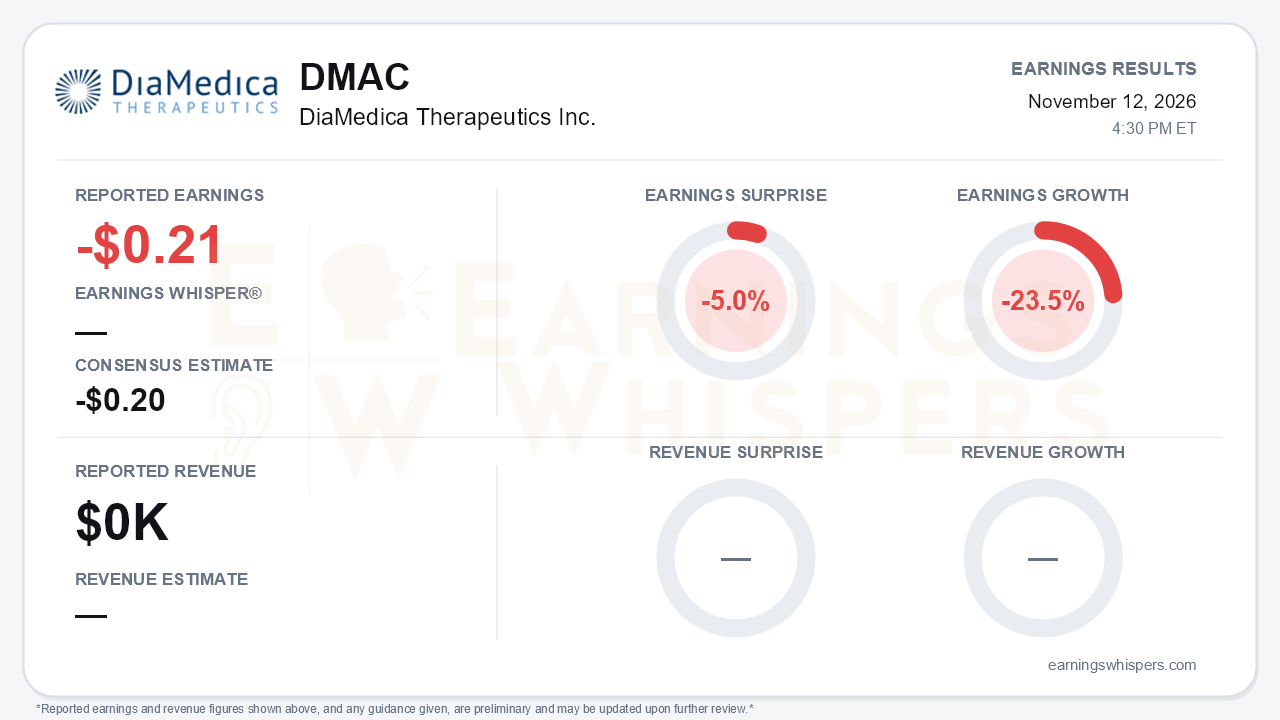
DiaMedica Therapeutics (NASDAQ: DMAC) reported a third-quarter loss of $0.21 per share, a penny worse than the $0.20 consensus. That is a 5.0% miss, and earnings fell 23.5% from a year ago. For a pre-revenue clinical-stage company, the per-share result matters little on its own. What matters is what it reveals: spending is accelerating, the cash cushion is thinning faster than investors had been told, and the timelines that justify that spending continue to drift. The company did hit two real enrollment milestones. The central tension is that the stock has rallied hard into a pair of binary events while the operating discipline around those events has weakened.
The widening loss is mostly an R&D story. Net loss rose to $11.3 million from $8.6 million a year earlier. Research and development expense climbed to $9.2 million from $6.4 million, and spending is also rising sequentially, from $8.0 million in Q1 to $8.2 million in Q2 to $9.2 million in Q3. Management attributed the increase to several drivers:
- a larger clinical team;
- global expansion of the ReMEDy2 stroke trial;
- start-up of the Phase 2 preeclampsia study in Canada and the UK;
- additional FDA-requested reproductive toxicity work;
- manufacturing development.
G&A was essentially flat at $2.4 million. Management expects R&D to increase moderately from here. Cash, equivalents and investments fell to $34.9 million from $43.5 million at the end of Q2 and $59.9 million at year-end 2025. Runway guidance was quietly trimmed from "through 2027" to "into Q4 2027." The change looks small, but it compresses the window between the stroke interim analysis and the point at which new capital becomes necessary.
The call preserved a credible clinical narrative.
ReMEDy2 enrollment progressed steadily across the year:
- roughly 70% of the interim threshold on the Q4 FY25 call;
- more than 70% in Q1;
- more than 85% in Q2;
- the 200th participant enrolled in October.
The independent DSMB interim analysis remains on track for Q1 2027, unchanged from last quarter. Management expects close to 300 patients enrolled by the time of the readout.
In fetal growth restriction, both six-patient cohorts at 5 and 10 µg/kg are now fully enrolled. A key opinion leader event featuring preliminary data is set for November 24.
Regulatory progress in preeclampsia was also tangible. The company received EMA conditional authorization in October and a Health Canada authorization in September. In addition, the in-life phase of the FDA-requested rat study is complete. Pharmacokinetic and pharmacologic results are due in the coming weeks, followed by a submission aimed at opening a U.S. IND.
The weaker side of the ledger is a pattern of slippage that bears can legitimately point to:
- The FGR KOL event moved from September to late November.
- Starts for Parts 1b and 2 of the investigator-sponsored preeclampsia study, once guided for "this summer," are now expected by the end of 2026.
- First enrollment in the company-sponsored Phase 2 preeclampsia study is now "this year, worst case early 2027," after being guided to Q4 2026.
- The stroke interim itself has already moved from H2 2026 to Q1 2027.
- The rat study report is running behind the September/October expectation set on the Q2 call.
None of these delays is individually damaging. Collectively, they argue for discounting management's timelines.
The forward setup is dominated by two catalysts with very different risk profiles.
The November 24 FGR readout is near-term but limited. It covers 12 patients in an open-label, single-center investigator-sponsored trial in South Africa, and the company itself cautions that the data are preliminary and subject to change. The data may be informative on safety and signal, but they cannot carry heavy statistical weight.
The ReMEDy2 interim is the larger event. The company will remain blinded, and the DSMB can stop the trial for futility or re-estimate the sample size anywhere from 300 to 728 participants. A recommendation toward the high end would materially raise costs and extend timelines, and current cash runs only into Q4 2027.
The market has been pricing the upside more than the risks. Shares are up 39.9% since the open following the August report, from $6.67 to $9.33. They sit about 30% above the 200-day moving average of $7.18, and the price and AVWAP trend readings are both positive. At roughly 54 million shares, that implies a market value around $500 million against $34.9 million of cash. Investor sentiment tells a more cautious story: it remained negative and slipped modestly, from -0.38 to -0.43. Enthusiasm in the share price has not been matched by improving investor expectations.
The bottom line is that the Q3 miss itself is noise, but the quarter sharpened the trade-offs. DiaMedica delivered the enrollment milestones it needed, has two meaningful readouts within roughly five months, and is making regulatory headway in preeclampsia. It is also spending more, guiding to a shorter runway, and continuing to miss its own timelines. With the stock well extended above its long-term average heading into a small open-label dataset and a blinded interim that could end in futility or a costly upsize, the risk/reward now hinges almost entirely on execution at those two events.
Read our earnings preview for DiaMedica Therapeutics Inc.: https://www.earningswhispers.com/article/DMAC/22969
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-13 | |
| Nov-12 | |
| Nov-05 | |
| Nov-05 | |
| Oct-22 | |
| Oct-19 | |
| Sep-30 | |
| Sep-02 | |
| Aug-11 | |
| Aug-10 | |
| Aug-04 | |
| Jul-17 | |
| Jun-23 | |
| Jun-16 | |
| May-27 |
