Southern Company Beats On Weather And Data Centers, Lifts 2026 Outlook As Georgia Political Risk Emerges
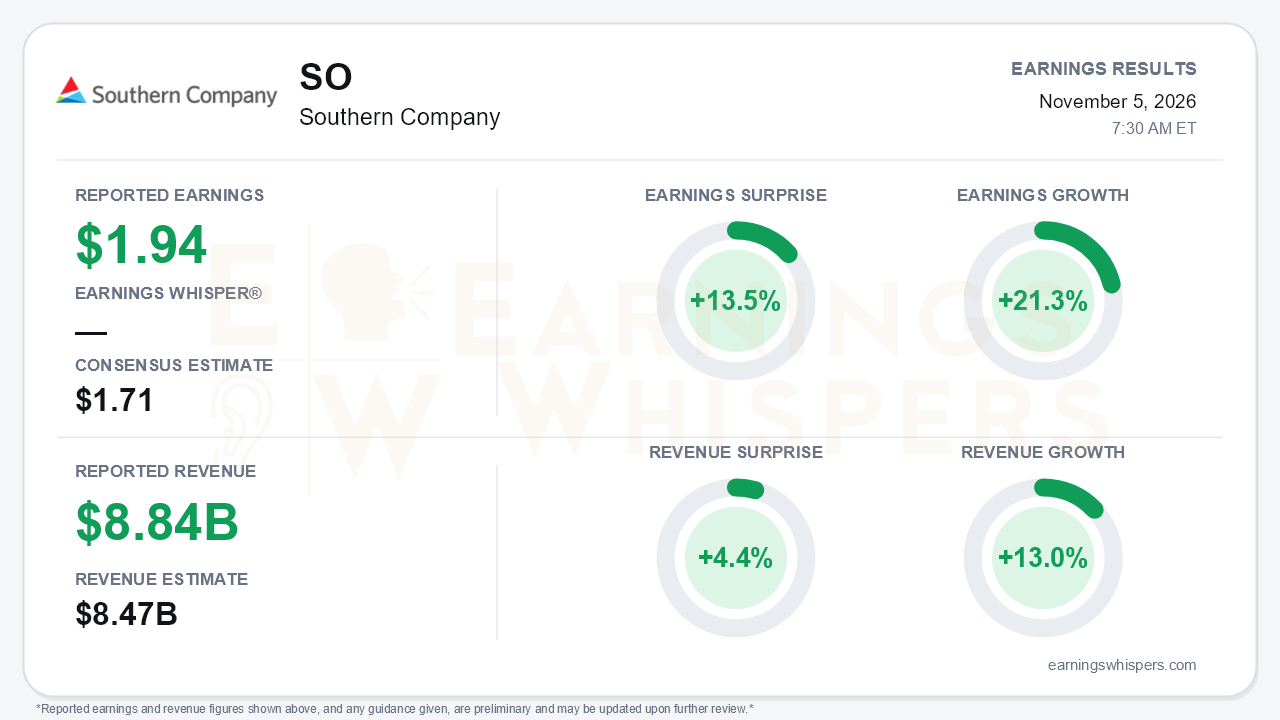
Southern Company delivered the most forceful quarter of its year. Adjusted earnings of $1.94 per share beat the $1.71 consensus by 13.5% and grew 21.3% year over year. Revenue of $8.843 billion topped the $8.47 billion estimate by 4.4% and rose 13.0%, well ahead of the 7.3% nine-month pace. The call analysis cites a lower $1.65 estimate, which would make the beat look even larger. Either way, this was the third straight beat and the widest of 2026. Management raised full-year adjusted EPS guidance to about $4.70, $0.10 above the top of the original $4.50-$4.60 range. In the second quarter it had only pointed to "near or at the top." The central tension is that the growth story keeps strengthening while the regulatory backdrop in Georgia, Southern's largest earnings engine, just became less predictable.
The quality of the beat deserves some scrutiny, but it holds up better than a weather-aided quarter usually does. Of the $0.34 adjusted EPS increase, weather contributed $0.15. Retail revenue impacts added $0.21 and retail sales growth another $0.11. Several items worked against the result:
- Higher non-fuel O&M cost $0.09.
- Interest expense and other cost $0.11.
- Share dilution cost $0.09, as average shares rose to 1,157 million from 1,102 million.
- Taxes other than income taxes jumped $146 million.
GAAP EPS of $1.77 trailed the adjusted figure. The gap came mainly from continued accelerated depreciation on Southern Power's wind repowering, debt-extinguishment costs including a $57 million tax-benefit change tied to 2025, and a small Nicor Gas disallowance charge. Georgia Power was the standout, with net income up 22.0% on an 18.6% revenue increase. Southern Company Gas earned slightly less in its seasonally small quarter.
Beneath the weather, demand is accelerating:
- **Retail sales:** Weather-normal retail sales grew 3.5%, up from 2.3% in each of the first two quarters.
- **Commercial sales:** Weather-adjusted commercial sales rose 7.3%.
- **Data centers:** Data center usage climbed 59%, versus 55% in the second quarter and 42% in the first.
- **Residential sales:** Weather-adjusted residential growth was a modest 1.3%. The acceleration is concentrated in large-load customers rather than broad household demand.
- **Signed large-load contracts:** These reached 21 GW, up from 17 GW last quarter and 10 GW at year-end. Alabama and Georgia each added roughly 2 GW.
- **Late-stage pipeline:** This narrowed to 7 GW from 12 GW in the first quarter. That reads less as weakness than as conversion into signed contracts.
- **Economic development:** Announcements hit $25 billion in the quarter and a record $45 billion-plus for the year, including Audi's $4 billion Georgia plant.
The forward catalysts are substantial. Management signaled it will raise the upper ends of its 2027 ($4.85-$4.95) and 2028 ($5.25-$5.45) EPS ranges in February, creating a higher base for 7-8% growth. About $4 billion of projects now sit above the $81 billion capital plan. These include Southern Power uprates, a Georgia Power nuclear uprate partnership with Google, and the Southeast Connector pipeline expansion. Management said the plan could approach $100 billion with RFP wins.
Bears have legitimate ammunition, though:
- **Equity needs:** The remaining equity requirement through 2030 rose to about $2 billion from $1.1 billion, reflecting the added capex.
- **Construction costs:** Management acknowledged that combined-cycle costs are trending toward $3 billion-plus per GW, well above its $2 billion rule of thumb.
- **Georgia politics:** The November election flipped the party makeup of the Georgia PSC, leaving an untested commission ahead of the 2028 rate case. The governor-elect has also floated pausing new data center development by executive order.
- **Storm costs:** Hurricane Isaias affected 650,000 customers.
The market setup is more complicated than the surprise implies. Shares hit a 52-week low of $81.69 on September 29. They have since rallied 14% to $93.12, just 0.7% above the 200-day moving average. Even so, the stock remains 4.2% below its opening price after the July report and about 4% below the quarter's high. Investor sentiment improved only slightly, from -0.23 to -0.21, and remains negative. Investors have not embraced the growth narrative despite consecutive beats. Short-term momentum and AVWAP readings have turned positive, consistent with the autumn recovery, while the broader price trend is neutral.
The bottom line is that Southern Company converted accelerating data center demand into a raised 2026 outlook, a firmer multi-year growth trajectory and a capital plan that could grow sharply. Weather flattered the quarter, but weather-normal sales and contracted load show the fundamental improvement is real. The open question is no longer demand but execution and regulation: rising equity needs, construction-cost inflation and a reshaped Georgia commission now carry more weight in the investment case. With sentiment still negative and shares only just reclaiming the 200-day average, investors appear to be pricing that regulatory uncertainty more heavily than the earnings momentum.
Read our earnings preview for Southern Company: https://www.earningswhispers.com/article/SO/22185
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Nov-04 | |
| Nov-04 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-16 |
