Milestone's Cardamist Launch Faces Its Pricing Test As Coverage Tops 50% And Shares Slide
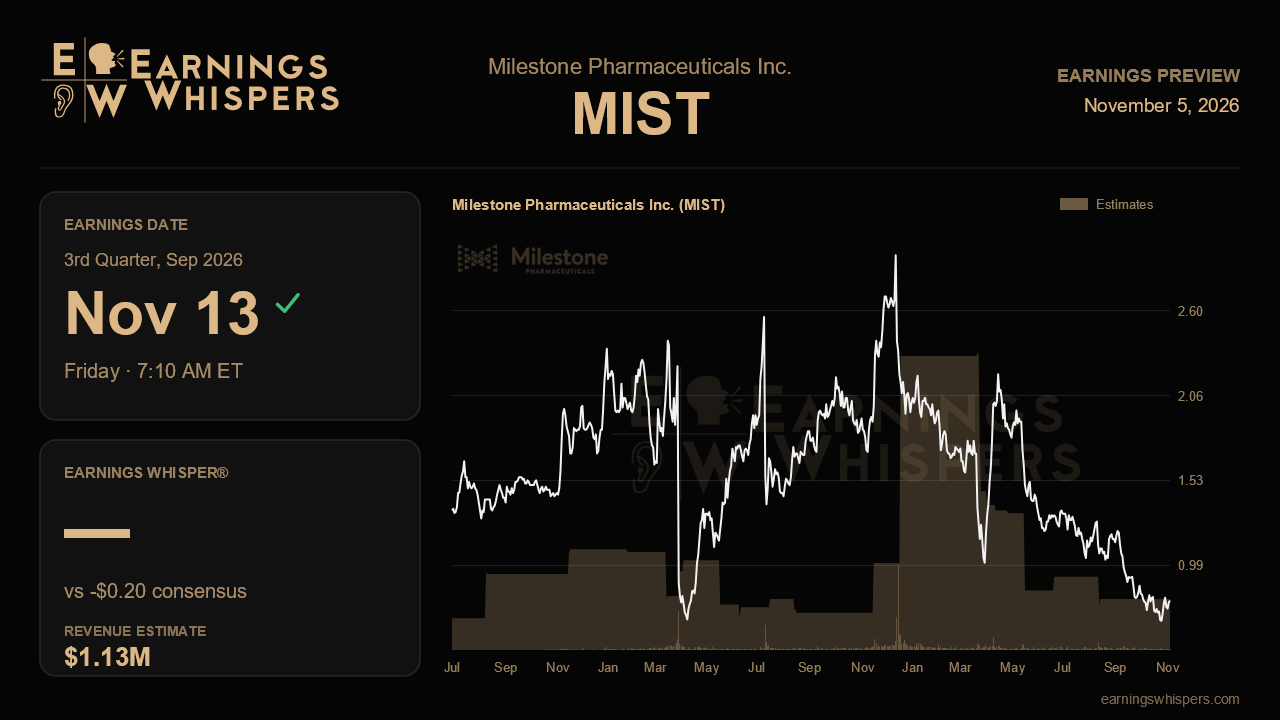
Milestone Pharmaceuticals heads into its third-quarter report with a split personality. On the operating side, the Cardamist launch looked like it was finally gaining traction last quarter, with prescriptions, prescribers and insurance coverage all stepping up sharply. In the market, though, the stock has fallen 28.5% since that report, badly lagging a roughly flat S&P 500. The November 13 release, due before the open, is the first quarter in which Milestone has had more than half of commercially insured lives covered, which makes it the first real test of whether broader access translates into meaningful revenue rather than just more scripts.
The Street is looking for a loss of $0.20 per share, essentially in line with the $0.21 loss in the second quarter but well wider than the $0.12 loss a year ago, a roughly 67% deterioration that reflects the cost of building a commercial organization. Revenue is expected at about $1.1 million, nearly double the $0.6 million booked in the second quarter. Management offers no formal financial guidance, as is typical for an early launch, but it did say it expects demand to accelerate in the second half. The consensus revenue figure effectively assumes that promise holds.
The arithmetic behind that estimate is worth unpacking. Second-quarter revenue of $0.6 million on more than 1,200 prescriptions implies net revenue of roughly $500 per script, a figure held down by aggressive denial conversion and copay support while coverage sat near 25%. Management argued that pricing should improve in the third and fourth quarters as the UnitedHealthcare and other Express Scripts and OptumRx plan wins added in July and August take hold. If realized price per script does not move, Milestone would need something close to 2,200 prescriptions to hit consensus, a steep jump in a single quarter. If pricing improves as promised, a more modest script gain gets the job done. The split between volume and price is therefore the single most informative detail in this report.
Beyond revenue, the call laid out several markers that would validate the improving narrative. Prescriber growth should keep compounding from the more than 800 cumulative writers at midyear, and repeat use, hinted at by 1,500 scripts across 1,300 patients in the first half, should become more visible. The patient-activation campaign, which management held back until coverage crossed 50%, should begin showing up in demand commentary. On the pipeline, investors will want confirmation that the Rivera 301 Phase III trial in AFib with rapid ventricular response has actually begun enrolling, along with reassurance that the European regulatory decision for the PSVT indication remains on schedule for the first half of 2027.
The risks are equally clear. SG&A jumped to $22.6 million in the second quarter from $8.9 million a year earlier, and cash of $170.6 million at the end of June was said to last into the second half of 2027. With the stock at $0.77, well below its 200-day moving average of $1.36 and sitting closer to the $0.63 low than the $1.26 high of its post-earnings range, any sign that burn is outrunning revenue will sharpen financing concerns. Sentiment has turned noticeably, swinging from mildly bullish ahead of the last report to moderately bearish now, suggesting the market is already braced for disappointment.
That pessimism sets up an asymmetric moment. The central question is whether the jump to majority coverage is lifting net revenue per prescription, not just prescription counts. Evidence that pricing is improving while spending levels off would support management's acceleration story and ease runway worries. Flat realized pricing paired with rising costs would suggest the launch is buying volume at a price the balance sheet cannot sustain for long.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-19 | |
| Oct-09 | |
| Sep-24 | |
| Sep-03 | |
| Sep-02 | |
| Aug-27 | |
| Aug-21 | |
| Aug-21 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 |
