Milestone Pharmaceuticals Beats On A One-Time License Payment, But A 30% Cost Cut Shows The CARDAMYST Launch Is Running Below Plan
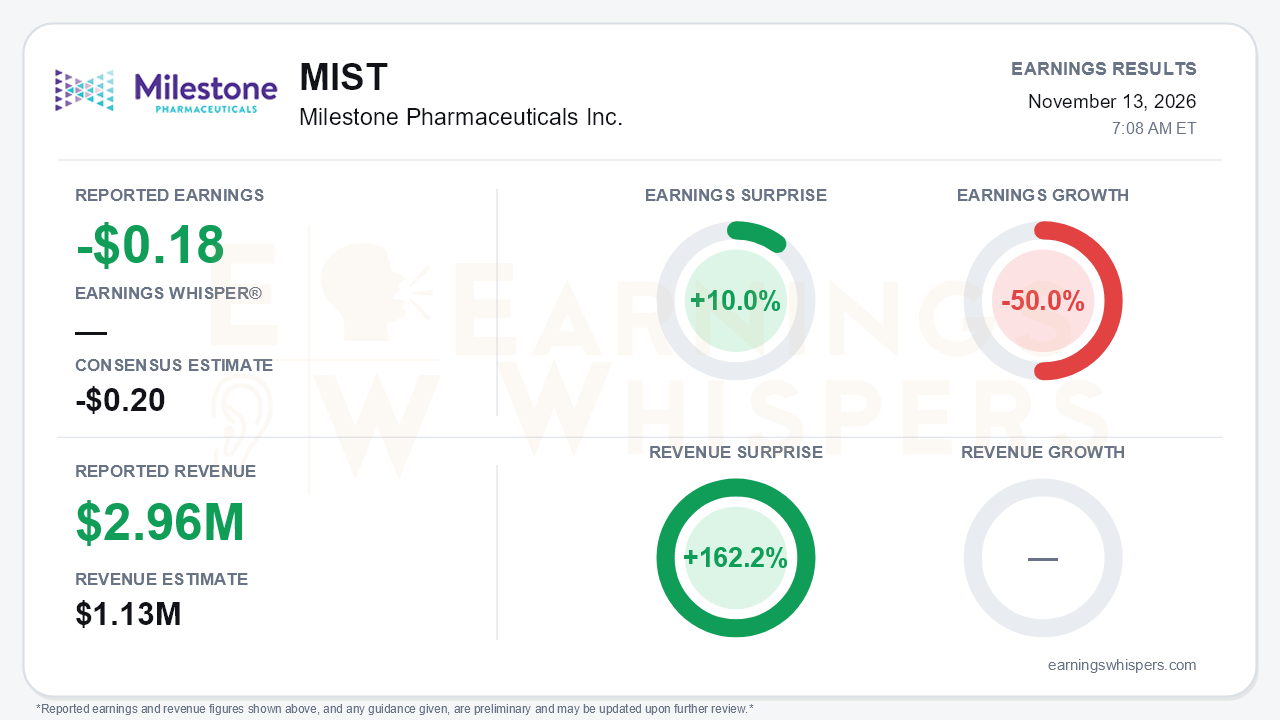
Milestone Pharmaceuticals (NASDAQ: MIST) beat expectations in the third quarter, but the more important news was the company's decision to shrink. The company reported a loss of $0.18 per share, ahead of the -$0.20 consensus by 10.0%. Revenue of $2.96 million beat the $1.13 million estimate by 162.2%. Neither figure reflects how the CARDAMYST launch is actually going. Alongside the results, Milestone announced a roughly 30% operating-expense reduction, a smaller in-house sales force, and the departures of its CFO and CMO. A company whose launch is accelerating does not take those steps. That is the central tension: every launch metric improved sequentially, yet management chose to stretch its cash rather than spend to accelerate.
The quality of the beat deserves scrutiny. Of the $2.96 million in total revenue, $2.0 million was license and other revenue. Net product revenue from CARDAMYST was only $963,000. That figure is up 73% from the second quarter and up from about $0.2 million in the first, but it is still small against $24.2 million of SG&A spending, compared with $7.9 million a year ago. The net loss more than doubled to $25.8 million from $11.9 million, and earnings fell 50.0% year over year as the per-share loss widened from $0.12. Interest expense also more than doubled. The balance sheet now shows an $82.8 million royalty financing obligation and a small shareholders' deficit. Cash of $145.4 million is up from year-end only because of that financing. Sequentially it fell from $170.6 million in Q2 and roughly $184 million in Q1.
The operating data on the call were directionally healthy:
- Q3 prescriptions reached roughly 1,800, up 50% from more than 1,200 in Q2.
- Unique prescribers grew to about 750 from more than 600.
- Commercial coverage expanded to about two-thirds of covered lives, up from roughly 50% at the Q2 call and 25% at Q1.
- Implied net revenue per script improved to about $555 from about $500.
- The refill rate held at 1.3 scripts per patient.
The tone, however, changed. In Q2, management talked about accelerating growth in the second half and a patient-activation "tipping point." This quarter the language became "steady growth" and an admission that "we have work to do." The CEO identified physician inertia as the core friction. Combined with the August cut in the field force from about 60 reps to 45, the message is that the launch curve is shallower than the company originally modeled.
The restructuring is defensible, and it addresses the most immediate risk, which was financing. Milestone now guides cash runway into late 2028, more than a year beyond the prior 2H 2027 outlook. The RTW note amendment helps by extending the payment-in-kind interest period to March 2029. Most importantly, runway now reaches past the ReVeRA-301 Phase 3 readout in AFib-RVR, expected in 2H 2028. Management estimates that indication's U.S. population at 3 to 4 million patients, roughly three to four times the PSVT opportunity. In effect, Milestone is managing CARDAMYST for efficiency while it waits for a larger binary event. The plan costs about $2 million in one-time charges and is slated to finish by Q1 2027.
Bears have legitimate ammunition. Management warned of a possible Q1 2027 flattening or dip in prescriptions as insurance and out-of-pocket costs reset. National Medicare Part D coverage was called "challenging," and the company will not chase it at any rebate level, so Medicare is not a near-term growth driver. CVS Caremark national coverage is still not secured. The loss of the CFO and CMO in the same announcement adds execution uncertainty. The AFib-RVR trial is event-driven, targeting roughly 150 events across 500 to 700 patients, so its 2028 timing carries some risk.
The market was already pricing in disappointment. Shares were $0.66 heading into the report, down 39.3% from the $1.08 open after the August release. They sat about 50% below the 200-day moving average of $1.32 and just 3.9% above the 52-week low of $0.63 set on October 26. The stock fell from an inter-earnings high of $1.26 in early September to near the bottom of its range. Investor sentiment swung meaningfully, from modestly positive (0.12) to clearly negative (-0.26). Earnings Whispers trend readings are mostly negative on price and AVWAP, with only momentum positive.
The bottom line is that Milestone delivered a cosmetic beat built on a license payment, while the real news was a strategic retreat. Prescription, prescriber and coverage gains are genuine, but they are arriving at a pace that forced a 30% cost cut, a smaller sales force and leadership turnover. The extended runway removes the near-term financing overhang and preserves a path to the 2028 AFib-RVR readout. Until CARDAMYST shows it can grow through the Q1 reset without the spending it just cut, the stock remains a cash-runway and pipeline story rather than a launch story.
Read our earnings preview for Milestone Pharmaceuticals Inc.: https://www.earningswhispers.com/article/MIST/22978
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| Nov-05 | |
| Nov-03 | |
| Nov-03 | |
| Nov-02 | |
| Oct-19 | |
| Oct-09 | |
| Sep-24 | |
| Sep-03 | |
| Sep-02 | |
| Aug-27 | |
| Aug-21 |
