Honest Beats On Record Margins And Faster Organic Growth, But A Sharp Consumption Slowdown Tests The Guidance Raise
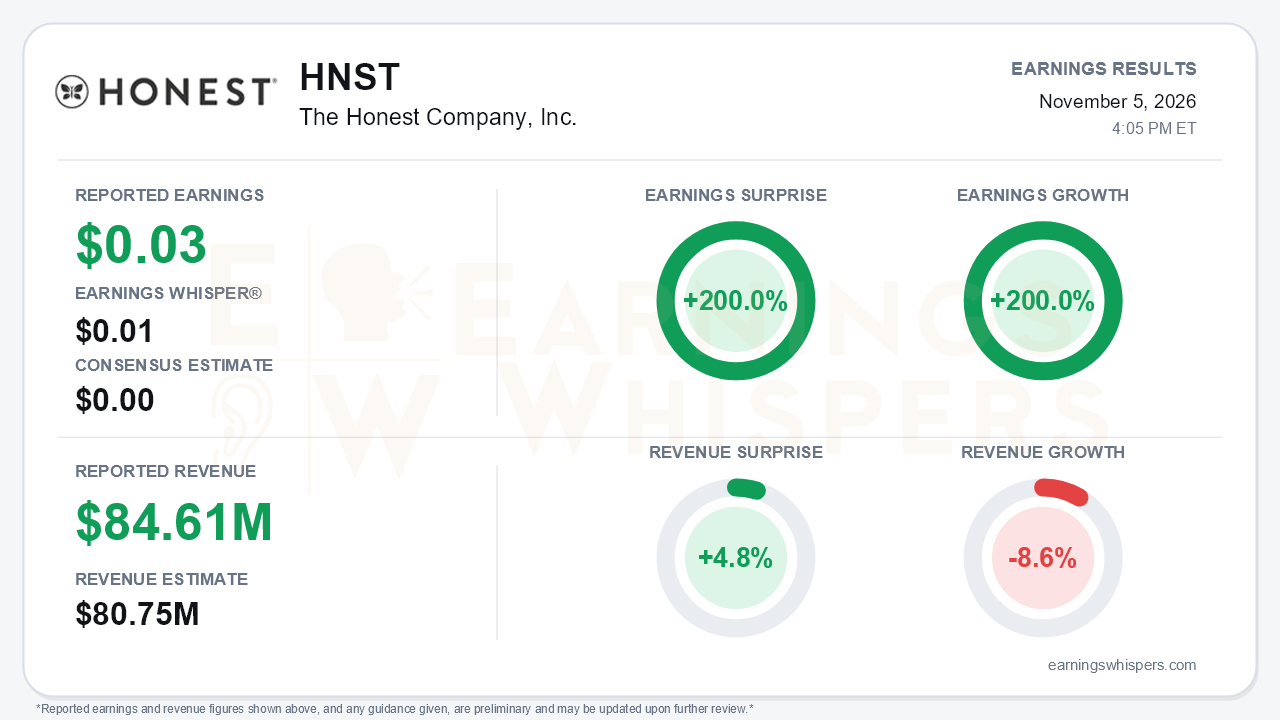
The Honest Company (NASDAQ: HNST) delivered a clean beat on the numbers that matter most to the turnaround thesis. Adjusted earnings of $0.03 per share topped both the $0.00 consensus and the $0.01 Earnings Whisper number, a 200.0% surprise, and earnings grew 200.0% year over year. Revenue of $84.61 million beat the $80.75 million consensus by 4.8% even as it fell 8.6% from a year ago. The central takeaway is that the reshaped portfolio is getting more profitable and growing faster underneath the shrinking top line. The central tension is that shelf-level consumption slowed sharply in the same quarter organic revenue accelerated.
The headline numbers need some unpacking. GAAP net income was $91.3 million, or $0.81 per diluted share, but $89.4 million of that came from releasing the valuation allowance on deferred tax assets. That is a non-cash item, though it is a meaningful signal that management expects sustained profitability. Stripping it out, Underlying Adjusted Net Income was $3.1 million versus $0.8 million a year ago. The reported revenue decline reflects deliberate exits under Powering Honest Growth: Honest.com fulfillment, Canada, and apparel.
That apparel exit also flattered the top line. Reported revenue included $5.3 million from a partial liquidation of remaining apparel inventory that carried zero gross profit, so part of the revenue beat came from non-recurring, profitless sales. The better measure is Organic Revenue, which rose 9.2% to $79.3 million. That continues a steady acceleration from 0.7% in Q4 FY25 to 3.9% in Q1 and 6.7% in Q2. Underlying Adjusted Gross Margin hit a record 48.9%, up 1,160 basis points year over year and up from 43.8% in Q2, helped by supply chain rates and mix. Even GAAP gross margin expanded 770 basis points to 45.0%.
The call preserved the growth story but exposed softer demand signals. Tracked consumption grew just 1.3% in the quarter, down from roughly 8% in both Q1 and Q2. Management attributed most of the slowdown to Prime Day shifting into Q2 and pointed to roughly 6% year-to-date consumption growth. Even so, the deceleration shows up in the growth engines themselves:
- Wipes consumption growth eased to 15% from 26% in Q2.
- Personal care consumption growth slowed to 11% from 19%.
- Diaper consumption fell 27%, far worse than the 9.6% decline in Q1, and management now calls the diaper pressure structural.
Wipes and personal care still outgrew their categories roughly fourfold, and distribution in those platforms is up about 20% year to date. Support for that growth included a CVS launch for hand sanitizing wipes, Toy Story kid care expansion into HEB and Ahold Delhaize, and the Mother of All Standards campaign.
That brand push carries a cost, and it is the main pressure on near-term margins. Marketing rose 20% to $17.7 million, and Underlying Adjusted EBITDA margin of 7.9%, while up 300 basis points year over year, fell from 9.8% in Q2. Management flagged further SG&A and marketing step-ups in Q4 alongside slower implied organic growth.
The outlook still moved higher for a third consecutive quarter:
- Organic growth guidance rose to 6%-7% from 5%-7%.
- Adjusted EBITDA guidance rose to $25-$26 million from $23-$25 million.
- Adjusted gross margin guidance rose to 45.5%-46.5% from "mid-40s."
- The reported revenue range narrowed to $322-$325 million, with only the low end raised. The unchanged top end fits the view that Q4 will cool.
There is also no 2027 gross margin framework yet; management deferred it to early 2027.
Capital returns add support. With $103.0 million in cash, no debt, and $30.5 million in year-to-date free cash flow, the board authorized a new $30 million buyback after completing the prior $25 million program, which retired about 7.2 million shares at an average price of $3.47. One caveat is that cash slipped from $105.9 million in Q2 as inventory timing reversed.
Investor sentiment swung meaningfully, from -0.27 at the prior report to +0.10. That shift moved expectations from skeptical to modestly positive, though not to euphoric levels. Price action tells a more sobering story. Shares surged to a 52-week high of $6.01 in early September, then gave back much of that move. They entered the report at $4.44, down 9.2% since the post-Q2 open, 26% below that high, and only 6.7% above the inter-earnings low set days earlier. The stock does remain about 17% above its 200-day moving average. The Earnings Whispers trend readings are mixed, with momentum positive but sequential growth and AVWAP still negative.
The bottom line is that Honest is executing the transformation it promised: faster organic growth, record margins, a strengthening balance sheet, and a third straight guidance raise. Bears have legitimate ammunition in the consumption slowdown, worsening diaper declines, and a heavier Q4 spending load. Whether Q3's 1.3% consumption figure proves to be Prime Day noise or an early sign of fading momentum will likely determine whether the stock can reclaim its September highs.
Read our earnings preview for The Honest Company, Inc.: https://www.earningswhispers.com/article/HNST/22305
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-15 | |
| Aug-20 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Aug-04 | |
| Jul-21 | |
| Jul-21 | |
| May-19 | |
| May-06 | |
| May-06 | |
| Apr-28 |
