Unusual Machines Misses On GAAP Investment Markdowns, But Revenue Beat And Reaffirmed $25M Q4 Target Shift The Debate To Execution
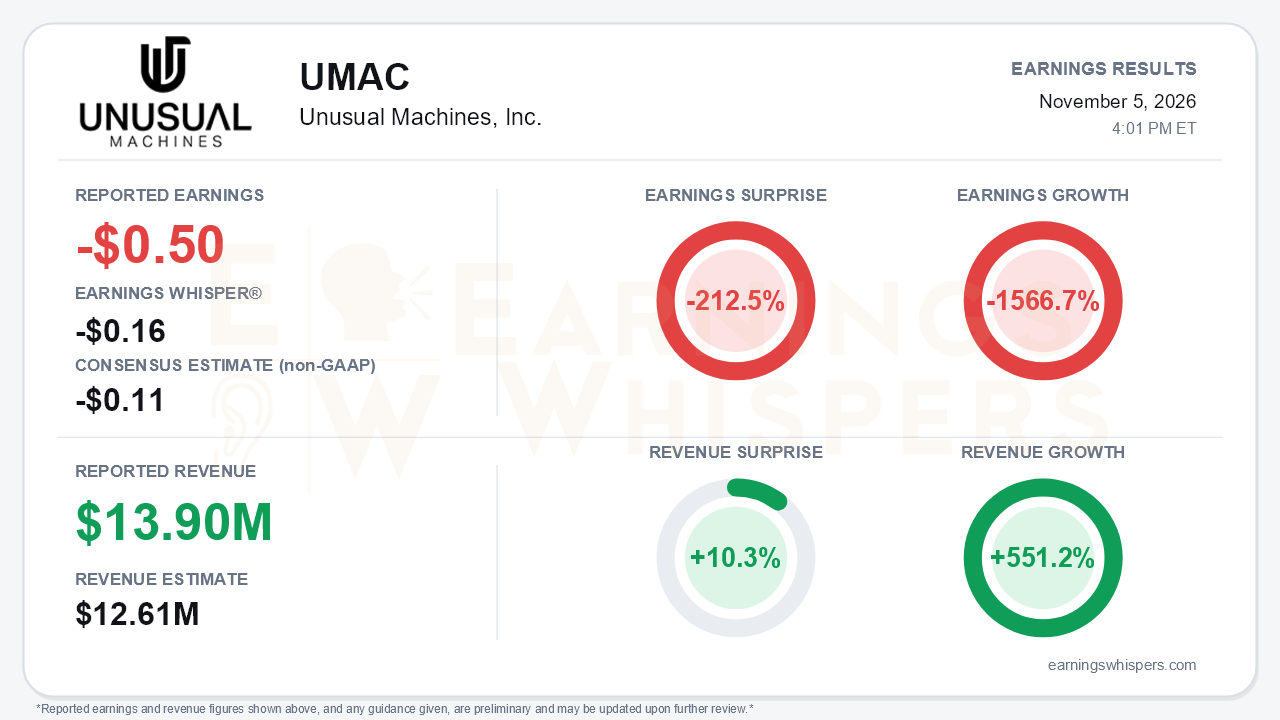
Unusual Machines (NYSE American: UMAC) reported a third-quarter loss of $0.50 per share, far below the consensus estimate of -$0.11 and the Earnings Whisper number of -$0.16. That is a 212.5% miss and a 1566.7% year-over-year decline from a $0.05 profit a year earlier. Revenue told a different story. Sales of $13.9 million beat the $12.61 million consensus by 10.3% and rose 551.2% from a year ago. The comparison needs care: the consensus was a non-GAAP figure, while the reported loss is GAAP. Most of the gap came from an $18.4 million unrealized loss on the company's public equity stakes and $5.5 million of stock compensation, not from the operating business. That is the central tension. The headline miss is largely a mark-to-market event, but the operating story also stumbled. Revenue fell from $16.7 million in Q2 and ended a streak of record quarters.
The quality of the quarter deserves scrutiny from both directions. Management had flagged Q3 as a "building quarter" on the Q2 call, and revenue landed at the top of its $12–14 million internal target. Gross margin edged up to 35.4% from 34.7% in Q2 and 32.8% in Q1, despite the costs of ramping. Adjusted EBITDA was a loss of about $0.7 million, slightly wider than Q2's $0.4 million loss. Underneath, the GAAP picture is harder to dismiss:
- Operating loss widened to $8.4 million from $5.0 million a year ago.
- G&A more than doubled to $10.2 million.
- About $2.0 million of quarterly revenue and $1.9 million of receivables came from related parties.
- The investment book that produced Q1's profit is now swinging the other way, concentrated in three volatile public positions: Powerus, Xtend and XTIA.
The balance sheet is where the bull case is being staked, and where bears have legitimate ammunition. Inventory and prepaid inventory jumped from $42.4 million to $65.9 million in one quarter, against quarterly revenue of $13.9 million. Receivables doubled to $18.7 million. Management frames these as leading indicators of a Q4 ramp. The release's own risk factors acknowledge the possibility of inventory obsolescence. Cash fell from $229.6 million to $162.0 million, driven by $24.8 million of inventory purchases and $35 million of new investments and loans. Net working capital remains substantial at $342.1 million.
On the call, management reiterated its Q4 revenue target of $25 million with "high confidence" and said capacity is fully allocated through Q1 2027. That allocation includes Drone Dominance Phase 2 orders placed in October, a funded Phase 3 for early 2027, and a new $16.9 million Powerus counter-drone order. Management characterized the Q4 risk as operational, not demand-driven. That is a fair distinction, but it puts heavy weight on several moving parts landing on time:
- a new automated motor line said to add 100,000 motors per month;
- roughly 100,000 square feet of additional space;
- integration of Upgrade Energy, with headcount now above 340.
The ongoing OSC loan discussions, which press reports put near $220 million, also remain unresolved. Counter-drone exposure is concentrated in Powerus, with no other customer of similar scale.
The tone shifted in subtle but meaningful ways. Management now concedes that sector valuations have compressed and that private drone customers have less access to capital. It said the company will move toward funding growth internally and expects to be "relatively boring" on M&A and investments for about six months. The 40% gross margin target "may take longer." Positive adjusted EBITDA remains a 2027 aspiration rather than a near-term deliverable. Election-related demand uncertainty and budget timing were also flagged.
The market had already priced in much of this deterioration. Shares fell 45% since the open following the August report, from $23.68 to $13.03. The stock collapsed from an inter-earnings high of $34.93 on August 14, also its 52-week high, and set a quarter low of $11.63 on November 4. It entered the report 62.7% below that peak, near the bottom of its range. Investor sentiment remained negative but improved, rising from -0.19 to -0.11. That suggests expectations had reset lower rather than turned constructive. The Earnings Whispers trend signals are mixed: price and AVWAP readings are negative, while momentum is positive.
The bottom line is that Unusual Machines delivered an ugly GAAP print wrapped around a respectable operating quarter. Revenue topped expectations, margins held, and management reaffirmed an aggressive Q4 target. But the sequential revenue decline, ballooning inventory, investment-driven earnings volatility and a tougher capital environment mean the story now rests almost entirely on execution. A Q4 near $25 million would validate the inventory build and the "building quarter" narrative. Anything short of that would leave investors holding a heavily stocked balance sheet and a GAAP loss that is no longer easy to explain away.
Read our earnings preview for Unusual Machines, Inc.: https://www.earningswhispers.com/article/UMAC/22407
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-22 | |
| Oct-19 | |
| Oct-14 | |
| Oct-11 | |
| Oct-08 | |
| Oct-01 | |
| Sep-30 | |
| Sep-28 | |
| Sep-28 | |
| Sep-15 | |
| Sep-09 |
