Reformation Beats On Revenue And Raises Again, But Slowing Growth And A Stock At Its Highs Raise The Bar
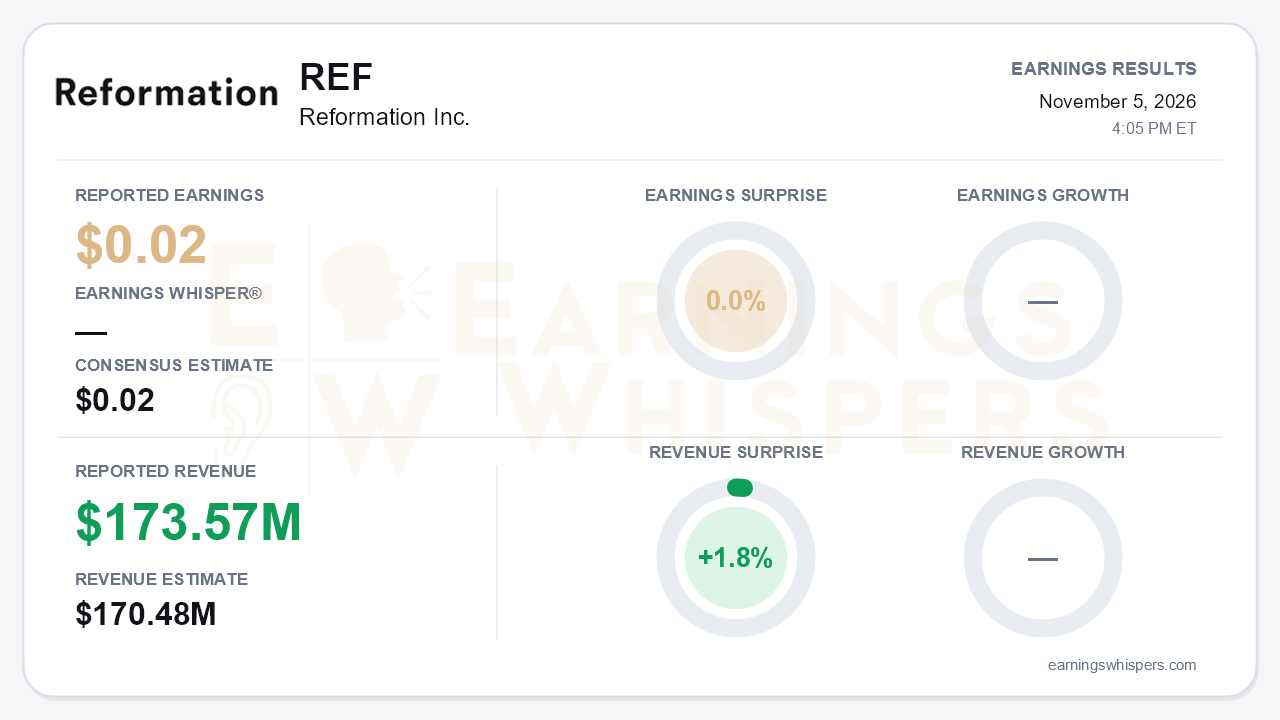
Reformation's second quarter as a public company delivered what growth investors want from a recent IPO: a revenue beat, a guidance raise and margin expansion. It also carried a less comfortable message. Revenue of $173.57 million topped the $170.48 million consensus by 1.8%, and Earnings Whispers' normalized EPS of $0.02 matched expectations. Management lifted full-year revenue guidance to $610-$612 million from $602-$606 million and pinned the adjusted EBITDA margin outlook at about 14.2%, the top of the prior range. Beneath that, top-line growth cooled noticeably. Revenue rose 19.1%, down from 24.1% in the second quarter. That is the central tension: the full-year outlook is improving, but the quarterly growth rate is coming off its peak, and the stock ran hard into the print.
The EPS picture requires care. The normalized $0.02 matched consensus, but on a GAAP basis Reformation reported a net loss of $1.1 million, or $(0.02) per share. A year earlier it earned $5.0 million, and in the second quarter it earned $12.4 million. The loss was largely mechanical. IPO-related stock compensation lifted SG&A 33.5%, accounting for roughly 590 basis points of deleverage, and a 165.9% effective tax rate reflected limits on deducting executive compensation after the IPO. A $2.2 million debt-extinguishment loss also weighed. Strip those out and operations were strong. Gross margin expanded 252 basis points to 60.4%, adjusted EBITDA jumped 64.2% to $23.1 million, and the adjusted EBITDA margin widened 366 basis points to 13.3%. The quality of that margin gain deserves some scrutiny. Lower tariff rates and about 50 basis points of vendor refunds of IEEPA tariffs helped, alongside 3-4% higher average unit retail and better full-price selling.
Customer metrics were the cleanest part of the report. Active customers grew 23.4% to 1.25 million, matching the second quarter's pace. DTC revenue per customer improved sequentially to $419, down 0.5% year over year compared with a 1.4% decline last quarter. That suggests the dilution from rapid new-customer acquisition is easing. The deceleration was broad, however:
- **DTC:** growth slowed to 16.7% from 21.2%.
- **Wholesale:** growth eased to 40.8% from 48.7%.
- **International:** growth fell to 24.7% from 36.8%.
Management's tone was upbeat. Executives said October trading was strong and that wholesale reorders came in earlier than expected ahead of the holiday. They now frame full-year growth as above 20%, well ahead of the company's mid-to-high-teens long-term algorithm.
The call added several tangible catalysts:
- An Alexa Chung collaboration is carrying average unit retail more than 25% above the rest of the assortment.
- A new AI-based planning engine supports demand forecasting and factory allocation.
- New stores are performing ahead of internal projections. The Santana Row opening lifted DTC growth in that market by about 30% and new-customer growth by about 90%, while the reopened Palisades store and new Birmingham location added to the store count.
Bears still have legitimate ammunition:
- **Gross margin:** the CFO flagged a first-half 2027 headwind as the company laps a tariff-free first quarter and this year's tariff refunds.
- **Costs:** shipping, fuel and public-company expenses are rising.
- **Inventory:** it rose 36% to $83.8 million against 19% sales growth. Management attributed about a third of the increase to a deliberate raw-materials build for speed to market, and the prior-year base was atypically low.
- **Fourth-quarter guidance:** management described it as prudent, but more than two-thirds of the selling period was still ahead at the time of the call.
The market setup is more complicated than the beat implies. Investor sentiment swung sharply from -0.56 after the September report to +0.11 ahead of this one. Expectations moved from clearly negative to modestly positive. Shares rose 40.5% from the $13.10 open after the prior report to $18.41. They ended the pre-report snapshot just below an inter-earnings and 52-week high of $18.44 set on November 4, roughly 55% above the September 30 low of $11.85, and about 26% above the 200-day moving average. The AVWAP trend is also positive. The stock entered earnings priced for a good quarter rather than braced for a disappointing one.
The bottom line is that Reformation delivered a credible beat-and-raise. Customer growth was durable, adjusted profitability improved sharply, and full-year targets now exceed the company's own algorithm. The GAAP loss was largely an IPO artifact rather than an operating problem. The harder questions are the decelerating quarterly growth rate, tariff tailwinds that reverse next year and an inventory build that must sell through. With the stock near its highs and sentiment no longer depressed, the next leg depends on whether holiday execution and the 2027 margin outlook can hold up against tougher comparisons.
Read our earnings preview for Reformation Inc.: https://www.earningswhispers.com/article/REF/22370
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Nov-04 | |
| Oct-28 | |
| Oct-22 | |
| Sep-10 | |
| Sep-10 | |
| Aug-27 | |
| Aug-24 | |
| Aug-07 | |
| Jul-31 | |
| Jul-30 | |
| Jul-30 | |
| Jul-30 |
