Main Street Capital Misses As Earnings Power Steps Down, While Record NAV, Better Credit And A Dividend Raise Hold The Story Together
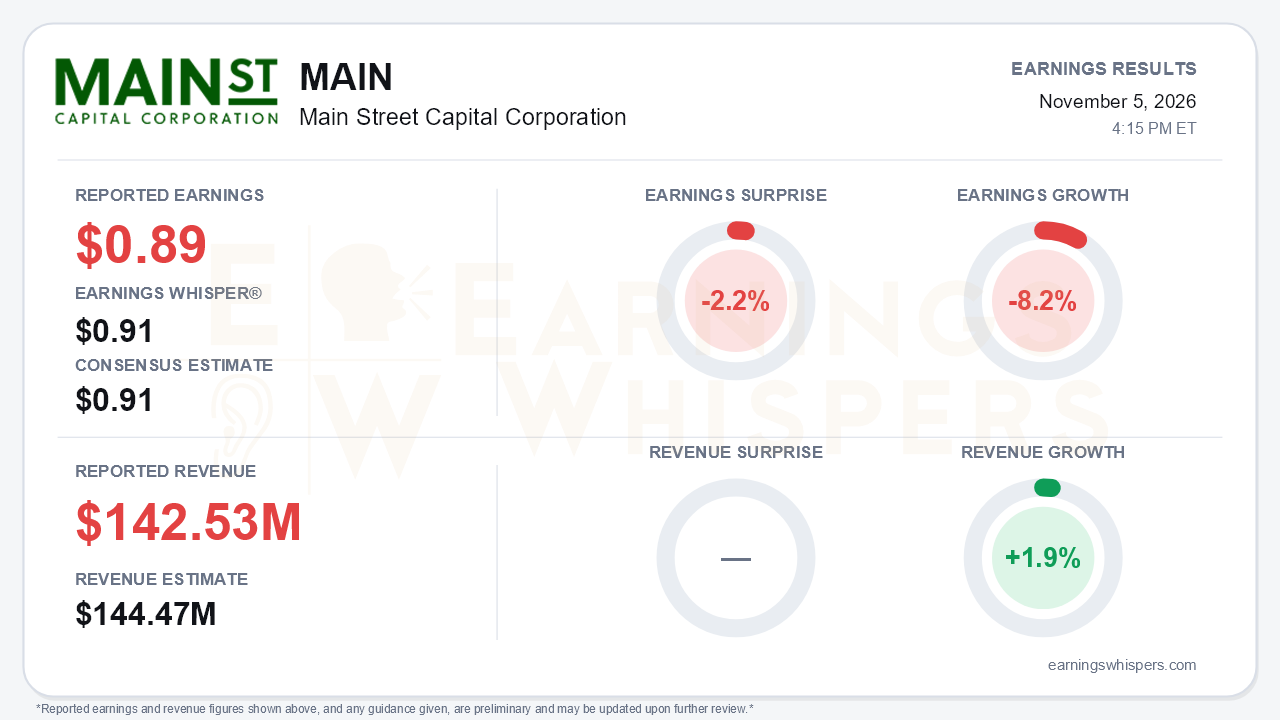
Main Street Capital (NYSE: MAIN) reported third-quarter net investment income of $0.89 per share. That was 2.2% below both the $0.91 consensus and the Earnings Whisper number, and 8.2% lower than a year ago. Total investment income of $142.53 million rose 1.9% year over year but missed the $144.47 million consensus by 1.3%. The company can say it hit its own target: distributable NII before taxes of $0.98 per share cleared the 'at least $0.97' guidance from the prior call. That is a non-GAAP measure, though, and it does not change the core finding. A record $34.22 NAV, improving credit and another dividend increase sit alongside a clear step-down in quarterly earnings power. That is the central tension.
The trajectory matters more than the size of the miss. Distributable NII before taxes has fallen from $1.11 in the fourth quarter of 2025 to $1.04, then $1.08, and now $0.98. Annualized ROE dropped to 14.7% from 18.9% in the second quarter. Total investment income fell 4.7% sequentially, with fee income down $4.4 million and less-recurring income slipping to $6.1 million from $9.5 million.
The year-over-year detail is equally telling. Interest income rose $8.6 million on a larger debt book, but three items worked against it:
- Dividend income fell $5.7 million, driven by a $6.9 million drop from lower middle market (LMM) companies.
- Interest expense climbed $6.4 million as cheap debt was replaced at higher unsecured rates. The 3.00% July 2026 notes were repaid, while the newer issues carry coupons of 6.55% to 6.93%.
- A 4.6% increase in the share count, much of it from ATM issuance, diluted per-share results.
In other words, the quality of the miss deserves scrutiny. It reflects structural pressure rather than a one-off timing issue.
The call explained what is changing beneath the portfolio. Management acknowledged that some LMM companies are seeing earnings and cash flows decline and are allocating capital more conservatively, which pressures the equity dividends that have long distinguished Main Street's model. Net portfolio growth turned negative for a second straight quarter:
- LMM cost basis fell $19 million, after a $31 million decline in the second quarter.
- Private loans slipped $2 million.
That compares with net LMM additions of $253 million and $157 million in the two quarters before. The LMM pipeline remained 'average,' down from 'above average' late last year. Management's tone also cooled from 'very pleased' to 'pleased,' and the quarter lacked the kind of exit gain that lifted the second quarter.
The offsetting evidence is credible:
- **Credit:** Non-accruals improved to 0.9% of fair value from 1.1%, though they remain 3.5% at cost.
- **Valuations:** $68.5 million of net unrealized appreciation, roughly $27 million of it accounting reversals, more than absorbed $27.6 million of realized losses, pushing NAV up 0.9% sequentially.
- **Pipeline:** The private loan pipeline was upgraded to 'well above average' from 'average,' with pricing described as in line with history.
- **Exits:** Buyer interest in several LMM companies could produce realizations over the next few quarters.
The forward signals are mixed rather than weak. Guidance calls for at least $0.98 of distributable NII before taxes in the fourth quarter, a penny above the prior guide, which may indicate earnings are stabilizing. However, the guide has drifted down from $1.04 at the start of the year.
Shareholder returns remain well supported. The release declared fourth-quarter regular monthly dividends of $0.265, and the call added an increase to $0.27 for the first quarter of 2027 along with the 21st consecutive $0.30 supplemental. Distributable NII of $0.96 comfortably covers the $0.795 quarterly regular payout. Total third-quarter dividends of $1.095 exceeded current earnings, so the supplemental relies on undistributed income and future gains.
The balance sheet is a genuine strength, though the two liquidity figures need reconciling. The release shows $1.218 billion at September 30. The $1.6 billion cited on the call reflects October's $500 million January 2030 note issue and the expanded $425 million SBIC capacity. Bears still have legitimate ammunition on funding costs: the June 2027 notes and the first low-cost SBIC debenture maturities in 2027 will reprice, and the call flagged expectations for higher base rates.
Investor sentiment moved decisively from mildly negative (-0.14) at the prior report to clearly positive (+0.34). The stock has barely moved, up 0.6% since the open after the August report and sitting 2.6% above its 200-day moving average. The market setup is therefore more complicated than the surprise implies. Expectations improved heading into a quarter that delivered a modest miss, while the price shows investors paying for stability rather than growth.
The bottom line is that Main Street remains a high-quality, conservatively financed BDC whose per-share earnings power has reset lower. Record NAV, better credit, ample liquidity and a stronger private loan pipeline give the dividend story credibility. The next leg depends on converting that pipeline into net portfolio growth and stabilizing LMM dividend income before higher financing costs erode the $0.98 baseline further.
Read our earnings preview for Main Street Capital Corporation: https://www.earningswhispers.com/article/MAIN/22334
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-28 | |
| Oct-27 | |
| Oct-16 | |
| Oct-15 | |
| Oct-15 | |
| Oct-08 | |
| Oct-08 | |
| Sep-29 | |
| Sep-21 |
