MSC Income Fund Misses On Earnings And Revenue As The Dividend Leans On Fee Waivers While Management Bets On An Upgraded Pipeline
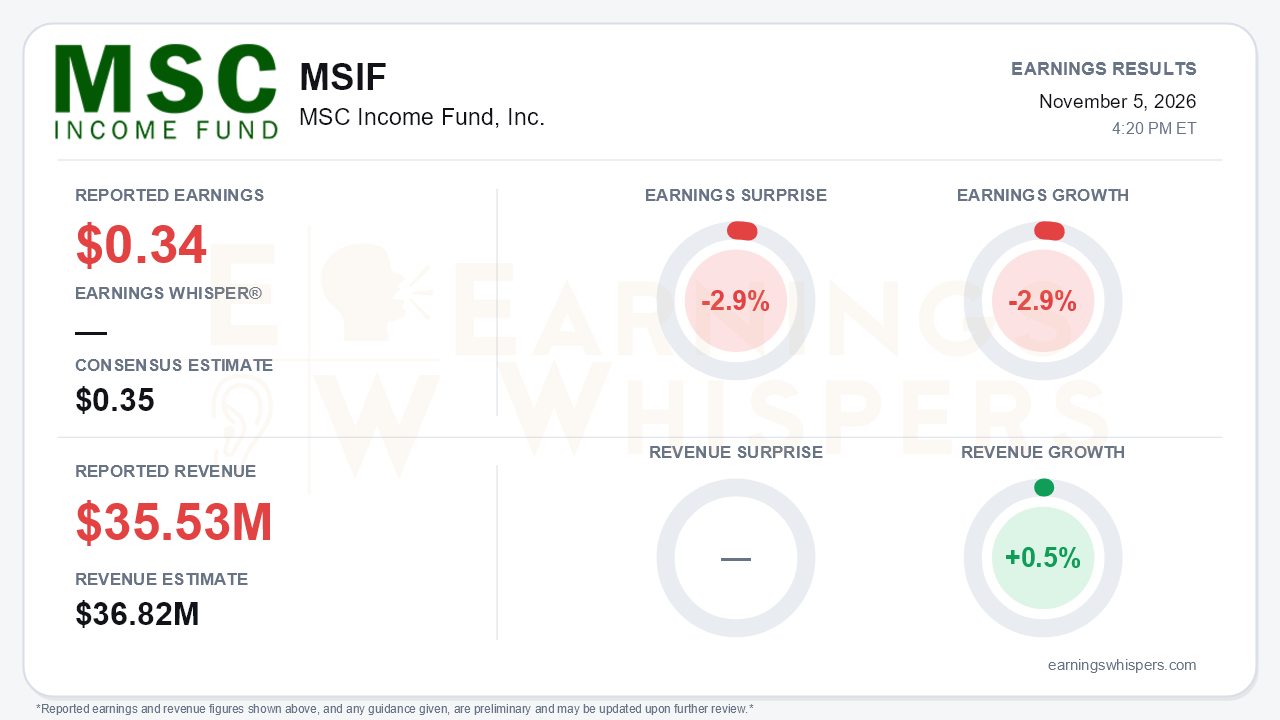
MSC Income Fund (NYSE: MSIF) reported adjusted net investment income of $0.34 per share for the September quarter. That missed the $0.35 consensus by 2.9% and was down 2.9% from a year ago. Total investment income of $35.53 million fell 3.5% short of the $36.82 million consensus and grew just 0.5% year over year. On a GAAP basis, NII was $0.32, versus $0.35 a year earlier, after a $0.02 per share capital gains incentive fee accrual. The quarter's central tension is that management sounded more confident about the future than at any point this year, while the portfolio actually shrank and dividend coverage depended more heavily on the adviser's generosity.
The quality of the quarter deserves scrutiny. Adjusted NII before taxes of $0.36 matched the $0.36 in total dividends declared ($0.33 in regular monthly payouts plus a $0.03 supplemental). Several supports made that match possible:
- **Fee waiver:** Main Street waived about $0.6 million of incentive fees, up from roughly $0.26 million in the second quarter.
- **Non-recurring income:** Income the fund itself describes as less consistent or non-recurring added $0.02 per share versus the prior-year period.
- **Lower share count:** A 4.2% decline in weighted-average shares, mostly from repurchases, flattered per-share results.
Against those supports, interest expense rose $1.3 million year over year as cheaper floating-rate borrowings were replaced with higher-coupon unsecured notes. Fee income also slipped. Management conceded on the call that deployment is needed to cover the dividend without the waiver. That is the right diagnosis, but it means the current payout is not yet self-funding.
Deployment is where the quarter disappointed most. The fund invested $61.4 million in private loans, yet repayments, returned equity, and realized losses left the private loan cost basis down about $10.5 million. That compares with net growth of roughly $10 million in Q2, $17 million in Q1, and $57 million in Q4 of fiscal 2025. Lower middle market follow-on investments fell to about $4 million, from $13 million in Q2 and $23 million two quarters before that. Realized results were mixed:
- An $11.0 million gain on the Core Transformers exit was more than offset by a $9.4 million loss on a private loan restructuring and a $6.4 million loss on a long-held LMM exit.
- Net realized losses came to $3.9 million.
- Annualized return on equity dropped to 9.7%, from 15.9% in Q2.
The bull case rests on the forward-looking evidence, and it is not trivial. Management upgraded the private loan pipeline to "well above average," from "average" in each of the first two quarters. One new private loan has closed since quarter-end, and several more are expected before year-end, which management said could produce a significant move in Q4. Credit metrics also improved sequentially:
- Non-accruals declined to 1.4% of the portfolio at fair value and 5.2% at cost, from 1.9% and 5.8% in Q2. They nonetheless remain above the 3.9%-at-cost level of late 2025.
- NAV per share edged up to $16.56 from $16.51 and is 4.5% above year-end.
- The $150 million October 2026 maturity has been fully refinanced with the new September 2029 notes, and KBRA reaffirmed its BBB- rating.
Bears still have legitimate ammunition here. The refinancing replaces 4.04% paper with 6.83% notes, a structural headwind to NII. Management also dropped its earlier "three to four quarters" framing for reaching target leverage and now offers no specific timeframe, noting that M&A activity has not picked up drastically. An upgraded pipeline paired with a vaguer deployment timeline is a combination investors should weigh carefully.
Investor sentiment improved meaningfully, moving from roughly neutral (-0.03) before the prior report to modestly positive (0.26). That suggests investors are giving more weight to the pipeline and NAV stability than to the shrinking book. Price action has been more restrained. Shares are up 3.4% since the open following the August report, at $12.25, essentially sitting on the 200-day moving average of $12.26. The stock still trades at roughly a 26% discount to NAV, which explains why the fund activated a $20 million repurchase plan triggered by NAV discounts. Main Street has also been buying and now owns more than 5% of the fund. Those purchases signal sponsor confidence, but they also underline how persistently the market has questioned the fund's earnings power. The November 9 transition to Nick Meserve as CEO, who has run the private credit strategy, provides continuity rather than a strategic shift.
The bottom line is that MSIF delivered a modest miss on both lines and a flat-to-shrinking portfolio. The dividend was covered only with help from waivers, non-recurring income, and a lower share count. Offsetting that, NAV, credit, and the balance sheet look sturdier, and management is pointing to its strongest pipeline of the year. Whether the stock can narrow its deep NAV discount now depends on that pipeline translating into net portfolio growth in Q4. Without it, rising financing costs and reliance on fee waivers will keep coverage questions front and center.
Read our earnings preview for MSC Income Fund, Inc.: https://www.earningswhispers.com/article/MSIF/22342
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-16 | |
| Oct-08 | |
| Oct-02 | |
| Sep-16 | |
| Sep-01 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Aug-06 | |
| Aug-05 | |
| Aug-03 |
