Ring Energy Beats Easily, But Capex Overrun, Negative Free Cash Flow And Trimmed 2027 Volumes Cloud A Margin-Driven Quarter
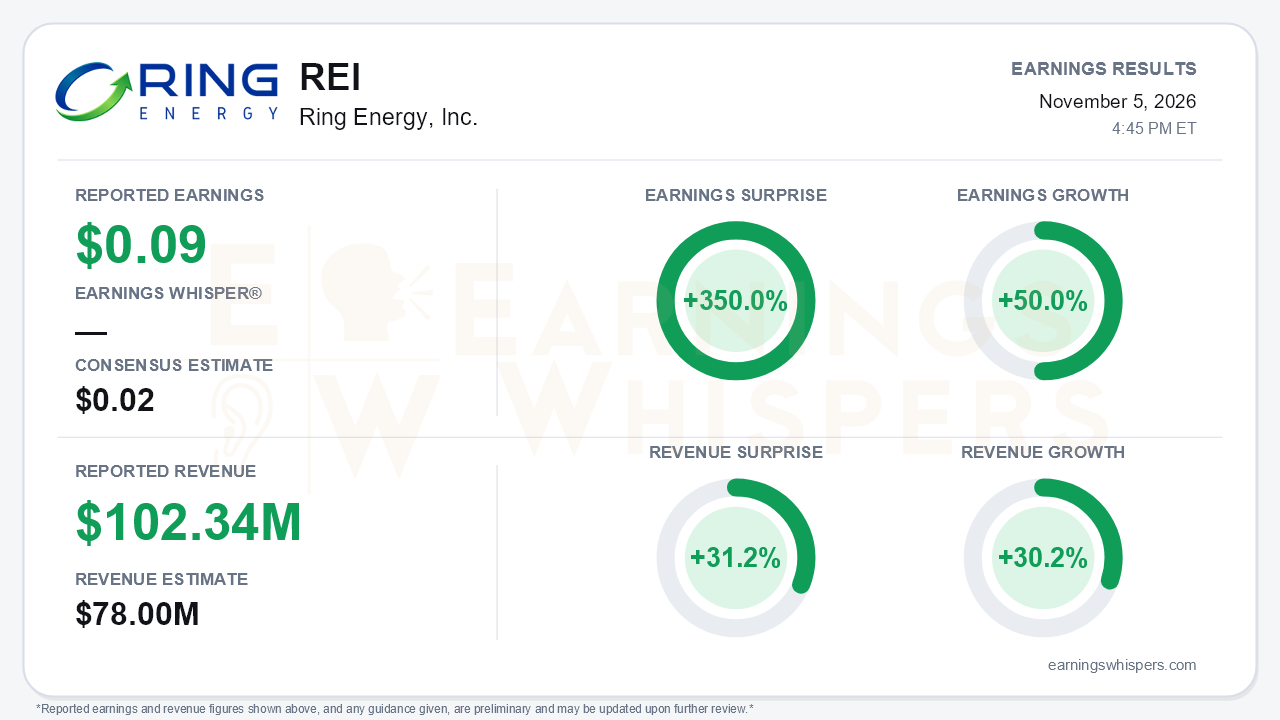
Ring Energy delivered a large headline beat for the third quarter. It reported earnings of $0.09 per share against a $0.02 consensus, a 350.0% surprise, on revenue of $102.34 million, 31.2% above the $78.0 million estimate. Earnings grew 50.0% and revenue 30.2% from a year earlier, driven mostly by a realized oil price of $83.72 versus $64.32 in the year-ago quarter. The central tension is that the beat landed in what management itself framed as a deliberate investment quarter. Margins and leverage improved, but spending ran ahead of plan, adjusted free cash flow turned negative, and the volume outlook for 2026 and 2027 was trimmed.
The quality of the beat deserves scrutiny on several fronts. On a GAAP basis, Ring posted a net loss of $16.6 million, or $0.06 per share, because of a $41.0 million unrealized loss on commodity derivatives. Its own adjusted figure was $27.3 million, or $0.10 per share. That adjusted result was flat per share with the second quarter even though adjusted net income rose 14%. The share count climbed to roughly 260.5 million from 206.7 million a year ago following the second-quarter equity raise, so year-over-year growth of about 108% in adjusted net income shrank to 50% per share. Sequentially, the trend stalled. Revenue slipped 2% to $102.3 million and the realized oil price fell 12% from $95.45. Hedging also remains a drag: Ring realized $12.2 million of derivative losses, and fourth-quarter oil swaps sit near $70.60.
Beneath the headline, the operating story is better than the revenue line suggests:
- Adjusted EBITDA rose 5% to $57.1 million, and margin expanded to 56% from 52%.
- Gas realizations swung to -$0.30/Mcf from -$5.20 as Permian takeaway constraints eased.
- All-in cash costs fell 3% to $21.03 per Boe, and LOE of $10.20 came in below the guidance midpoint.
- Volumes rose 3% to 20,635 Boe/d.
- The first five two-mile co-developed laterals in Crane County came online, mostly late in the quarter, and proved horizontal targets expanded from two to five.
The cost of that progress was capital. Spending of about $64.0 million, up 48% sequentially, drove adjusted free cash flow to negative $13.8 million. That ended a streak management had highlighted as 26 consecutive positive quarters as recently as the first-quarter call. Third-quarter capex plus the $43-$48 million fourth-quarter guide implies roughly $107-$112 million for the second half, above the $80-$100 million framework given on the second-quarter call. Management argued the outspend was intentional, given strong prices and divestiture cash, and said it intends to be cash flow positive in the fourth quarter and for the full year.
Guidance is where bears have legitimate ammunition. Ring cut its 2027 guidance, with oil now at 13,200-14,300 Bo/d and total production at 21,000-23,000 Boe/d, midpoints lower by about 350 Bo/d and 500 Boe/d. The call analysis indicates divestitures explain only about 80 Bo/d of the oil reduction. Fourth-quarter oil guidance of 12,900-13,500 Bo/d also implies a second half below the prior 13,475 midpoint. Management acknowledged that pad co-development makes production lumpy, causing shut-ins at offset wells, and asked shareholders to be patient. It also said second-half 2027 capex is contingent on oil prices.
The balance-sheet narrative is the most credible positive. Ring sold about $30.5 million of non-core assets and recycled $18.8 million into roughly 16.5k net acres of core Central Basin Platform leasehold. It cut revolver borrowings to $350 million from $420 million at year-end. Leverage on an annualized last-quarter basis fell to 1.5x from 1.7x, though the trailing covenant measure was 1.87x. Liquidity reached about $236 million, and a further $13.4 million divestiture closed October 30. Management is targeting leverage below 1.0x in 2027 if prices hold. It has also upgraded hedges to keep first-half 2027 free cash flow positive at $65 WTI, with a borrowing base redetermination due in December.
Investors had already grown more cautious. Earnings Whispers sentiment remained positive but roughly halved, falling to 0.32 from 0.64. Shares have dropped 12.5% since the open following the August report, to $1.12, and sit about 17% below the 200-day moving average of $1.36. The market has been discounting the stock despite firmer commodity realizations, and this report does little to resolve the execution questions behind that discount.
The bottom line is that Ring's headline beat rests on higher year-over-year oil prices and wider margins, while the forward signals moved the other way. Capex ran over, free cash flow turned negative, and 2027 volumes were cut by more than divestitures explain. The deleveraging and portfolio high-grading are real progress. The quarters ahead need to show that the two-mile laterals translate into the production growth management has asked investors to wait for.
Read our earnings preview for Ring Energy, Inc.: https://www.earningswhispers.com/article/REI/22372
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-22 | |
| Oct-08 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 | |
| Jul-31 | |
| Jul-23 | |
| Jul-22 | |
| Jul-08 | |
| Jul-02 | |
| Jun-29 |
