Regency Centers Lands A Cent Short Of The Whisper As Record Occupancy Lifts 2026 But A Slower 2027 Comes Into View
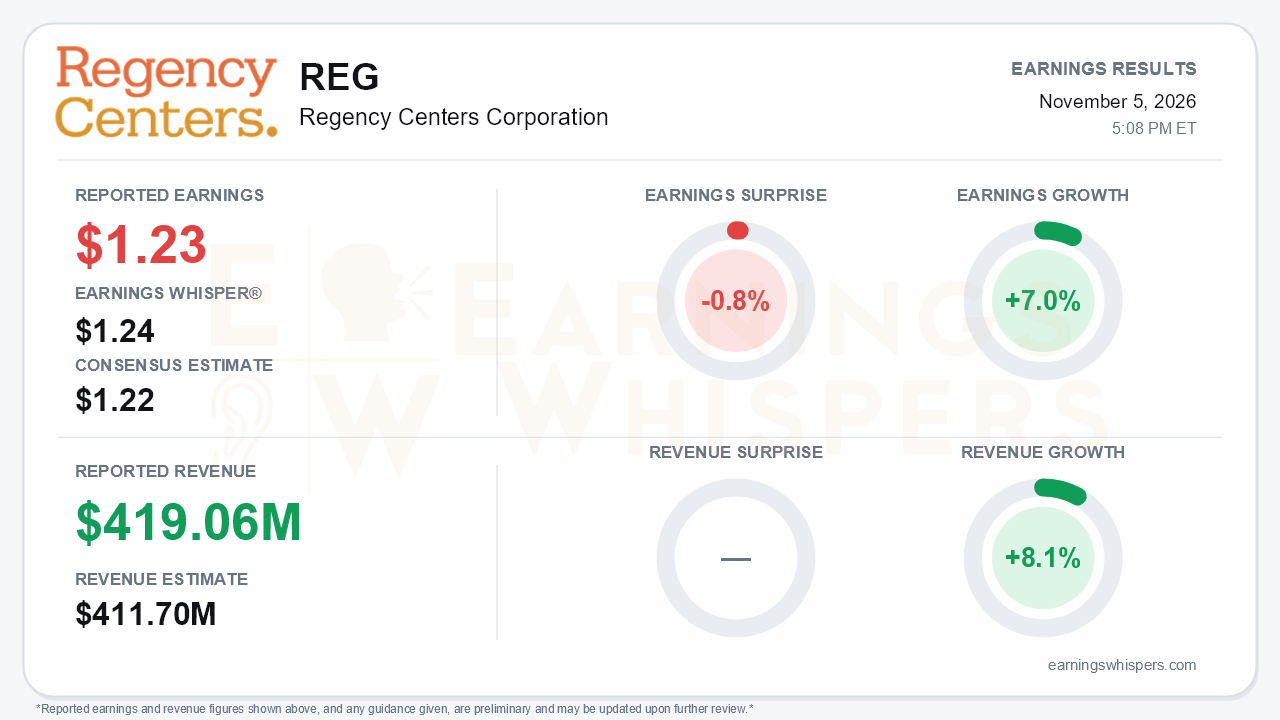
Regency Centers (NASDAQ: REG) reported third-quarter Nareit FFO of $1.23 per share. That was a penny above the $1.22 consensus but a penny below the $1.24 Earnings Whisper number, a 0.8% shortfall against the bar investors were actually watching. Revenue of $419.06 million beat consensus by 1.8% and grew 8.1% year over year, while earnings grew 7.0%. On its own, the quarter was clean. Same-property NOI rose 5.1%, ahead of the 4.4% year-to-date pace, and full-year targets moved up again. The central tension is timing. This quarter likely marks the high-water mark of the current growth cycle, and management's first look at 2027 points to slower internal growth and a heavier financing drag.
The quality of the quarter is mostly good, with a few caveats. GAAP net income fell to $0.41 per diluted share from $0.58. That decline came from a $65.1 million impairment ($0.35 per share), partly offset by $23.8 million of real estate gains, and both items are excluded from FFO. The impairment also explains why full-year GAAP EPS guidance dropped to $2.31-$2.33 from $2.48-$2.52.
The company describes its FFO guidance as raised. In practice it narrowed: the $4.86-$4.88 range lifts the low end and leaves the top unchanged. Core Operating Earnings guidance moved to $4.65-$4.67 from $4.62-$4.66, implying 5.7% growth at the midpoint, up from 4.5% earlier in the year. Even so, the updated full-year ranges imply fourth-quarter results that are roughly flat to slightly lower than the third quarter, not a continued step-up.
It also matters where the same-property growth came from. Excluding redevelopments, same-property NOI grew 3.5%, so redevelopment contribution did a meaningful share of the work. A better expense recovery ratio (87.5% versus 85.7%) also helped.
The operating story from the call is strong and broad-based:
- Same-property leased occupancy reached a record 97.0%.
- Shop leased rose to a record 94.6%, up from 94.2% at year-end 2025.
- Commenced occupancy hit a record 95.1%, up 80 basis points year over year.
- Renewal cash spreads improved to 15% from 13%.
- Tenant retention peaked at 84%.
- Nearly all new shop leases carry annual rent steps of 3% or more.
- Base rent contributed 4.0% to same-property NOI growth, up from 3.5% in the first quarter.
Same-property NOI guidance has now risen from 3.25%-3.75% at the start of the year, to 3.7%-4.1% last quarter, to 4.25% or better. One softer data point stands out: GAAP rent spreads eased to 22% from a record 25% at year-end 2025.
The forward catalysts are real:
- **Development:** 2026 starts are tracking toward roughly $400 million, compared with more than $300 million in 2025 and about $250 million in 2024. New starts include a Whole Foods-anchored project in Redlands and a Sprouts-anchored project in Morgan Hill, and Kroger's fleet expansion is adding opportunities.
- **Pipeline:** The in-process pipeline grew to $682 million at a blended yield of about 9%.
- **Acquisitions:** The company is running more than $170 million year to date, partly funded with joint-venture capital that has room to do more.
- **Balance sheet and dividend:** Leverage sits at 4.9x, and the 6% dividend increase to $0.80 signals board confidence.
Bears have legitimate ammunition for 2027, however:
- Management pointed same-property NOI toward the mid-3% area, down from 4.25% or better this year.
- Gains in commenced occupancy are fading, from about 150 basis points in 2025 to about 80 in 2026 and an expected 40-50 in 2027, which management described as occupancy-neutral.
- Bad debt is expected to normalize to about 50 basis points from about 25.
- The drag from refinancing debt widens to 150-200 basis points of earnings growth, versus 100-150 this year.
Add volatile rates complicating acquisitions, Albertsons reviewing its real estate, and new development yields capped around 7%-8% versus the pipeline's roughly 9%, and the growth algorithm looks set to compress.
The market appears to be anticipating that shift rather than rewarding this year's upgrades. Earnings Whispers investor sentiment remained negative and weakened further, falling from -0.26 to -0.41. That is a meaningful move toward skepticism heading into the print. Shares at $76.28 are down 4.7% from the $80.04 opening after the July report, despite a quarter of record occupancy and higher guidance. The stock sits just 0.6% below its 200-day moving average of $76.74, effectively at that line. That positioning reflects a market treating Regency as a high-quality operator whose good news is largely priced, while the 2027 deceleration is not yet fully digested.
The bottom line is that Regency delivered another quarter of strong execution: record leasing, accelerating same-property NOI, higher 2026 targets and a dividend hike. A one-cent miss against the whisper is not the issue. What changed the investment setup is the 2027 preview, with slower same-property growth, a larger refinancing drag, normalizing bad debt and little help from occupancy. The development pipeline offers a credible offset, but investors appear focused on the slowdown rather than on the beat.
Read our earnings preview for Regency Centers Corporation: https://www.earningswhispers.com/article/REG/22371
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Sep-30 | |
| Sep-11 | |
| Sep-10 | |
| Sep-09 | |
| Aug-06 | |
| Aug-05 | |
| Jul-30 | |
| Jul-29 | |
| Jul-29 | |
| Jul-02 | |
| Jun-25 |
