Draganfly Needs A Revenue Step-Up To Show Its Delayed Ramp Is Back On Track
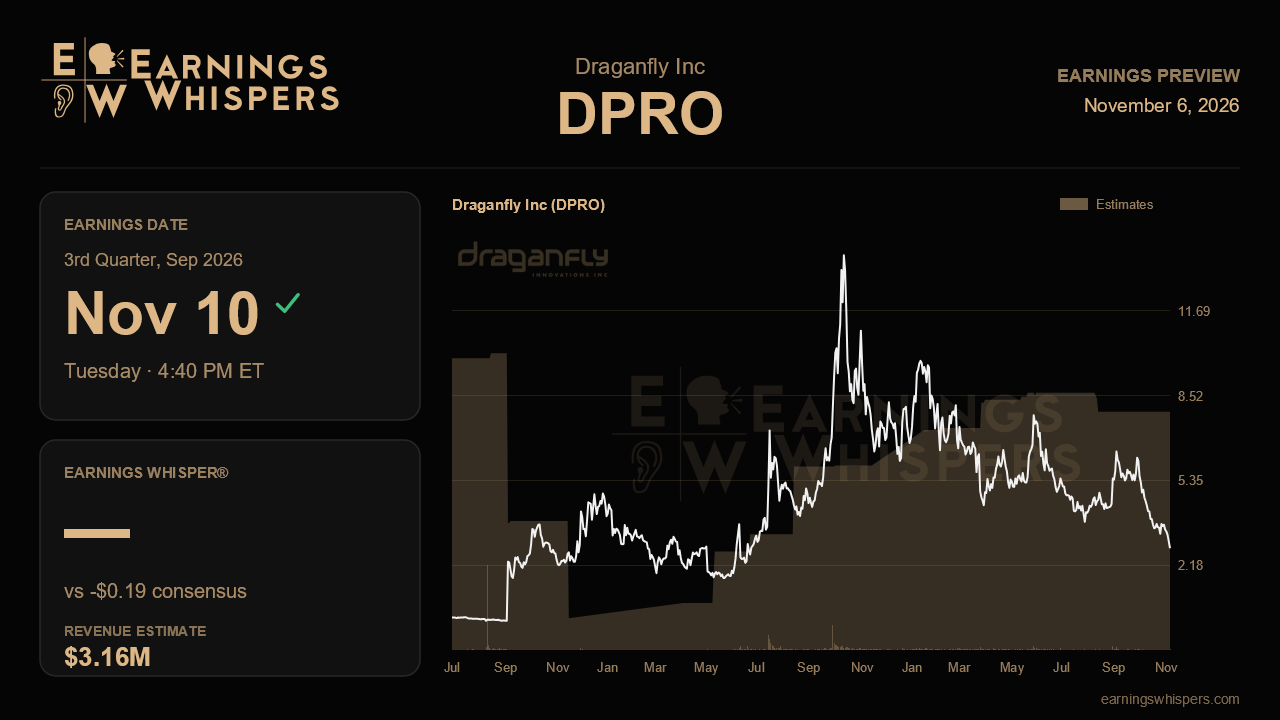
Draganfly enters its September-quarter report with a credibility test rather than a numbers test. Last quarter brought record revenue, the best gross margin in a year and an unusually long list of new deals. Management also admitted something it had not said so plainly before: its revenue ramp has been meaningfully delayed. The stock has lost roughly a third of its value since. When results arrive after the close on November 10, the question is whether the pipeline is finally turning into sales, or whether the delay is stretching further out.
The Street is asking for a lot on the top line. Consensus calls for about $3.2 million in quarterly revenue, roughly double the $1.6 million reported a year ago and a clear step up from the record of about $2.7 million management reported last time. The loss is expected to be about $0.19 per share, slightly wider than the $0.18 lost a year earlier and narrower than the $0.24 in the prior report. Draganfly still gives no formal guidance, so there is no company range to measure that $3.2 million against. That leaves the estimate resting on analysts' reading of a pipeline management itself described as slower to convert than hoped.
The last call sets out what would support that estimate. Year-over-year revenue growth slowed to 26% from nearly 50% the quarter before. Management blamed buyers who have become more discerning and keep refining specifications mid-order, which forces redesigns and pushes out deliveries. Revenue near $3.2 million would suggest those order changes are clearing. Evidence that the Flex FPV wins with Special Forces units are producing follow-on orders would also help. The defense business matters most here. The DEVCOM counter-drone award, which management framed as potentially worth hundreds of millions of dollars over several years, needs signs of early contract activity. Other recent catalysts should not be expected to show up in the numbers yet. Management has pointed to the second quarter of next year for meaningful revenue from the IACLEA campus program. The Skip Dynamics acquisition was described as a talent and technology purchase with no near-term revenue. The new rural police association deal, the ACSL partnership in Canada and the optics business are early-stage efforts. For now they are evidence of demand, not of sales.
Margins and cash burn are the second test. Gross margin rose to 20% last quarter from 15% in the prior period and under 5% two quarters before that. Holding or improving that level on higher volume would show the business can scale. The comprehensive loss doubled to $11.8 million, however, as spending on staff, research, professional fees and travel climbed. Some non-cash derivative and inventory charges added to the total. Cash fell to $131.9 million from $147 million in one quarter. That is still a large cushion for a company of this size. Even so, another sharp drop alongside flat sales would show spending running well ahead of revenue.
Sentiment has warmed noticeably, swinging from clearly bearish before the last report to modestly bullish now, even as the share price has slid. The stock has fallen 34.4% since the prior report, about 29 points worse than the S&P 500. At $2.81 it sits well below its 200-day moving average of $5.57 and only a few percent above its post-earnings low of $2.68. The current trading range is entirely below the previous quarter's range. The market has already priced in a good deal of disappointment. Whether that creates opportunity depends on what the report shows.
In the end, this quarter turns on conversion. Revenue at or above $3.2 million would show the delayed ramp moving again, especially if gross margin holds near 20% and cash burn eases. Another quarter of record announcements paired with a revenue shortfall would point the other way. It would suggest the ramp management pushed out last quarter is slipping again, which is the scenario the share price has been pricing in.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| 13 hours | |
| Oct-27 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-28 | |
| Sep-11 | |
| Sep-10 | |
| Sep-09 | |
| Sep-08 |
