Draganfly Misses Badly And Pushes Its Revenue Inflection Into 2027, Even As Canadian Defence Wins Start To Land
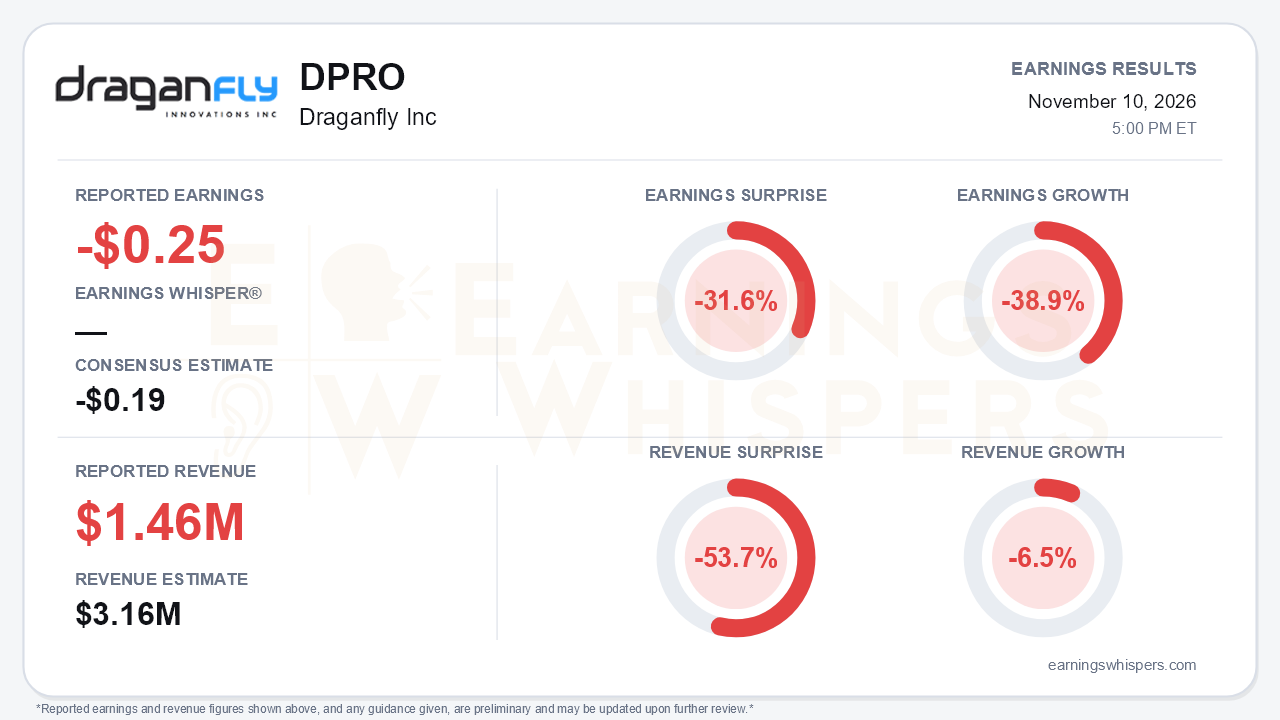
Draganfly (NASDAQ: DPRO) delivered a clear miss in the third quarter, and the bigger problem was timing rather than the size of the loss. On Earnings Whispers' normalized basis, the company lost $0.25 per share against a consensus loss of $0.19, a 31.6% shortfall. Revenue of $1.46 million came in 53.7% below the $3.16 million consensus. Earnings fell 38.9% year over year and revenue declined 6.5%. The company's own release shows revenue of $2,048,425 and a net loss of $0.35 per share. That gap with the normalized figures appears to reflect currency translation from the Canadian-dollar reporting basis, not a different result. On either basis, the central tension is the same. Draganfly is landing the defence credentials it has been chasing, but management now concedes that the revenue those wins should produce is roughly a year further out than it previously expected.
The quality of the quarter deserves scrutiny on two fronts. Revenue stalled after two quarters of growth. The call analysis notes that Q1 rose 49% and Q2 rose 26% year over year, but Q3 fell 23% sequentially from Q2's record level. Product sales of about $1.6 million were essentially flat, and services drove the decline. Reported gross margin fell to 6.3% from 20.0% in Q2 because of a $366,609 non-cash inventory write-down. Excluding it, gross margin was 24.2%. That extends a steady climb from 17.2% in Q4 2025, 19.6% in Q1 and 21.7% in Q2, so the underlying unit economics are improving. Those gains, however, are being earned on a very small revenue base. Operating expenses were $13.6 million, down from $16.1 million in Q2 but up sharply from $5.3 million a year ago. Management cited higher share-based payments, travel, office and personnel costs. The adjusted comprehensive loss widened to roughly $12.6 million, compared with about $3.6 million a year earlier.
The most consequential development on the call was the reset in management's timeline. The CEO now expects revenue to inflect around Q2 or Q3 2027, about a year behind his prior expectation. Back in Q1, he had said the company was comfortable with 2026 consensus and that strong quarters were coming. Management attributed part of the delay to its own choices. It held or switched production lines in anticipation of orders under existing contracts and chose to pursue larger defence programs over some shorter-term revenue. It also flagged external friction in the U.S., including continuing resolutions, midterm-election effects and a defence budget trimmed from $1.5 trillion to $1 trillion. The tone was more guarded than in prior quarters, even as management insisted it has "never been busier."
The pipeline does give bulls something tangible. The Government of Canada selected Draganfly to supply up to 5,000 tactical ISR drones, which management described on the call as a $25 million award with an initial 100-drone delivery. The company has also qualified across all five capability streams of Canada's Defence Drone Initiative Marketplace. It says it is participating in 19 Canadian military RFPs and expects two more announcements before year-end. Management framed the Canadian opportunity as worth hundreds of millions of dollars over the next couple of years. Other developments include:
- an FAA Section 44807 exemption for its Heavy Lift platform;
- a new U.S. defence unit led by retired Brigadier General AJ Pasagian;
- a US$10 million strategic investment, half from Unusual Machines.
Bears have legitimate ammunition here too. The U.S. counter-drone and loitering-munition opportunities promoted last quarter still have no announced contracts.
The balance sheet buys time, but it is not a free option. Cash stood at $128.6 million, well above the $90.2 million at year-end 2025. It has been drifting lower, though, from roughly $147 million in Q1 and $131.9 million in Q2. Shares outstanding rose to 39.1 million from 29.3 million at year-end. A shareholder question on dilution suggests investors are watching the cost of funding a roughly $12 million-plus quarterly loss through a longer pre-revenue runway.
Investor sentiment improved meaningfully into the report, rising from -0.21 to +0.04, though it remains only marginally positive. The stock had opened at $4.28 after the August report, below its 200-day moving average of $5.48, against a backdrop of a sector-wide sell-off in drone names. The Earnings Whispers trend readings are mixed: price and AVWAP trends are negative, while sequential growth registers positive. Sentiment that had just turned neutral-to-positive now has to absorb a guidance-style delay.
The bottom line is that Draganfly's quarter was weak on the headline and weaker on timing. A steep revenue miss and a widening loss came alongside management's admission that the inflection has slipped into mid-2027. The Canadian award, rising adjusted margins and a large cash cushion keep the defence thesis credible. Until contracts convert into consistent revenue, however, investors are being asked to fund a longer wait.
Read our earnings preview for Draganfly Inc: https://www.earningswhispers.com/article/DPRO/22982
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-10 | |
| Nov-06 | |
| Nov-06 | |
| Oct-27 | |
| Oct-13 | |
| Oct-12 | |
| Oct-08 | |
| Oct-08 | |
| Sep-29 | |
| Sep-28 | |
| Sep-28 | |
| Sep-28 | |
| Sep-11 | |
| Sep-10 |
