Seanergy's Stock Has Slumped Since A Record Quarter; Q3 Must Prove The Capesize Upcycle Holds
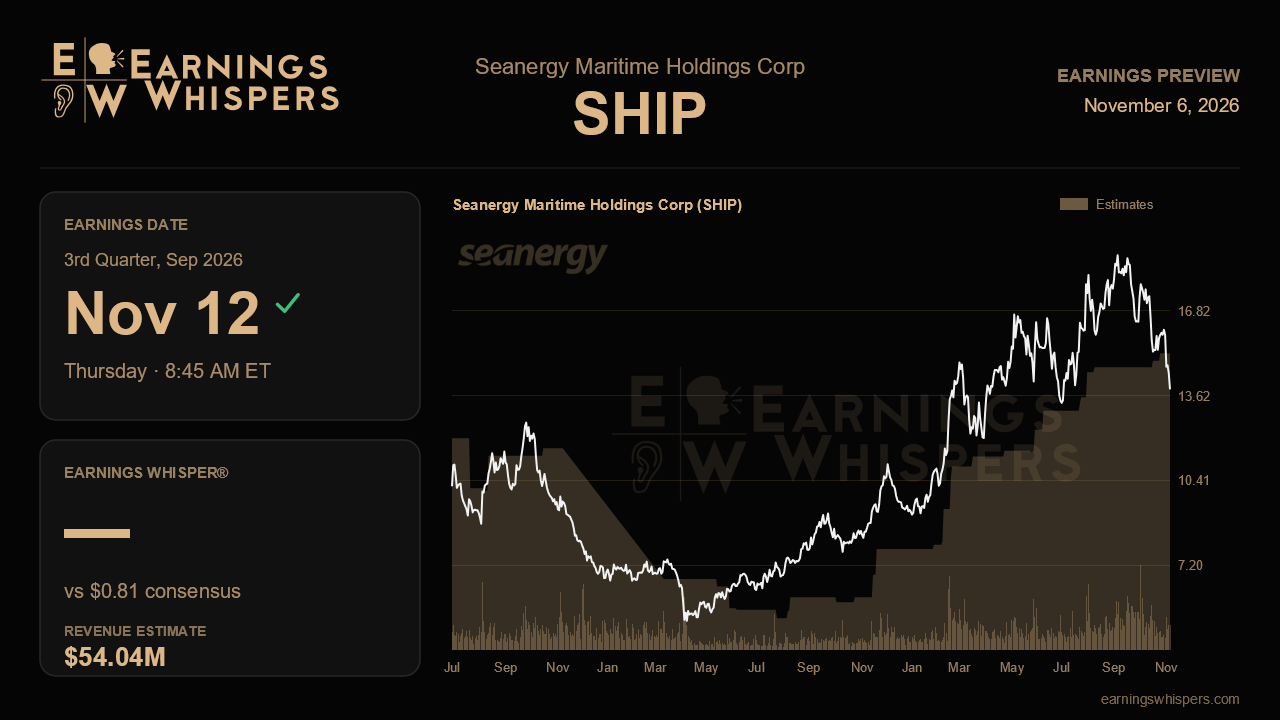
Three months ago Seanergy delivered the most confident quarter in its recent history: record results, a higher full-year EBITDA target, a 75% dividend increase and an eight-vessel fleet renewal program that is now largely financed. The market has not followed management's lead. The shares have fallen 16.5% since that report while the S&P 500 was essentially flat, and at $13.85 they sit just above the $13.79 low of the post-earnings range and below the 200-day moving average of $15.05. The third-quarter report, due before the open on November 12, has to show whether that selloff was a fair reading of a cooling Capesize market or an overreaction to a business whose earnings power is still climbing.
The Street is bracing for a step down from the second quarter but solid growth from a year ago. Consensus calls for EPS of $0.81 on revenue of $54.0 million, up roughly 31% and 15%, respectively, from the $0.62 and $47.0 million posted in the same period last year. Sequentially, though, the picture is softer. Revenue is expected to slip only modestly from $55.7 million, yet EPS is forecast to drop sharply from $1.23. That gap is worth watching. If revenue holds near forecasts, the bottom line depends on how vessel operating costs, drydocking, depreciation and interest on a growing debt stack evolve, and any upside on cost control could translate quickly into a beat.
Management's own framework offers a useful cross-check. The company lifted its 2026 EBITDA outlook to about $138 million at prevailing freight futures, up from roughly $122 million earlier in the year. With first-half adjusted EBITDA of about $69.7 million, that target implies a second half running near $34 million per quarter, well below the $41.5 million record in the second quarter but comfortably above the first quarter's $28.2 million. The Street's revenue estimate looks broadly consistent with that path. Reaffirming or raising the $138 million figure would validate last quarter's narrative; trimming it would confirm the market's skepticism.
Charter coverage is the key operating detail. Seanergy entered the second half with about 55% of its days fixed at roughly $30,800 per day, a level that underpins earnings even if spot rates have eased from their summer spike. Last quarter the fleet earned $32,355 per day, and management acknowledged that its fixed conversions left it slightly behind the index by design. This time the hedge book could work the other way. A realized time charter equivalent near or above $30,000 would show the coverage strategy is doing its job. A number meaningfully lower would suggest the unfixed half of the fleet is absorbing more weakness than expected.
Beyond the quarter itself, the balance sheet story deserves attention. Seanergy tapped a new funding channel with an oversubscribed €100 million unsecured bond at 4.9%, secured about $296.5 million of bank financing covering roughly 90% of remaining capex, and locked in long-term charters for its three 2027 newbuilds with a $23,100 floor plus profit sharing. Updates on whether the euro coupon has been hedged, how the newbuild schedule is progressing and whether the $0.35 dividend is sustained will matter. So will any commentary on Guinea's bauxite export policy, which management flagged as a source of near-term volatility, and on Chinese iron ore demand and the Simandou ramp that featured prominently in its bullish case.
Sentiment has cooled markedly, slipping to 7.9% bullish from 31.1% ahead of the last report, so the bar for a favorable reaction is lower than it was in August. The central question is simple: can Seanergy show that its second-quarter strength was the start of a sustained upcycle rather than a peak? A reaffirmed EBITDA outlook, a steady dividend and realized rates near its fixed coverage would keep the expansion story intact; a guidance cut or a sharp drop in day rates would hand the bears the confirmation they have been pricing in.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-06 | |
| Nov-06 | |
| Sep-25 | |
| Sep-02 | |
| Jul-30 | |
| Jul-30 | |
| Jul-27 | |
| Jul-08 | |
| May-28 | |
| May-28 | |
| May-26 | |
| Apr-14 | |
| Apr-01 | |
| Apr-01 | |
| Mar-12 |
