BioStem's Funding Fix Matters More Than Revenue As Stock Sinks Near $1
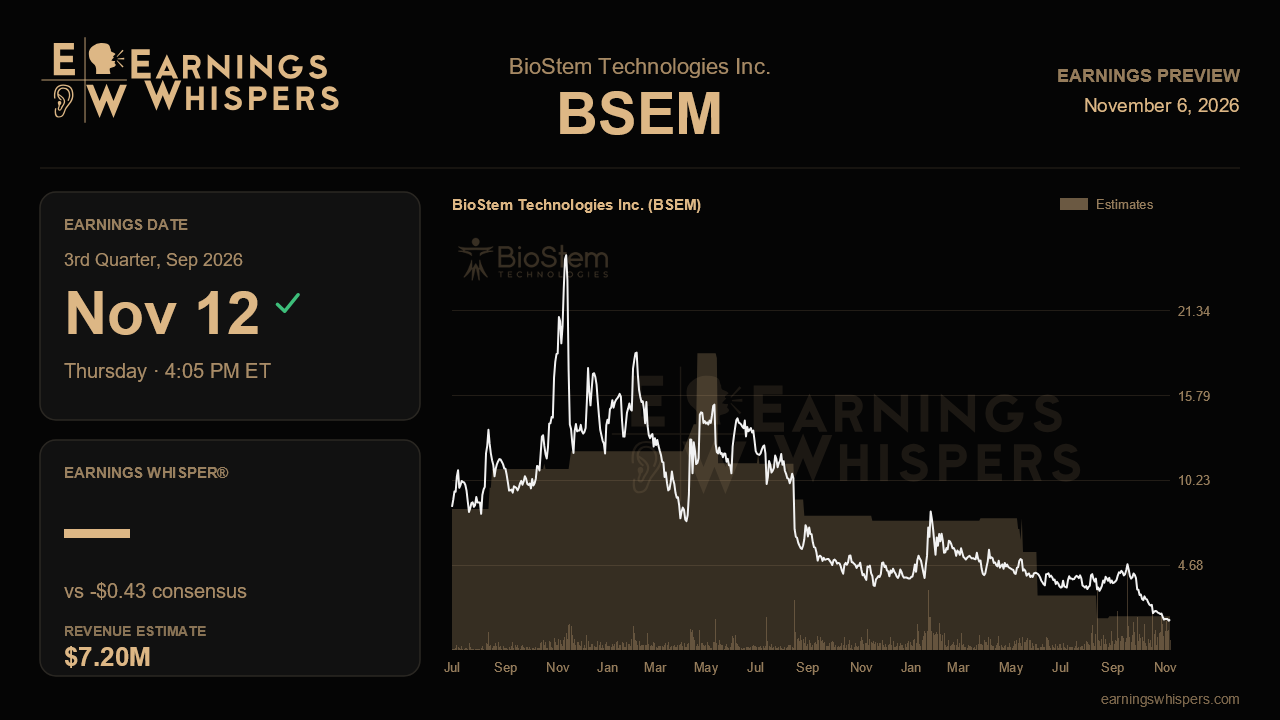
BioStem Technologies heads into its third-quarter report with an odd split. The operating story looked better last quarter than it had in some time, yet the stock has lost more than half its value since then. Shares fell 54.8% while the S&P 500 slipped 5.4%, and at $1.04 the stock sits barely above its post-report low of $1.01 and far below its 200-day moving average of $4.13. Revenue still matters on Wednesday, November 12, after the close. The bigger question is whether the company has solved the balance-sheet problem that hung over an otherwise encouraging quarter.
The Street expects a loss of $0.43 a share on revenue of $7.2 million. That revenue figure is 31.3% below the $10.5 million reported a year ago. The year-ago quarter came before BioStem rebuilt itself around hospital customers, so the comparison says more about the transition than about current demand. A year ago the company earned $0.03 a share. The more useful benchmark is last quarter's $7.9 million in revenue and $0.52 loss. Consensus assumes a modest sequential revenue dip and a slightly narrower loss.
That revenue estimate fits within management's outlook. Last quarter BioStem raised the low end of its fiscal 2026 revenue guidance to $26 million to $29 million. With about $14 million already booked in the first half, the range implies $12 million to $15 million for the second half, or roughly $6 million to $7.5 million a quarter. The $7.2 million consensus sits in the upper half of that pace. Management called the guidance deliberately prudent because the company had only just uplisted. Revenue near or above last quarter's $7.9 million would support that description and point toward the top of the range. A number closer to $6 million would suggest the second quarter's jump was not a new baseline.
The second-quarter growth came from two places. Hospital revenue rose to $6.7 million from $5.4 million, and physician office sales beat expectations at $1.1 million. Management grew the direct sales force to 30 reps and 5 regional directors, up from 18 at the acquisition, and is aiming for 40 by year-end. That hiring is a cost commitment. If the new reps are producing, hospital revenue should keep climbing. If revenue stalls while headcount rises, the losses that recently replaced a long run of positive adjusted EBITDA will look more stubborn. Gross margin is unlikely to help much. It was flat at 61%, and management expects modest pressure through the second half as discounted acquisition inventory is sold. The promised 15 to 20 point margin gain is tied to a technology transfer in the first half of 2027, so this quarter mainly tests whether margins hold up.
The balance sheet is the issue that could outweigh everything else. Cash fell to $7.0 million from $13.7 million in a single quarter, with $5.5 million used in operations. A $10 million milestone payment tied to the acquisition came due in mid-August, and the company had secured only an extension. Management said it was weighing dilutive and non-dilutive financing. Shareholders will want to know how the obligation was settled, how much cash remains, and whether any new capital came on terms that do not deeply dilute a stock now trading near a dollar.
Sentiment has become markedly more bullish than it was before the last report, even as the share price collapsed. That gap suggests some traders see the selloff as overdone. They will need evidence to back that view. The core narrative of hospital-led growth on a newly listed platform holds up only if revenue stays near $7 million or better and the funding gap is clearly closed. Strong sales paired with an unresolved liquidity problem would likely do little to repair confidence.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-06 | |
| Sep-21 | |
| Aug-18 | |
| Aug-13 | |
| Aug-11 | |
| Jun-09 |
