BioStem Beats On Revenue And Lifts Its Guidance Floor, But A $1 Million Cash Balance Makes Survival The Real Story
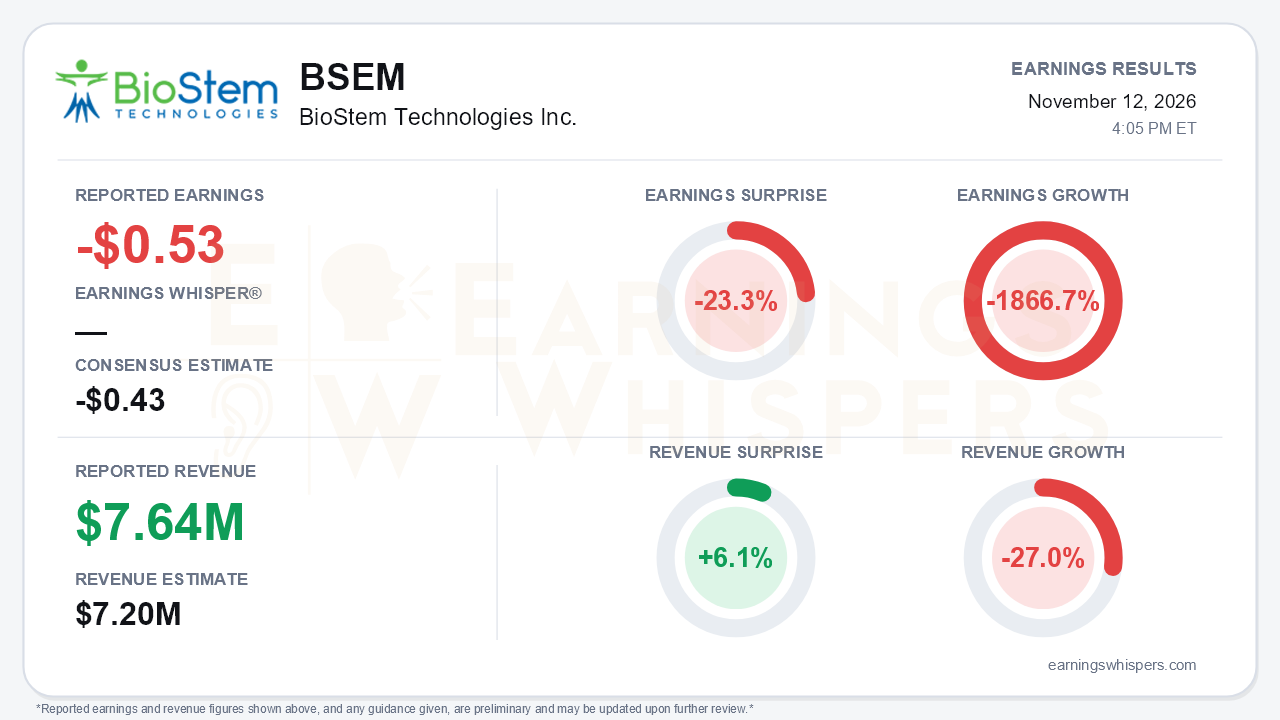
BioStem Technologies reported a third-quarter loss of $0.53 per share, missing the consensus estimate of a $0.43 loss by 23.3%. Revenue of $7.64 million beat the $7.2 million consensus by 6.1% but fell 27.0% from a year ago. Earnings fell 1866.7% year over year, a swing from a small profit in the year-ago quarter (diluted EPS of $0.03) to a deep loss. Investors should note that the company's GAAP net loss was $11.4 million, or $0.64 per share, wider than the normalized $0.53 figure. Either way, the loss widened from $0.52 per share in the second quarter. The revenue beat and a modestly higher guidance floor are real, but they are secondary. The central development is that BioStem ended September with $1.0 million in cash after burning $8.8 million in operations during the quarter. The narrative has shifted from building a commercial platform to financing the company's survival.
The quality of the quarter deserves scrutiny. Total revenue slipped to $7.6 million from $7.9 million sequentially. Hospital revenue edged up to $6.8 million from $6.7 million, while physician office revenue kept eroding, falling to $810,000 from $1.1 million. Gross margin compressed to 56% from 61% as discounted BioTissue inventory ran out, a sharp contrast with the 88.5% margin a year ago. Operating expenses rose to $14.1 million from $13.2 million, even though management had guided to roughly flat spending excluding uplisting costs. The adjusted EBITDA loss widened to $6.4 million from $4.6 million. Accounts payable has more than doubled since year-end to $10.5 million, and a $10 million consideration payable now sits in current liabilities. That leaves total current liabilities of $22.2 million against $16.1 million of current assets.
The operating story beneath the headline is genuinely mixed rather than broken:
- **Hospital growth:** hospital revenue has grown for three straight quarters, up from $5.4 million in the first quarter.
- **Deeper accounts:** customers buying two or more product lines rose 14% sequentially, and three-plus-line accounts rose more than 40%. Multi-product customers now generate more than half of revenue.
- **Better months:** management called July and September the best months since the acquisition.
- **Distribution:** VENDAJE won its first GPO coverage, with the two largest agreements.
- **Systems control:** the CRM and ERP systems are live, giving the company control over invoicing and collections.
The forward framework, however, was cut in several places. Expected post-transfer gross margin uplift is now described as 10-15 points, gradual through 2027. Last quarter it was 15-20 points into the 70s, and at the end of fiscal 2025 the target was a return to 80%-plus. The push toward 40-plus sales reps has given way to moderated hiring and a narrower territory focus. The revised $28-$29 million full-year guide also implies fourth-quarter revenue of roughly $6.4-$7.4 million, flat to down from the third quarter.
The catalysts are now mostly about liquidity:
- **New capital:** a $3 million private placement with up to $5.6 million in additional warrant proceeds, plus $1 million from CEO and COO option exercises.
- **Equity facility:** a $40 million committed facility with Roth that generally cannot be tapped until April 2027 and carries a $1 minimum share price condition.
- **Cost cuts:** a plan to remove $10-12 million in annualized cash operating expenses, with the full benefit starting in the first quarter of 2027.
- **Other sources:** restructuring talks with BioTissue over the clearance payment, plus a possible receivables-based credit line, a land sale and an expected tax refund of about $1 million.
- **Clinical data:** VLU study top-line results are due in early December and are the main clinical catalyst.
Bears have legitimate ammunition here. The roughly $10 million clearance payment remains unpaid even after a $1 million extension fee. That has delayed the Catalyze 510(k) launch that was guided for later this year. The release explicitly cites going-concern, Nasdaq listing-compliance and dilution risks. The Chief Accounting Officer also retires in December.
The market setup is more complicated than the revenue beat implies. Shares opened at $2.30 after the prior report and fell 36.1% to $1.47 by the eve of this release. That leaves them 63.6% below the 200-day moving average and 73.0% below the September 18 high of $5.44. The stock set a 52-week low of $1.00 on November 10 and rebounded 47% into the print. The proximity to $1 matters fundamentally, not just technically, because the equity facility depends on that threshold. Investor sentiment nonetheless jumped from 0.35 to 0.87, a substantial move toward optimism that sits awkwardly against the price action. The Earnings Whispers trend signals remain mostly negative, with price, sequential growth and AVWAP all deteriorating.
The bottom line is that BioStem delivered a revenue beat, steady hospital traction and a firmer guidance floor, yet the quarter changed the investment debate from growth to solvency. With $1 million in cash, an unpaid $10 million obligation and margin targets repeatedly scaled back, the next few months hinge on financing, the BioTissue restructuring and December's VLU data rather than on incremental commercial wins. Sharply improved sentiment suggests some investors see a bottom forming. The balance sheet, however, leaves little margin for error and points to meaningful dilution ahead.
Read our earnings preview for BioStem Technologies Inc.: https://www.earningswhispers.com/article/BSEM/23007
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-06 | |
| Sep-21 | |
| Aug-18 | |
| Aug-13 | |
| Aug-11 | |
| Jun-09 |
