DLocal's Raised Outlook Faces Its Operating-Leverage Test As Stock Slips Below Trend
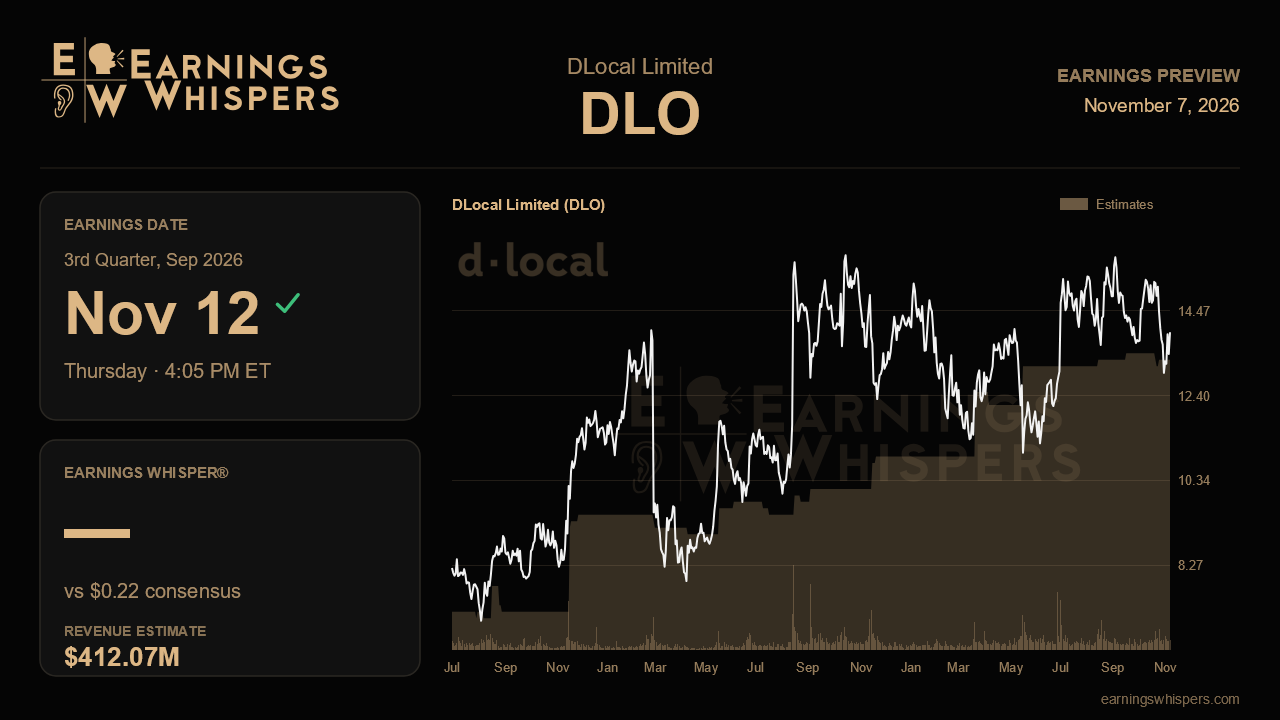
DLocal enters its third-quarter report with an awkward contrast. Last quarter's call was the most confident in at least a year, with payment volume growth hitting a four-year high, two guidance raises and the first real sign that operating costs were finally lagging revenue. The stock has gone the other way. It is down about 12% since that report, roughly double the S&P 500's decline over the same stretch. The November 12 release, due after the close, has to show that the acceleration was the start of a new phase rather than a single spectacular quarter.
Wall Street is looking for earnings of $0.22 a share on revenue of $412.1 million. That would mean revenue growth of nearly 46% and EPS growth of about 29% from a year earlier. Sequentially the step-up is modest, only about 3% on the top line from $399.7 million, while EPS would rise from $0.18. That gap matters. Analysts are not counting on another big revenue surprise. They are counting on profit growing faster than revenue, which is exactly the operating-leverage story management laid out.
The second-quarter numbers explain both the excitement and the caution. Total payment volume reached $17.7 billion, up 92%, after 73% in the first quarter and 70% in the fourth. Management lifted full-year volume growth guidance to 60% to 70% and gross profit growth guidance to 25% to 30%. Operating profit, however, was held at 27.5% to 32.5% growth. Executives blamed a one-time prior-year tax item and currency moves that went against them, and said they would otherwise have raised it. This quarter is the first clean look at whether that explanation holds. Operating profit reached 50% of gross profit last quarter, and management said elevated first-half spending, including annualized hiring from 2025, World Cup marketing and senior hires, would fade in the back half. If that ratio holds or improves, the case for raising the operating profit guide gets much stronger. If it slips, the holdback starts to look less like caution and more like a warning.
Take rate is the other swing factor. Volume has been outrunning gross profit by a wide margin, and net take rate fell to about 72 basis points as local-to-local flows climbed to 61% of volume. Management offered two reasons this should stabilize. The ramp of its largest ride-hailing merchant, whose tiered pricing had been diluting rates, is now complete. And excluding that merchant, take rate would have been roughly flat. A steadier take rate would confirm the drag was temporary. Further compression would raise doubts about how much of the volume growth reaches the bottom line. Mexico, where gross profit slipped sequentially on cost issues, and Africa and Asia, which also declined from the prior quarter, are the places to check. Brazil and Argentina, both at record gross profit, need to stay strong.
There is also the matter of comparisons. Management repeatedly warned that year-over-year comps get harder in the second half and into 2027, and flagged OECD Pillar 2 as a pressure on the tax rate starting next year. Investors should watch whether early 2027 commentary leans on newer drivers, such as the dMORE merchant-of-record product and buy now, pay later, now live in eight markets, to offset tougher comparisons.
Sentiment has cooled, moving from essentially neutral before the last report to mildly bearish now. At $13.42, the stock sits just below its 200-day average of $13.54 and near the bottom of its post-earnings range of $12.87 to $16.15. That positioning suggests a lower bar than the operating momentum would imply. In the end, the report comes down to one question. If the second-half cost relief arrives and operating profit grows faster than gross profit, the confident tone from last quarter will look justified. If it does not, the market's skepticism will look earned.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-07 | |
| Oct-14 | |
| Sep-14 | |
| Aug-28 | |
| Aug-18 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Jul-28 | |
| Jun-26 | |
| Jun-05 | |
| May-15 | |
| May-15 | |
| May-14 | |
| May-14 |
