DLocal's Operating Leverage Finally Shows Up, But A Revenue Miss, Slowing TPV And New FX Headwinds Cap The Upside
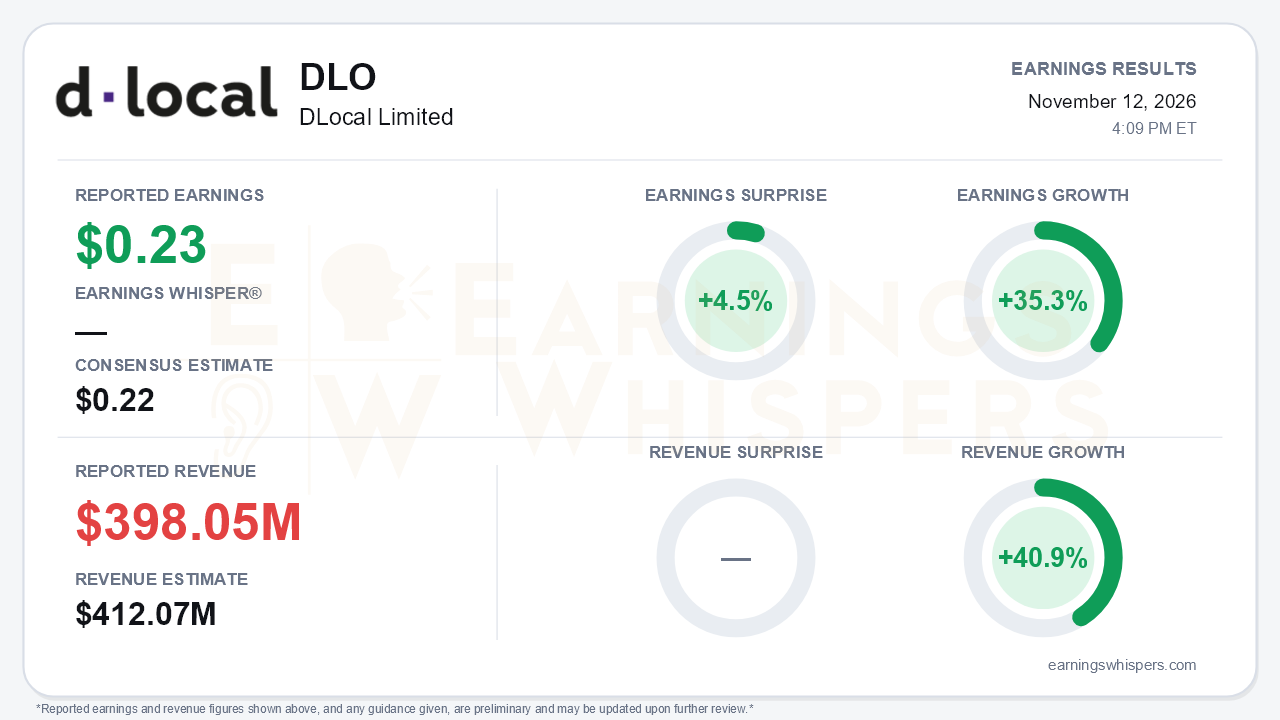
dLocal delivered the operating-leverage quarter management has promised since late 2025, but it arrived with a top-line problem. The company earned $0.23 per share in the third quarter, beating the $0.22 consensus by 4.5%. Earnings grew 35.3% year over year. Revenue rose 40.9% to $398.05 million, yet missed the $412.07 million consensus by 3.4%. Revenue was essentially flat sequentially from $399.7 million in the second quarter. That is the central tension: profitability inflected sharply just as volume and revenue growth decelerated, and management declined to raise full-year guidance despite the beat.
The profit improvement came mostly from expenses rather than from gross profit. Operating expenses fell 11% sequentially to $55.9 million, helped by lower third-party spend, lower headcount and automation. The call highlighted the first sequential payroll decline of the year. Operating profit rose 37% year over year and 19% sequentially to $76.2 million. Operating profit as a share of gross profit jumped to 58%, the highest since 2023, from 50% in the second quarter. This was the first quarter this year in which operating profit grew faster than gross profit. Year-to-date operating profit is up only 23%, so the third quarter marks a clear acceleration in profit growth.
The quality of that margin deserves scrutiny. Record gross profit of $132 million was helped by a one-off cost recovery in Nigeria, FX hedge gains and lower advancement costs in Argentina. The call also cited timing benefits, including back-half-weighted marketing and benign credit losses. The CFO explicitly cautioned against extrapolating the 58% ratio. Net income also benefited from higher finance income on larger cash balances. Record adjusted free cash flow of $99.1 million partly reflected a reversal of first-quarter working-capital drag, and management expects that benefit to partly normalize.
Beneath the headline, the growth trajectory is cooling:
- **TPV:** grew 77% to $18.3 billion, down from 92% in the second quarter and up just 4% sequentially.
- **Gross profit:** growth eased to 28%, versus 29% in the second quarter and 40% in the first.
- **Mix:** revenue was pressured by a higher share of lower-yielding local-to-local and pay-out flows, plus post-Hot Sale softness in Argentina. Excluding Argentina, revenue rose only about 1% sequentially.
- **Mexico and Brazil:** Mexico gross profit stepped down again on processing-cost catch-ups and large merchants reaching the lowest pricing tiers. Brazil saw a shift toward Pix and boleto.
There is a more constructive read on unit economics. Gross profit as a percentage of TPV held flat sequentially at 0.72%, versus 0.99% a year ago, suggesting take-rate compression is slowing rather than ending. Net revenue retention of 140% shows existing merchants are still expanding.
Guidance is where the setup turns more cautious. Targets raised in the second quarter (TPV growth of 60-70%, gross profit growth of 25-30%, operating profit growth of 27.5-32.5%) were only reiterated. The call indicated TPV is tracking toward the upper end of its range. However, the release said operating profit is being hurt by unanticipated FX headwinds in Brazil, Mexico and Argentina and by softer high-take-rate markets in Africa and Asia. Management sized the fourth-quarter FX swing at roughly 6 percentage points. Brazil's election-related advertising volume is also expected to normalize.
Other items weigh on the outlook as well. The $150 million credit facility drawn in August adds interest cost. Pillar 2 tax pressure looms from 2027.
Offsetting those concerns are tangible longer-dated catalysts:
- **Asia:** a newly hired APAC CEO, a major music-streaming client and talks with an AI lab. Management said the region could reach a mid-to-high single-digit share of the top line in 2027 if successful.
- **Licensing:** new US money transmitter licenses and Canadian AML registration.
- **Digital assets:** a stablecoin vertical now producing real growth.
- **Capital returns:** about $120 million of buybacks completed under the $300 million authorization.
The market entered the report skeptical. Investor sentiment slipped from essentially neutral to modestly negative heading into the print. Shares, at $13.96, were down 8.6% since the open after the August report and 13.6% below the September 3 52-week high of $16.15. They sat only 3.1% above the 200-day moving average and 8.5% above the late-October low. Sequential-growth and momentum trend readings are positive, while AVWAP remains negative, consistent with a stock that has given back its post-August rally despite improving profitability.
The bottom line is that dLocal proved it can convert volume into operating profit and cash. However, the quarter's best metrics were partly flattered by one-offs and timing, while revenue missed, TPV growth decelerated and a fresh fourth-quarter FX headwind kept guidance on hold. Bulls get validation of the leverage thesis; bears retain legitimate ammunition on top-line durability and margin sustainability.
Read our earnings preview for DLocal Limited: https://www.earningswhispers.com/article/DLO/23013
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 4 hours | |
| 5 hours | |
| 5 hours | |
| Nov-10 | |
| Nov-07 | |
| Oct-14 | |
| Sep-14 | |
| Aug-28 | |
| Aug-18 | |
| Aug-14 | |
| Aug-13 | |
| Aug-13 | |
| Jul-28 | |
| Jun-26 |
