Inuvo's Shrinking Search Business Puts IntentKey Growth And Cash Runway To The Test
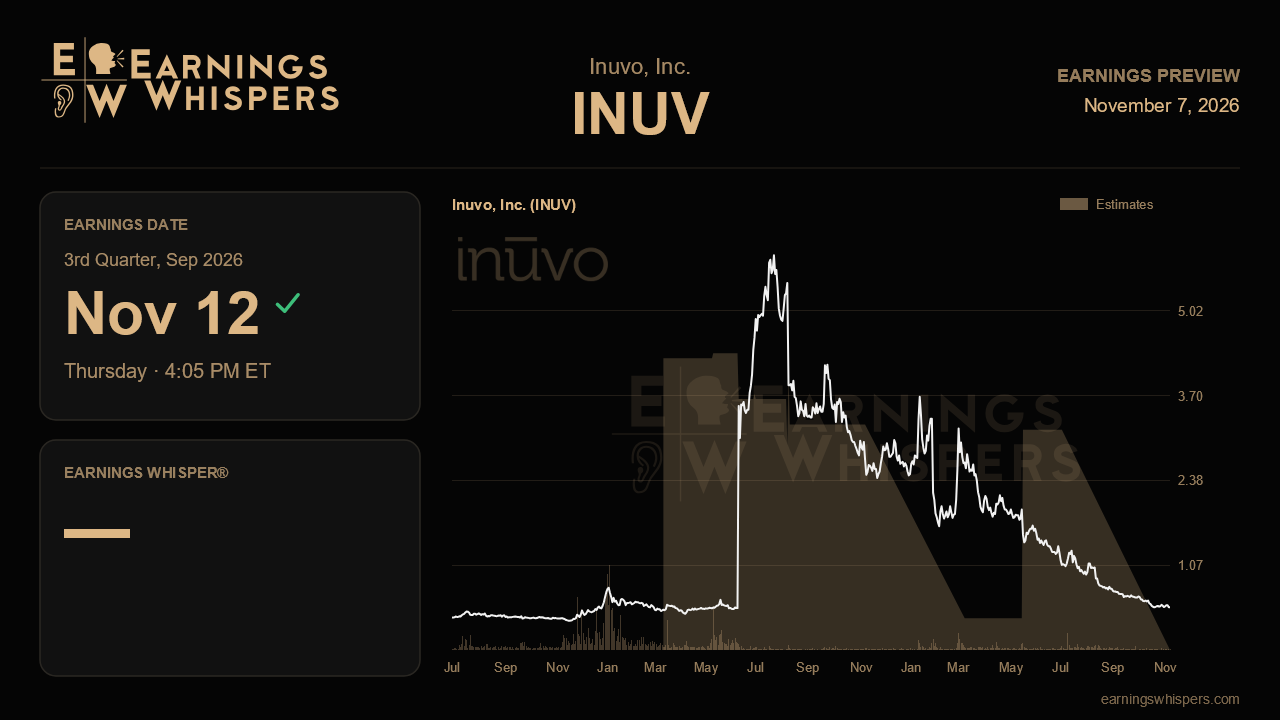
Inuvo heads into its third-quarter report on November 12 asking investors to look past a collapsing top line and focus on a much smaller, higher-quality business underneath. The company is deliberately letting its legacy search operation fade while betting its future on IntentKey and its audience-modeling franchise. The problem is that the old business is shrinking far faster than the new one is growing, and the stock has been punished accordingly. This report needs to show that the transition has a floor, and that the balance sheet can carry the company until it gets there.
There is no meaningful published consensus to anchor the quarter, and management has not issued formal guidance, so the bar is set by the trajectory the company described last time. Total revenue fell from $22.6 million in the year-ago quarter to $7.5 million in the second quarter, with legacy search down roughly 80% year over year. Unless something unexpected happens, a steep year-over-year revenue decline is a given. The more useful comparison is sequential. Revenue slid only modestly from $7.9 million in the first quarter to $7.5 million in the second, and a stable or rising figure this time would suggest the worst of the search runoff is in the rear-view mirror. The year-ago loss of $0.12 per share is a low hurdle on paper, but last quarter's $0.27 loss was inflated by a debt extinguishment charge and severance, so a cleaner result without those items is the reasonable expectation.
The heart of the story is audience modeling, which accelerated from 13% growth in the first quarter to 19% in the second, reaching about $3.6 million. Management reaffirmed year-over-year growth for the full year on the strength of its sales pipeline, but that pace still trails the strong double-digit cadence it promised a few quarters ago. Validation would look like growth holding near or above 20%, evidence that the five new brand-direct relationships added last quarter are spending, and an update on whether the two Fortune 500 pilots have progressed toward paid programs. Investors also deserve clarity on the newer catalysts: the MCP Server designed to plug IntentKey into AI assistants, the push into recruitment and healthcare open-enrollment marketing, and the long-delayed government contract that has yet to produce revenue. A quarter of encouraging anecdotes without revenue attached would weaken the narrative.
Margins are the other swing factor. Gross margin has fallen from 88% a year ago to roughly 44% as high-margin search disappeared. As audience modeling becomes a larger share of the mix, margin should begin to stabilize, and headcount cuts to 51 employees should start showing up in operating expenses. Management has already scrapped its old $100 million revenue and breakeven framework, saying IntentKey alone could reach cash neutrality in the mid-$20 million revenue range with a 2027 aspiration. Any concrete path toward that goal would carry weight, especially with new President and CFO Derek Ciccone now in the seat and likely to put his own stamp on the outlook.
Liquidity may matter most of all. Unrestricted cash stood at just $886,000 at the end of June, alongside $6.2 million in restricted cash whose release depends on note redemption milestones. The $13 million financing and the $450,000 sale of the Ranger QA tool helped, but shareholders will want to see how much of that cushion survived the quarter.
The market has delivered its verdict so far. Shares are down about 56% since the last report, badly lagging the S&P 500, and at $0.41 the stock sits at the bottom of its post-earnings range and far below its 200-day average of $1.40. Oddly, sentiment has turned much less bearish than it was before the prior report, suggesting some investors believe the bad news is already priced in. Whether that holds comes down to one question: can audience-modeling growth and cost discipline outrun the search decline and the cash burn before the runway gets any shorter?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-07 | |
| Nov-05 | |
| Nov-02 | |
| Oct-14 | |
| Sep-10 | |
| Aug-26 | |
| Aug-21 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-06 | |
| Aug-04 | |
| Jul-08 | |
| Jul-01 |
