Inuvo's IntentKey Growth Story Breaks As Audience Modeling Reverses And Liquidity Tightens To $1 Million
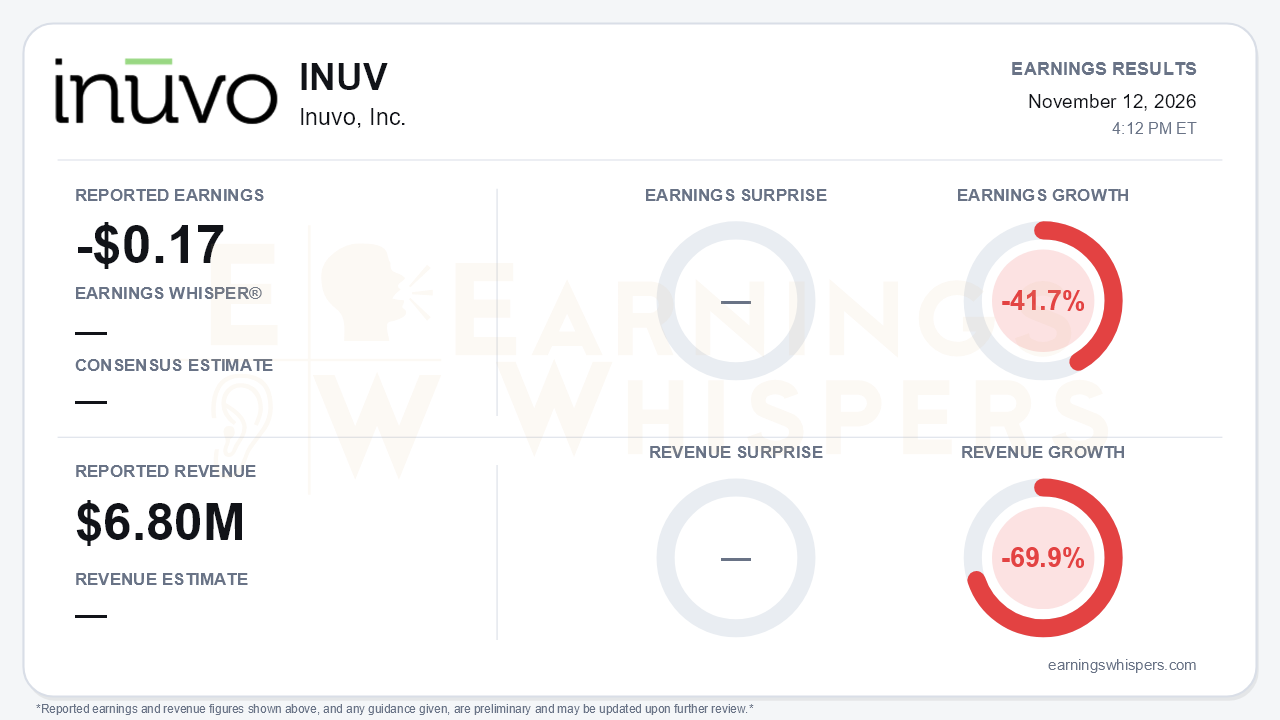
Inuvo's third quarter undercut the premise that IntentKey could carry the company through the collapse of Legacy Search. Earnings Whispers' normalized loss was $0.17 per share, a 41.7% deterioration from a year ago, on revenue of $6.8 million, down 69.9%. No consensus estimate was available, so there is no surprise to measure. The more telling comparison is against management's own narrative. Audience Modeling, the business meant to be the growth engine, fell 24% year over year after rising 13% in the first quarter and 19% in the second. The company had promised "strong double-digit growth each quarter" as recently as early 2026. That reversal is the central development of the quarter.
The GAAP picture is worse than the normalized figure. Inuvo reported a GAAP net loss of $5.0 million, or $0.28 per share, which included a $2.4 million non-cash impairment of Legacy Search intangible and long-lived assets. Excluding that charge does not rescue the quarter. Adjusted EBITDA loss widened to $1.6 million from $0.7 million a year earlier, and the net loss widened sequentially from $4.0 million in the second quarter. Revenue slid for a third straight quarter, from $7.9 million to $7.5 million to $6.8 million. Gross margin held at 44%, essentially flat with the prior two quarters but far below last year's 73%. That gap reflects the mix shift away from Legacy Search, which booked most of its costs as traffic acquisition rather than cost of revenue.
On the call, management attributed the Audience Modeling decline to a tariff-driven pullback by its largest client and slower pipeline conversion. It linked the slower conversion to an early-summer overhaul of the sales team, with sales cycles running four to six months. Implied Audience Modeling revenue fell roughly 18% sequentially, to about $2.95 million from about $3.6 million. That client concentration is now an explicit vulnerability rather than a footnote. Legacy Search also lost its recovery story. The second-quarter expectation of sequential revenue and margin improvement was replaced with a flat fourth-quarter outlook and the impairment. The business is now being managed for cash, covering its direct operating costs. Management's tone shifted from "significant room to run" to "cautiously optimistic" and "we've got to make it through the end of the year." Management framed 2027 as a breakout year only if conditions are met. Notably, the large government workforce contract, once described as "weeks away," went unmentioned.
The forward case rests on a new sequential guide: management expects fourth-quarter Audience Modeling revenue to rise meaningfully from the third quarter. It cited in-flight campaigns, booked revenue, and the return of the largest client's spend. Several other developments support that guide:
- a White Label Partner Program for agencies;
- completed Claude MCP integration testing, with a connectors-directory listing being prepared;
- neighborhood-level CTV targeting that served more than 20 million impressions in October;
- new logos including Sony, Fairmont, Extended Stay and Regal.
Management also positions Apple's iOS identity cutoff as a tailwind for its ID-free model. On costs, headcount is down to 47 from roughly 80, compensation fell 35%, and severance payments end at year-end.
The binding constraint is liquidity, and bears have legitimate ammunition here. Unrestricted cash was just $1.0 million at quarter-end, alongside $6.2 million in restricted cash. That position follows a $3.0 million registered direct offering and comes with roughly $9.9 million in notes payable now on the balance sheet. The company states it will need to raise additional capital. Its forward-looking disclosures reference substantial doubt about its ability to continue as a going concern. Management gave no runway date. The $450,000 Ranger sale helps at the margin but does not change the math, and further dilution looks difficult to avoid.
The market had largely priced in distress before the report. Shares fell 58% from the $0.94 open after the August release to $0.39. They sit about 71% below the 200-day moving average of $1.36 and just above a 52-week low of $0.38 set two days before the report. Investor sentiment improved meaningfully, from -0.46 to -0.15, but remains negative. That shift reads more like capitulation easing than renewed conviction. The Earnings Whispers trend signals remain mostly negative, with sequential growth and momentum still deteriorating.
The bottom line is that Inuvo's quarter replaced a growth narrative with a survival narrative. A credible fourth-quarter rebound in Audience Modeling, driven by a returning client and a maturing pipeline, is the only near-term proof point that matters. That rebound will have to arrive alongside a financing that likely dilutes existing holders. Until conversions show up in reported revenue, the product momentum is promising but secondary to the balance sheet.
Read our earnings preview for Inuvo, Inc.: https://www.earningswhispers.com/article/INUV/23021
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-09 | |
| Nov-07 | |
| Nov-05 | |
| Nov-02 | |
| Oct-14 | |
| Sep-10 | |
| Aug-26 | |
| Aug-21 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-06 | |
| Aug-04 |
