GrabAGun's Margin Gains Face A Test As Revenue Growth Is Expected To Nearly Stall
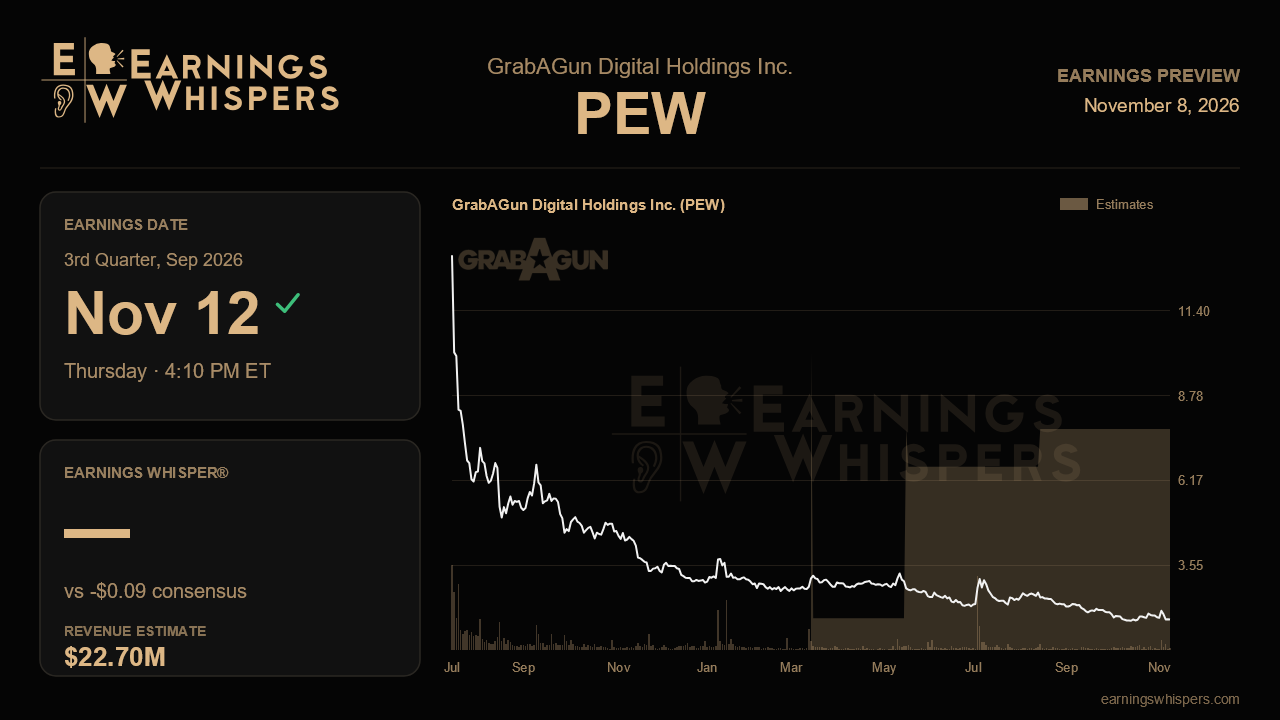
GrabAGun heads into its third-quarter report with a split personality. Last quarter, the online firearms retailer showed its best gross margin in recent memory and a logistics platform that keeps adding manufacturers. The stock still has fallen more than a quarter since then. The question now is whether improving unit economics can matter while top-line growth is expected to slow to a crawl.
Wall Street is looking for a loss of 9 cents a share on revenue of about $22.7 million. That revenue figure would be up only about 1.9% from the $22.3 million reported a year ago. Growth was 9.4% last quarter and 11.1% the quarter before, so consensus implies a sharp deceleration rather than a simple seasonal dip. On earnings, the projected loss is narrower than the 12-cent deficit of a year earlier but wider than the 6-cent loss posted last quarter. The company does not issue formal guidance, which leaves the Street's numbers as the main yardstick. Analysts appear to be modeling continued investment spending against a demand backdrop that has not yet turned.
The margin story is the core of the bull case, and this report will show whether it holds. Gross margin climbed to 13.5% last quarter from 10.7% in the first quarter and 11% in the year-ago third quarter. Management credited a richer firearm mix, AI-driven pricing and early contributions from Pew Logistics. Holding gross margin in the 13% range on flat revenue would suggest these drivers are structural. A slide back toward 11% would suggest last quarter benefited from favorable mix that may not repeat. Pew Logistics deserves close scrutiny as well. Cumulative gross merchandise value reached $1.9 million through June, up from $1.3 million three months earlier, and Backwoods Suppressors joined as a third manufacturer. That is still small relative to total sales. Because management describes the business as carrying roughly 70% margins, a visible step-up in GMV, or additional manufacturer signings, would do more for the earnings trajectory than a few points of retail growth.
Operating expenses are the other swing factor. Management said the second quarter was the last with difficult pre-public-company comparisons. That makes this the first clean look at whether G&A is leveling off. Adjusted EBITDA losses narrowed slightly to $1.7 million last quarter from $2.0 million. Further improvement would support the idea that losses reflect deliberate investment rather than a cost base outgrowing the business. Cash fell to $97.5 million, which management largely attributed to accounts payable timing, and it pointed to a rebound. A recovery in that balance would reinforce the explanation. Another decline would invite harder questions. This is also likely the first report under new CFO Jonathan Terry, formerly of Yeti, so any change in disclosure style or financial framing will be noticed. Ammunition demand, which management called soft across the industry, remains a drag worth monitoring.
Sentiment has improved even as the stock has not. Bearishness eased to about 31% from roughly 60% heading into the last report. Over the same period, shares fell 26.3%, trailing the S&P 500 by nearly 21 percentage points. At $1.88, the stock sits well below its 200-day moving average of $2.60 and near the bottom of its post-earnings range of $1.79 to $2.68. That entire range sits below the prior quarter's trading band, so the market has clearly discounted the margin progress.
The central issue is whether GrabAGun can show that its profitability levers work without help from revenue growth. Steady margins, rising Pew Logistics volume and leveling expenses would keep the improving narrative intact despite a near-flat top line. If margins slip while sales stall, the recent selloff will start to look less like an overreaction and more like an early read on a stalled story.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-08 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-05 | |
| Sep-09 | |
| Sep-08 | |
| Aug-18 | |
| Aug-18 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 |
