GrabAGun Misses On Both Lines As Record Gross Margin Masks Falling Volumes And A Widening Adjusted EBITDA Loss
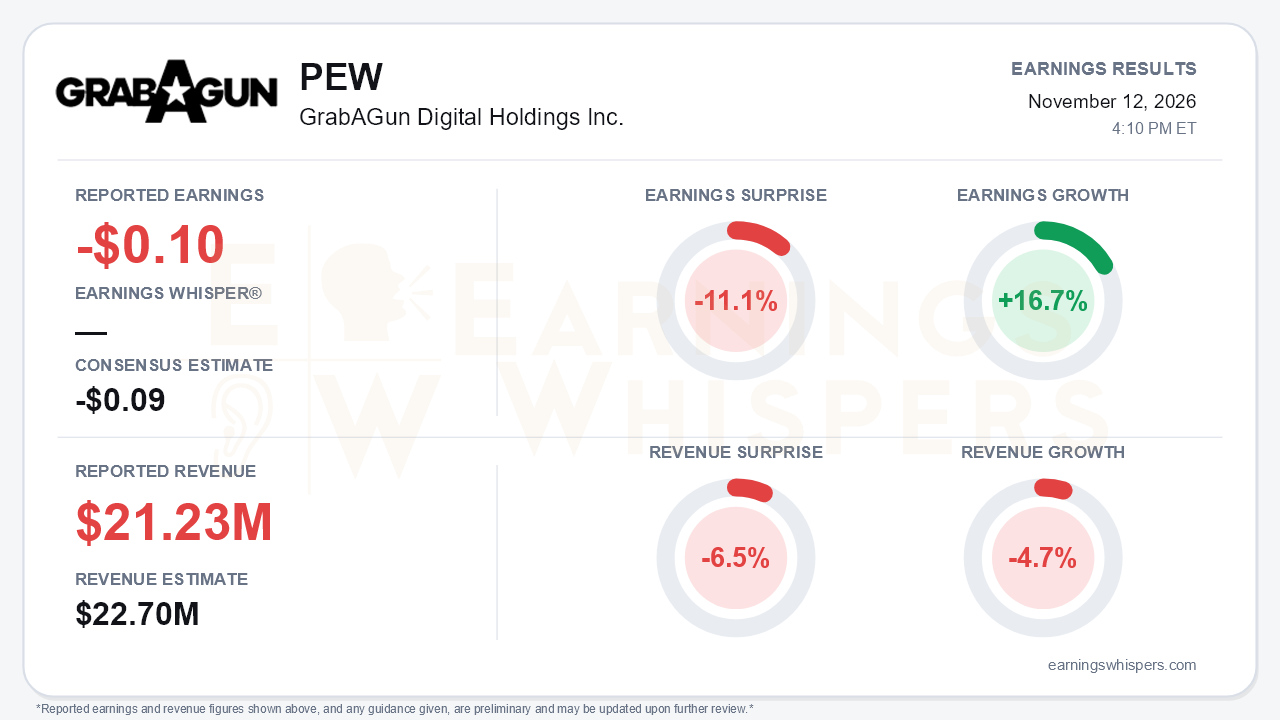
GrabAGun Digital Holdings (NYSE: PEW) missed on both lines in the third quarter. It posted a loss of $0.10 per share against a consensus estimate of -$0.09, an 11.1% shortfall. Revenue of $21.23 million fell 4.7% year over year and came in 6.5% below the $22.7 million consensus. The per-share loss did narrow from $0.14 a year earlier, which Earnings Whispers counts as 16.7% earnings growth. That improvement came alongside a sharp reversal in the top line. Revenue had grown 11.1% in Q1 and 9.4% in Q2, so this was a clear deceleration into contraction. The quarter's central tension is that management is now selling a margin-and-strategy story just as the core retail engine has stalled.
The margin story is real. Gross margin reached 14.4%, up from 9.6% a year ago, 10.7% in Q1 and 13.5% in Q2. Gross profit rose 44% to $3.1 million. The source of that gain deserves scrutiny, though. Firearm average selling prices rose 10% and non-firearm ASPs rose 20%, while firearm units fell 14% and non-firearm units dropped 27%. GrabAGun is earning more on each sale but making materially fewer sales, so the improvement owes more to pricing and sourcing than to demand.
The narrower GAAP loss also flatters the operating picture. General and administrative expense was essentially flat at $6.6 million. However, stock-based compensation fell from $3.2 million to $0.6 million, which means cash-type overhead rose meaningfully. Adjusted EBITDA, which strips out stock comp, shows the deterioration plainly: the loss widened to $2.1 million from $0.9 million a year ago and from $1.7 million in Q2. Better gross profit was not enough to absorb a heavier public-company cost structure. Lower interest income on a shrinking cash pile also removed some cushion below the operating line.
The call reinforced the shift in tone. Management attributed the volume decline to a difficult comparison against last year's IPO-driven demand and a regulatory pull-forward after Q2. Those explanations are plausible, but management declined to comment on Q4 demand. That contrasts with the explicit mid-to-high single-digit growth outlook it offered a year ago. The prior framing of outgrowing industry NICS checks was dropped in favor of an "execution, not announcements" message. Customer lifetime value of $825 was up 4% year over year but sits below the $855 cited a year ago, even as new users grew 26%. The share repurchase authorization lapsed in August with no Q3 buybacks.
The forward story now rests on three catalysts:
- **Camfour.** The roughly $34 million all-cash acquisition closed in late October without dilution. Camfour generated about $77 million of 2025 revenue (part of it intercompany), which could more than double the revenue base and adds an independent-dealer wholesale channel. It also brings lower-margin wholesale mix, integration risk, and no disclosed financials until an 8-K/A in January.
- **PEW Logistics.** The unit is small but scaling. Service revenue was about $0.3 million, up 28% sequentially, and cumulative GMV climbed from $1.9 million to $3.1 million. SAR USA became the fourth manufacturer client, and the KelTec relationship expanded into full direct-to-consumer site operations.
- **Suppressor demand.** The ATF's October decision to stop enforcing NFA registration for suppressors is a potential demand tailwind, with NFA checks up 129% year over year in September.
A new CFO from Yeti, a new CTO and a formal capital allocation framework round out the reset.
The market had already priced in plenty of skepticism. Shares closed at $1.81 ahead of the report, down 29% from the $2.55 open after the August release. That is roughly 30% below the 200-day moving average of $2.58 and just above the 52-week low of $1.79 set in mid-October. The stock trades below the $3.25 per share of cash held at quarter end. Even after the Camfour payment, the remaining cash, roughly $62 million or about $2.10 per share, appears to exceed the share price, though cash continues to erode. Nine-month operating cash burn was $7.3 million, and capital spending was $5.2 million. Investor sentiment remains negative but improved notably, rising from -0.60 to -0.30 since the last report. Expectations were washed out heading into the print. Earnings Whispers trend readings lean negative, with AVWAP weak and momentum neutral.
The bottom line is that GrabAGun delivered a genuinely better gross margin and a strategically meaningful acquisition. It paired them with a double miss, shrinking unit volumes, a wider adjusted EBITDA loss and no near-term outlook. Bears have legitimate ammunition in the demand data and cash trajectory. The deep discount to cash and improving sentiment give the story a floor of interest. The next leg depends on whether Camfour's January disclosures and Q4 volumes show the business can grow again, not just earn more per sale.
Read our earnings preview for GrabAGun Digital Holdings Inc.: https://www.earningswhispers.com/article/PEW/23027
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-08 | |
| Oct-27 | |
| Oct-22 | |
| Oct-20 | |
| Oct-05 | |
| Sep-09 | |
| Sep-08 | |
| Aug-18 | |
| Aug-18 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 |
