Marti Must Prove Its Profit Turn Can Absorb A 10-City Expansion Push
Three months ago Marti Technologies delivered the kind of quarter that changes how a small-cap story gets told: revenue up 141% from a year earlier, a record 77% gross margin, a first meaningful positive adjusted EBITDA print, and a full-year outlook lifted sharply on both the top and bottom lines. The report due before the open on November 9 is the first chance to see whether that inflection holds up while the company spends aggressively to widen its footprint across Türkiye.
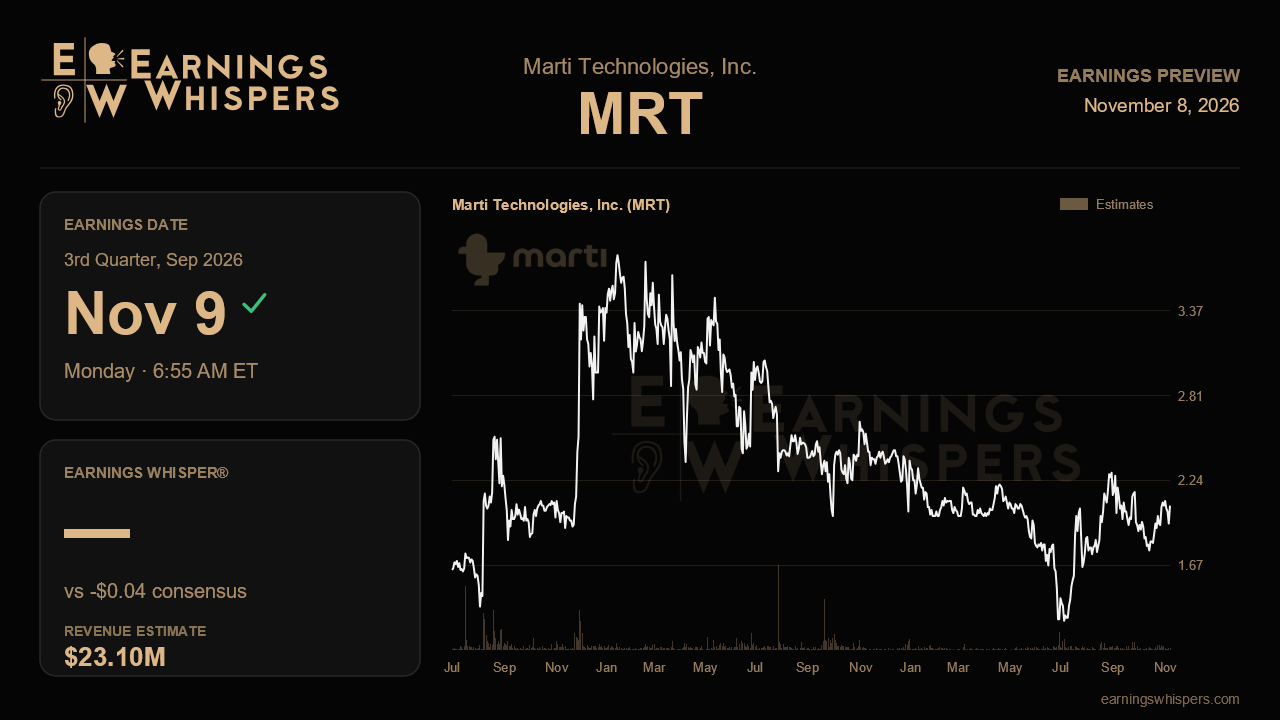
Wall Street is looking for third-quarter revenue of about $23.1 million, up roughly 15% from the $20.0 million booked in the second quarter, and a loss of $0.04 per share. That loss estimate compares with a $0.15 loss last quarter, though the earlier figure was inflated by a one-time, non-cash $8.3 million charge tied to a convertible note amendment. Excluding that item, the underlying net loss had already narrowed to $4.2 million from $9.2 million a year earlier, so the Street is essentially betting the improvement keeps compounding rather than banking on a sudden leap.
The guidance math is where the setup gets interesting. Management raised its 2026 revenue target to roughly $85 million from the $70 million it had held through two prior calls, and has since reaffirmed that figure. Consensus sits right on top of it. With $35.4 million generated in the first half, the company needs about $49.6 million in the back half, and the Street's third-quarter number implies something near $26.5 million in the fourth. That is not a heroic ask given that the first half already captured 42% of the annual target versus a 37% seasonal share last year. The flip side is that a guide reaffirmed rather than lifted again leaves room for upside, and a quarter that clearly clears $23 million would invite questions about whether $85 million is conservative.
Profitability is the more demanding test. Adjusted EBITDA guidance jumped sevenfold to about $7 million, and the first half contributed roughly $2.4 million, meaning the second half must produce around $4.6 million. Last quarter's $2.9 million showed the run rate is achievable, but the company launched 10 new cities during the third quarter, expanding to 30 cities covering about 85% of national GDP. New markets typically arrive with marketing and driver-acquisition costs before monetization catches up. Evidence that validates the story would include gross margin holding in the high 70s and edging toward the roughly 80% level management now calls sustainable, continued growth in monetized cities beyond seven, and rider and driver counts moving toward the 4.9 million and 580,000 milestones. A margin dip, slowing trip growth from the 73% pace, or a take rate stuck in the mid-teens alongside rising expansion costs would challenge it. Investors should also look for confirmation that growth outside Istanbul, now more than half the business, keeps outpacing the core market.
The autonomous-vehicle partnership with Tensor is the newest and least proven catalyst. No revenue is expected from it yet, so the useful signals are qualitative: progress toward a broader multi-provider alliance, any movement on the pilot deployments referenced in the state-level AI plan, and reassurance that AV ambitions will not trigger heavy capital commitments before safety is demonstrated. Any update on national ride-hailing regulation would matter as well.
The market has treated Marti fairly well since the last report. Shares are roughly flat while the S&P 500 fell 4.6%, and the stock at $2.07 sits above its 200-day moving average of $1.95, holding most of the prior quarter's surge from $1.12. It remains about 11% below its post-earnings high of $2.32, so this is not a breakout setup. Sentiment has also turned noticeably less bearish than heading into the last report. The central question is simple: can Marti show that its newly positive EBITDA survives a rapid city rollout? If margins hold while the new markets scale, the raised outlook looks credible and possibly cautious; if expansion costs swamp the gains, the profitability inflection will look premature.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-08 | |
| Nov-06 | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Sep-10 | |
| Sep-03 | |
| Aug-19 | |
| Aug-19 | |
| Aug-17 | |
| Aug-12 | |
| Jul-30 | |
| Jul-14 |
