Marti Breaks Into Operating Profit, But Unchanged Guidance And Slowing Volume Growth Temper The Beat
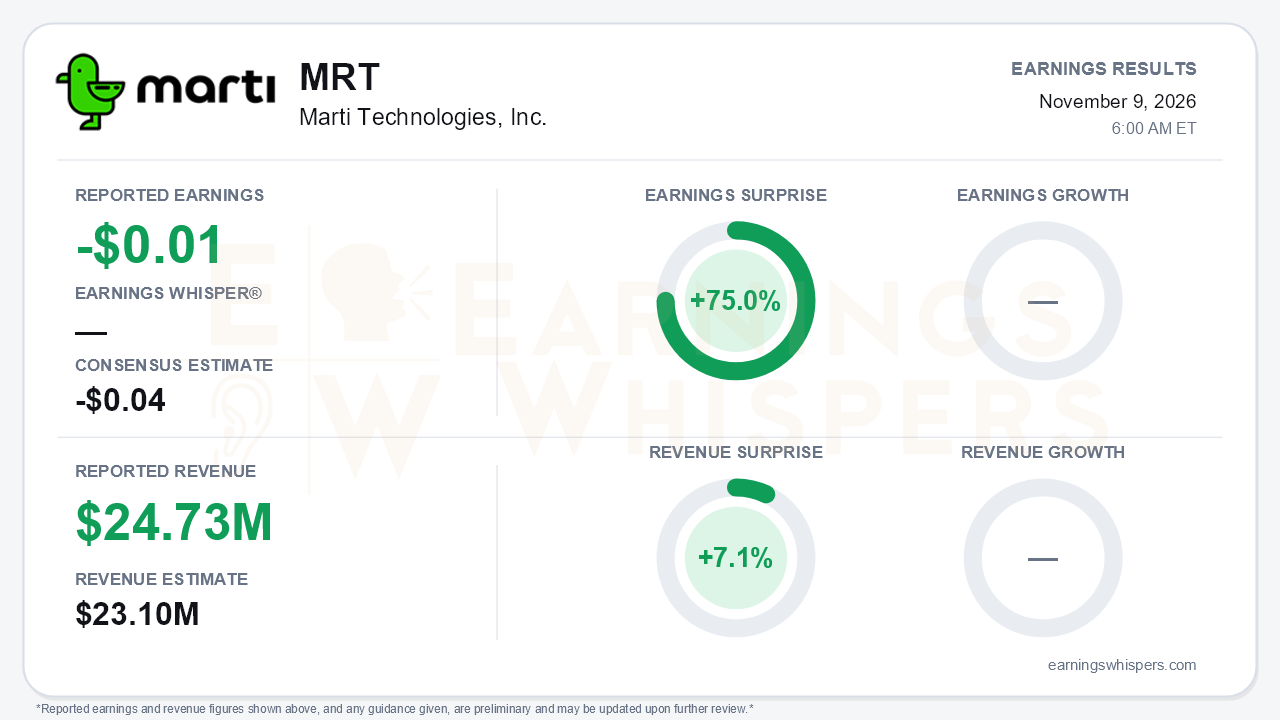
Marti Technologies delivered the profitability breakout that bulls have been waiting for. The Turkish mobility platform reported a third-quarter loss of $0.01 per share, beating the -$0.04 consensus by 75.0%. Revenue of $24.73 million topped the $23.1 million estimate by 7.1%. The more meaningful development sits below the EPS line. Marti posted positive income from operations for the first time, at $2.7 million versus an $8.8 million operating loss a year ago. Adjusted EBITDA nearly doubled sequentially to $5.6 million, a 22.7% margin. That is the headline story. The central tension is that management left full-year guidance unchanged, and the volume metrics that underpin the growth narrative are visibly decelerating.
The quality of the beat is better than most small-cap "adjusted" stories, though it has limits. Gross margin reached a record 81.5%, up from 76.6% in Q2, roughly 72% in Q1 and about 61% for fiscal 2025. Management conceded on the call that its earlier ~80% "sustainable" estimate may have been conservative. Total operating expenses, including cost of revenues, rose just 11.9% against company-reported revenue growth of 128.1%. G&A fell 17.2%, although a $2.0 million drop in share-based compensation drove much of that decline. The GAAP net loss narrowed to $1.0 million. Excluding $2.2 million of stock compensation, the company says it earned $1.2 million.
What stands between Marti and GAAP profitability is financing cost. Net financial expense was $3.7 million in the quarter, and the balance sheet carries $105.9 million of long-term financial liabilities against a stockholders' deficit of $83.3 million. Operating cash flow was positive for a second straight quarter at $1.0 million. Cash rose to $15.2 million, but year-to-date cash also benefited from $10.7 million of convertible note proceeds.
The call laid out a clear set of trajectories. Pricing is carrying the growth, and the user base is cooling. Revenue per trip jumped 56% to $1.13. Trip growth, however, slowed to 46% from 73% in Q2 and 93% in Q1. Unique consumer growth eased to 54% from 76% and 89%. Trips per consumer slipped to 8.2 from 8.6, which management attributed to new-city users ramping slowly. Revenue growth itself has stepped down each quarter, from 156% to 141% to 128%, even as absolute dollars set records.
The guidance math is where bears have legitimate ammunition. Nine-month revenue of $60.1 million against an $85 million target implies a Q4 roughly flat with Q3. Nine-month adjusted EBITDA of $8.0 million already exceeds the $7 million full-year guide, which implies a fourth quarter near or below breakeven. That reflects seasonal softness and heavier marketing as Marti pushes into 10 new cities. Management may be sandbagging, but it chose not to raise.
The forward catalysts are real. The ride-hailing footprint expanded to 40 cities covering roughly 90% of Türkiye's GDP. Rider and driver counts of 5.09 million and 597,000 beat September targets, and new year-end goals are 5.65 million and 630,000. Monetization is still limited to about 8-9 cities with no take-rate increases assumed, which leaves visible upside if pricing extends to newer markets. A 2027 outlook is expected before year-end. Marti also added CalmCar as a second autonomous-vehicle partner, with closed-area Istanbul testing pending permits. A favorable appeals ruling helped on the legal front, though that litigation is moving to a higher court. On the other side, dilution is a growing concern. The quarter brought 5 million commitment shares and a new management incentive plan equal to 10% of fully diluted shares. Most of the convertible debt converts at $1.65, below the current share price, and the $100 million facility now runs through July 2028.
Investor sentiment remained negative but improved meaningfully heading into the report, rising from -0.41 to -0.19. The stock has been far less enthusiastic. At $2.07, shares were essentially unchanged from the $2.08 open after the August report. They sat about 11% below the late-August high of $2.32 and 20% above the mid-October low of $1.72, holding roughly 6% above the 200-day moving average. Most Earnings Whispers trend readings are currently positive, with price, momentum and sequential growth all pointing up.
The bottom line is that Marti proved its platform can generate operating profit. Record gross margins and expense discipline delivered a clean beat on both lines. Unchanged guidance, decelerating trip and user growth, heavy convertible debt and mounting dilution keep the setup more complicated than the surprise implies. The 2027 outlook and the pace of monetization in newer cities will likely determine whether this quarter marks a durable inflection or a seasonal peak.
Read our earnings preview for Marti Technologies, Inc.: https://www.earningswhispers.com/article/MRT/23036
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-08 | |
| Nov-06 | |
| Nov-02 | |
| Oct-30 | |
| Oct-28 | |
| Sep-10 | |
| Sep-03 | |
| Aug-19 | |
| Aug-19 | |
| Aug-17 | |
| Aug-12 | |
| Jul-30 | |
| Jul-14 |
