Noodles & Co. Must Show Its Comp Surge Can Outrun Closures And A Gloomy Street
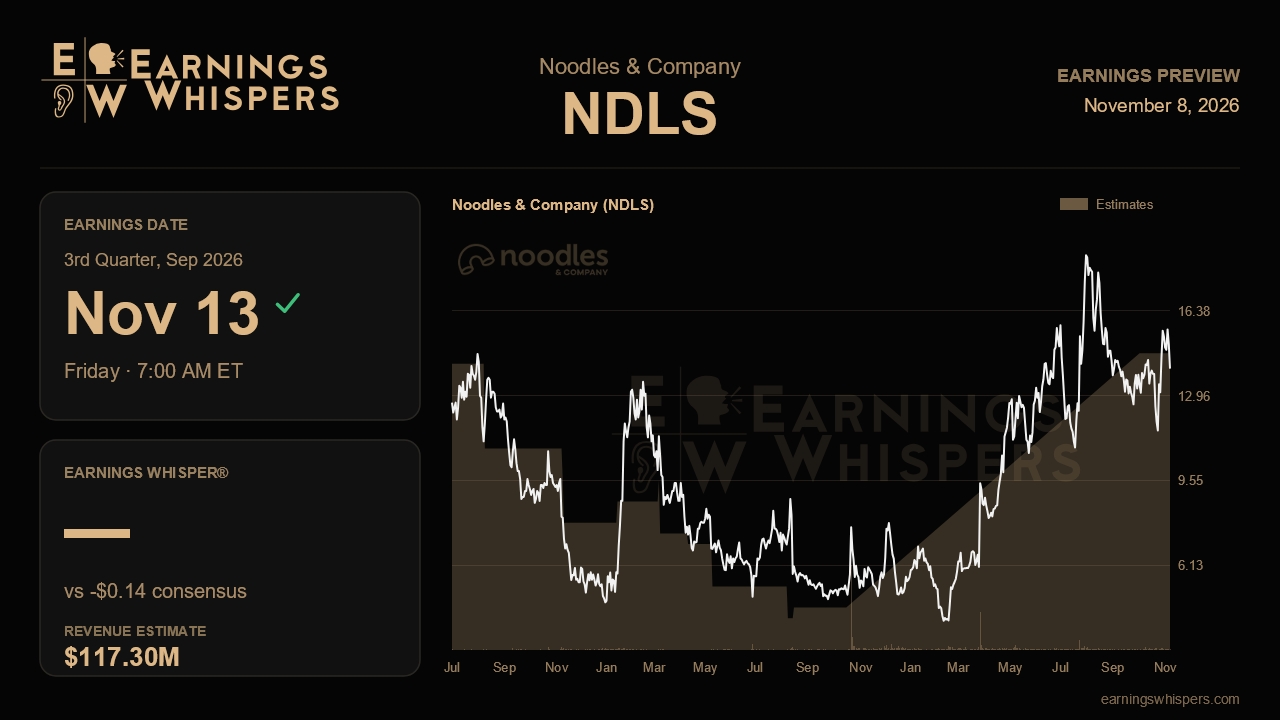
Few restaurant turnarounds have looked as tidy on paper as Noodles & Company's over the past year, yet the stock has slid since the last report and Wall Street is bracing for a wider loss. That gap between an operating story that keeps getting better and estimates that seem to point the other way is what makes the third-quarter release, due before the bell on November 13, worth close attention.
Consensus calls for a loss of 14 cents a share, deeper than the 10-cent loss a year ago, on revenue of about $117.3 million, down roughly 3.9% from $122.1 million. On its face that reads like contraction. The explanation is mostly portfolio pruning: management has been closing underperforming units, which flatters same-store comparisons while shrinking the top line. The revenue estimate looks easily reconcilable with that strategy. The deeper projected loss is harder to square with a company that raised full-year guidance for adjusted EBITDA to $34 million to $38 million and restaurant contribution margin to 16% to 17%. Some of that may reflect closure-related impairments, which hit the second quarter for $4.8 million, but it suggests analysts are leaving room for a quarter that looks less spectacular than the spring.
The prior call set a high bar. Company comps have climbed four straight quarters, from 4.0% to 11.4%, and traffic swung from a slight decline to a 7.6% gain. Management said the third quarter was tracking near 10% at the time of the call, a modest step down from the second quarter but still well above the 4.0% posted a year earlier. Delivering a final figure close to that pace, with traffic still doing most of the work, would validate the claim that the menu overhaul is drawing genuinely new customers rather than simply pushing price. A slide toward high single digits would not break the thesis, but it would invite questions about whether the Coca-Cola Fanta tie-in for Mac Month and the August baked limited-time offer kept momentum alive. Investors should also look for management to quantify how much of the comp still comes from closures, which contributed roughly 250 to 300 basis points last quarter.
Margins are the other test. Restaurant contribution margin jumped to 17.2% in the second quarter, a five-year best, against 13.2% in the year-ago third quarter. Holding something in the mid-teens or better would keep the full-year range credible, while rising third-party delivery fees, which already added 60 basis points to other operating costs, are the most visible source of leakage. A fourth guidance raise would be impressive after three straight increases; a simple reaffirmation could be read as a ceiling. Commentary on the fourth-quarter ramen platform, which management floated as a possible permanent category, will shape how the market views next year.
Then there is the balance sheet. Debt has edged down to $105.4 million and management targets year-end net leverage at or below 3.0 times, but the credit facility matures in the third quarter of fiscal 2027 and the strategic alternatives review remains open. Any update on refinancing or the review could move the shares as much as the quarter itself. The widening gap between franchise comps at 5.5% and company comps deserves a clearer explanation too.
Sentiment is mildly bearish, and the stock has lost 8.6% since the last report, lagging the S&P 500 by about 8 points. At $14.05 it trades well above its 200-day average of $11.49 but in the lower half of a post-earnings range stretching from $11.56 to $19.00, so the market has clearly given back some of its enthusiasm. That means the bar may be lower than the operating trends suggest. The question is whether Noodles can prove that double-digit-like traffic-driven comps and expanding margins can translate into earnings, and a financing path, durable enough to make a shrinking store base look like a strength rather than a retreat.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-08 | |
| Oct-23 | |
| Oct-16 | |
| Oct-14 | |
| Sep-23 | |
| Sep-16 | |
| Aug-05 | |
| Jul-27 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-24 | |
| Jul-22 | |
| Jul-09 | |
| Jun-24 |
