Noodles & Company Beats Handily, But October Comp Slowdown And Flat Guidance Midpoints Show The Turnaround Is Losing Speed
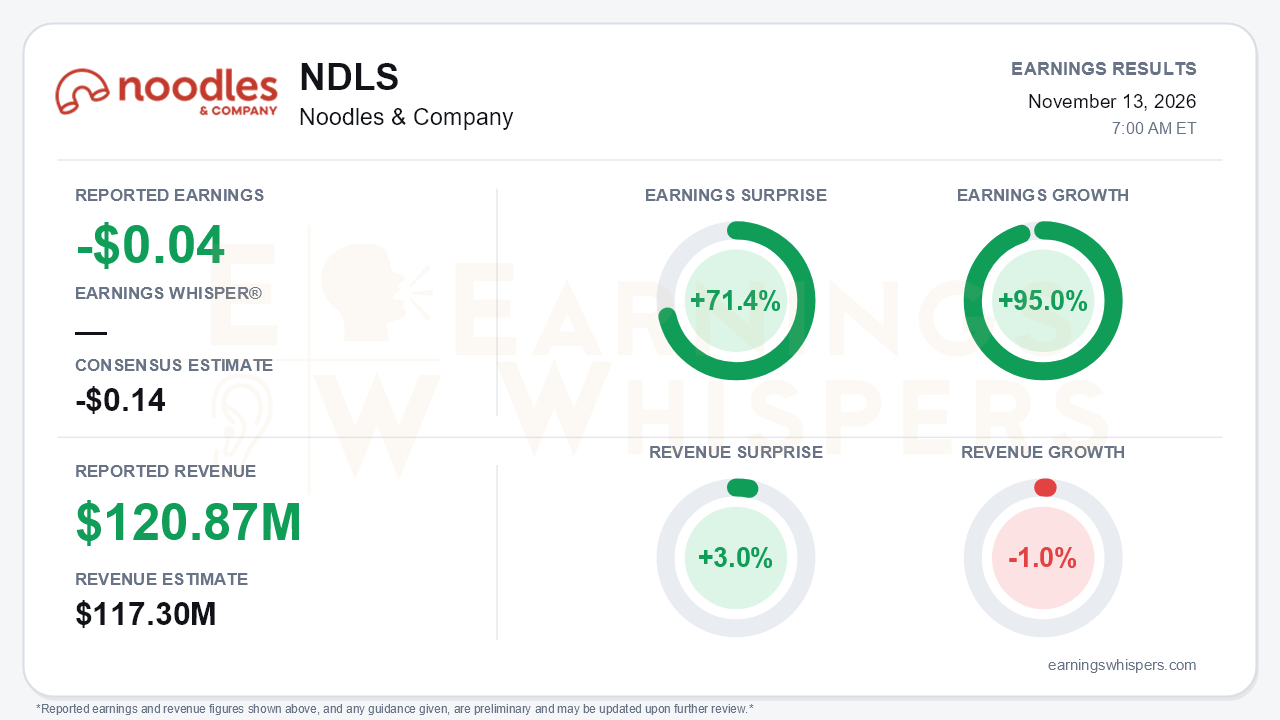
Noodles & Company delivered another clean beat in the third quarter. The adjusted loss of $0.04 per share topped the -$0.14 consensus by 71.4%, and earnings improved 95.0% from the year-ago adjusted loss of $0.82. Revenue of $120.87 million beat expectations by 3.0% but fell 1.0% year over year, because aggressive store closures still outweigh strong comparable sales. The quarter itself was strong. The central tension is that nearly every rate of improvement is now slowing, and management's guidance stopped moving higher after two consecutive raises.
The quality of the beat is better than a turnaround story usually offers, though GAAP results still show the cost of the restructuring. The GAAP net loss narrowed to $2.1 million, or $0.36 per share, from $9.2 million, or $1.58 per share. Operating income turned slightly positive at $145,000 versus a $6.3 million operating loss a year ago. The improvement came from the restaurants:
- Restaurant contribution margin expanded 350 basis points to 16.7%.
- Labor fell to roughly 29.5% of restaurant revenue from about 31.4%.
- Cost of sales and occupancy also improved as a share of sales.
- Adjusted EBITDA rose 34.3% to $8.7 million.
The drags were narrower. Third-party delivery fees pushed other operating costs higher, and G&A climbed to $13.6 million from $12.3 million, partly on transaction costs tied to the strategic review. The gap between the adjusted and GAAP loss consists mostly of impairments, severance, and transaction costs. Those charges are shrinking as the closure program matures.
The operating trends hold up well on their own but look weaker in sequence. System-wide comps rose 9.5%, with company-owned comps at 10.7%. That marked the third straight quarter above 9% and the eighth consecutive positive quarter. Company traffic rose 7.8%, slightly better than Q2's 7.6%, and company AUVs reached $1.545 million, up 15.2% from a year ago. The second derivative has turned, however:
- Company comps went from 11.4% in Q2 to 10.7% in Q3, then slowed to 5.5% in October against last year's chili garlic ramen promotion.
- Year-over-year margin expansion narrowed from 460 basis points in Q1 and 440 in Q2 to 350.
- Adjusted EBITDA growth slowed from more than triple in Q1 and 79% in Q2 to 34%.
- Franchise comps of 4.9% continue to trail company stores badly.
Management's tone also cooled. After calling Noodles 'back… faster than anticipated' last quarter, it now describes itself as 'mindful of the broader consumer environment.'
Guidance reflects that shift. Fiscal 2026 ranges were tightened rather than raised:
- Revenue: $485 million to $495 million, with the top end trimmed.
- Adjusted EBITDA: $35 million to $37 million, holding the $36 million midpoint.
- Comparable sales: 9% to 10%.
- Restaurant contribution margin: 16.0% to 16.7%, which slips the midpoint slightly.
The EBITDA range implies roughly $8 million to $10 million in fourth-quarter adjusted EBITDA, which is credible but not a further leg up. Closure targets moved higher to 34-36 company-owned and 7-8 franchised restaurants, which explains the softer revenue ceiling.
The forward catalysts are real:
- Ramen became a permanent platform in October with double-digit menu mix.
- The baked cheese tortelloni launch drove the year's best new-guest return rate.
- Closures are expected to taper to roughly 10-15 in 2027, so revenue declines from closures should fade.
The balance sheet remains the overriding risk. The company ended the quarter with just $1.5 million in cash, $101.0 million of debt, $21.2 million of revolver availability, and a stockholders' deficit of $52.7 million. Debt is down more than $9 million year to date. The credit facility amendment extending maturity to November 30, 2027 buys time, but it does not resolve the strategic review, which has now run for more than a year without an outcome.
The market has already been discounting this slowdown. Shares hit a 52-week high of $19.00 on July 31, shortly after the Q2 report, then slid to $11.56 by October 22. Entering this report, the stock sat at $13.75, down 10.5% from the open after the prior release and 27.6% below that peak. It still holds 18.1% above its 200-day moving average and has recovered about 19% off the October low. Investor sentiment stands at a mildly negative -0.17, consistent with a market that respects the operating repair but is skeptical of how far it can run. The internal trend readings are mixed, with momentum positive while AVWAP remains negative.
The bottom line is that Noodles posted a genuinely good quarter, with record-level restaurant economics, positive GAAP operating income, and a convincing earnings beat. However, the report marks a shift from acceleration to consolidation. The October comp slowdown, narrowing margin gains, and guidance held at an unchanged midpoint give bears legitimate ammunition. A thin cash position and an unresolved strategic review keep the capital structure at the center of the investment case. Ramen and the end of heavy closures offer a path forward, but investors now need evidence that comps can reaccelerate against tougher comparisons.
Read our earnings preview for Noodles & Company: https://www.earningswhispers.com/article/NDLS/23045
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 3 hours | |
| 6 hours | |
| 8 hours | |
| 9 hours | |
| 9 hours | |
| 9 hours | |
| Nov-08 | |
| Oct-23 | |
| Oct-16 | |
| Oct-14 | |
| Sep-23 | |
| Sep-16 | |
| Aug-05 | |
| Jul-27 |
