Creative Realities Must Deliver Its Promised Record Quarter As Shares Slide Toward Their Lows
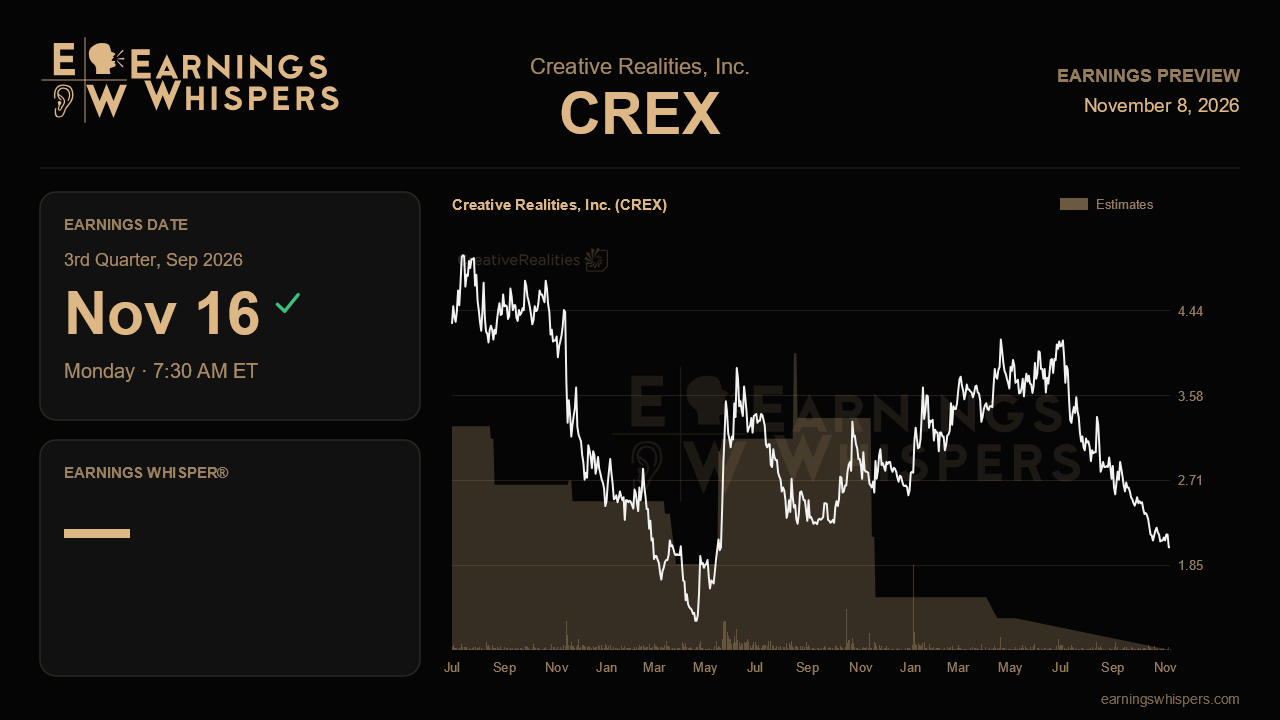
Three months ago, Creative Realities management made a bold, checkable promise: the September quarter would be the largest revenue quarter in company history, topping the $23.9 million posted in the fourth quarter of fiscal 2025. That pledge came alongside a newly named marquee customer in Albertsons, the removal of a going concern warning, and a CEO who bought a piece of the company's equity raise himself. The market has not given the story much credit. The stock has fallen roughly a third since that report and now trades near $2, so the November 16 release, due before the open, is less about modest beats than about whether the turnaround narrative is real.
There is no usable Street consensus for earnings per share or revenue going into the print, so the most meaningful bar is the one management set. For context, the year-ago third quarter produced just $10.5 million in revenue and a loss of $0.32 per share. A record quarter above $23.9 million would therefore mean revenue more than doubling year over year, building on the $21.5 million reported last quarter. Anything short of a new high would be a direct miss against the company's own framing, and that matters more for credibility than any analyst estimate would.
The credibility question is sharpened by what management stopped saying. In earlier calls, executives emphasized a fiscal 2026 revenue target above $100 million and adjusted EBITDA margins in the high teens to 20%. Last quarter those figures went unrepeated, replaced by sequential guidance that Q3 would set a record and Q4 would exceed Q3. Reaching $100 million would require an exceptionally strong second half after a weather-hit $16.3 million first quarter, so listen closely for whether management reaffirms, quietly drops, or explicitly lowers the full-year ambition. Adjusted EBITDA, which swung to a $2.0 million profit last quarter from a loss in Q1, should scale meaningfully on record revenue if synergy savings, already at about $7.5 million of a $10 million target, continue to flow.
Gross margin remains the weak spot. Consolidated margin recovered to 38.6% last quarter from 34.2% in Q1 but sat well below the 45.7% of a year earlier, with hardware margins at just 17.2% and service margins squeezed by expired higher-margin contracts and discounting competitors. Management has already conceded that margins above 40% likely will not return until 2027, so a record quarter driven by low-margin hardware installs could still disappoint on profitability. Stable or improving margin from the 38.6% level would validate the plan; a slip back toward the Q1 trough would challenge it.
The longer-term case rests on recurring revenue. Annual recurring revenue edged up to $20.5 million, with roughly $4 million to $5 million of contracted backlog set to switch on January 1, 2027. Updates on the Albertsons rollout beyond its roughly 3,000 live screens, and on whether the national cellular retailer and quick-service restaurant contracts described as in final stages have actually been signed, will show whether 2027 SaaS growth is materializing. Progress on the AMC lobby network and Lexus/Toyota Canada migration adds support. Investors should also watch debt, which climbed to $46.6 million, against cash of $10.7 million.
Sentiment has softened from deeply bearish to merely skeptical, improving to 46.3% bearish from 78.4% a quarter ago, yet the stock tells a gloomier story. Shares sit well beneath their 200-day moving average of $3.25 and near the $1.94 low of the post-earnings range, below the entire $2.80 to $4.38 band of the prior quarter. That washed-out positioning means a clean record quarter could be rewarded, but the core issue is simple: Creative Realities must show the revenue inflection it promised while proving that margins and leverage are not eroding the value of that growth.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-03 | |
| Oct-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-04 | |
| Jul-29 | |
| Jun-29 | |
| Jun-29 | |
| Jun-10 | |
| Jun-09 | |
| Jun-09 | |
| May-19 | |
| May-15 |
