Creative Realities Posts Record Revenue And A Wave Of Logo Wins, But Fading Margin Targets And A Steep Q4 Hurdle Keep The Stock Pinned Near Lows
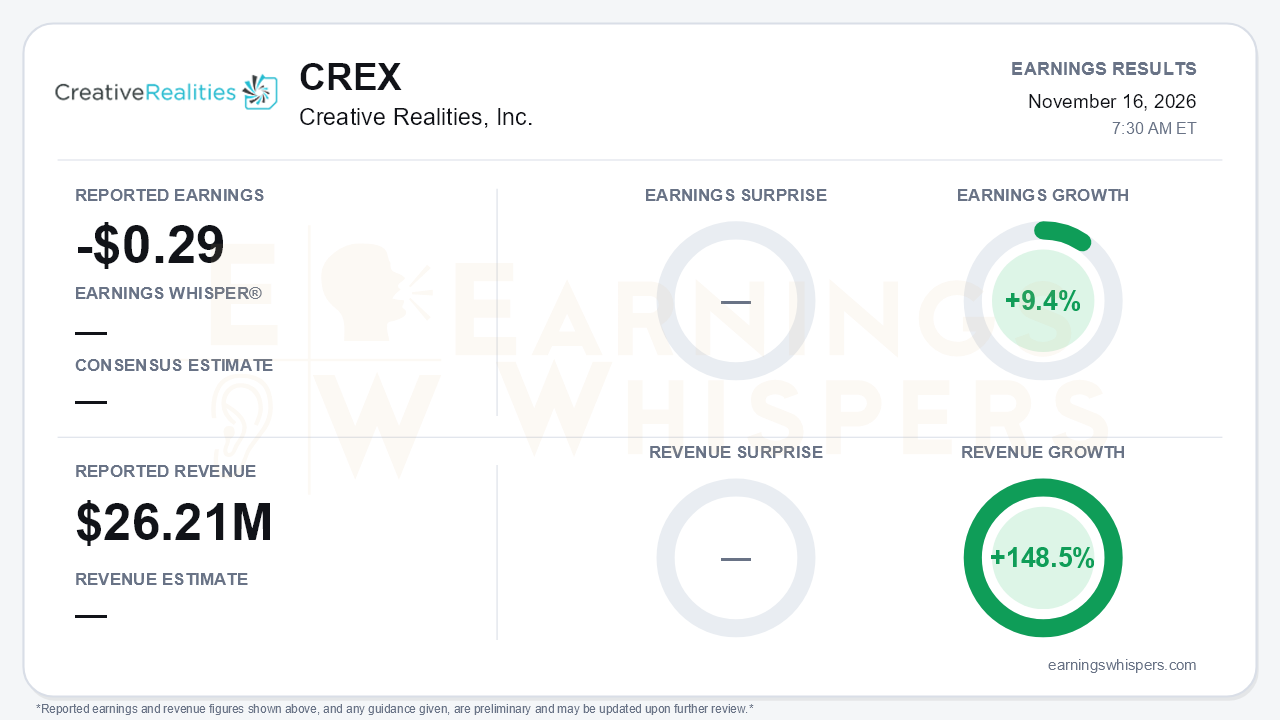
Creative Realities delivered the biggest top line in its history for the third quarter, but the quality of that growth deserves scrutiny. The digital signage and retail media provider reported a loss of $0.29 per share on revenue of $26.21 million. Revenue grew 148.5% year over year, and Earnings Whispers calculates earnings growth of 9.4%. In plain terms, the GAAP loss per share narrowed from $0.75 a year earlier, though that prior-year figure carried a $5.7 million software impairment. No consensus figures were available, so the story is less about beating estimates and more about whether record volume is turning into durable profitability. The central tension is that customer momentum is clearly accelerating while margin ambitions and execution timelines are quietly slipping.
The headline growth is heavily inorganic. Roughly $8.0 million of the quarter's sales came from Cineplex Digital Media (CDM), the acquired subsidiary. Hardware sales nearly tripled to $11.4 million, and services rose to $14.9 million. Mix worked against profitability. Consolidated gross margin fell to 37.1% from 45.3% a year ago. Hardware margin dropped to 18.5% from 30.0%, and services margin slipped to 51.4% from 55.3% as some customer contracts expired. Operating expenses roughly doubled with CDM's inclusion, and interest expense more than doubled to $1.2 million. Adjusted EBITDA improved to $2.7 million from $0.8 million, but it represents only about a 10% margin. The operating loss was still $2.4 million.
The sequential trend is more encouraging. Revenue climbed from $16.3 million in Q1 and $21.5 million in Q2. Adjusted EBITDA moved from a $0.5 million loss in Q1 to $2.0 million in Q2 and then $2.7 million. ARR rose to $21.7 million from $20.5 million. Segment gross margins also ticked up sequentially. The commercial pipeline was the real highlight of the call. Management added several new customers:
- Zaxby's, with more than 1,000 locations;
- KFC;
- Krispy Kreme;
- Cellular Sales, with about 800 stores;
- Toyota/Lexus Canada, formally announced.
A new 10-location state lottery pilot resembles the start of the $54 million North Carolina contract. The Nissan Stadium project grew to more than $10 million from $8.5 million. Management also guided to SaaS growth above 35% in 2027 and spoke more emphatically about share gains as a competitor heads toward closure.
Bears have legitimate ammunition, however. Consolidated gross margin declined sequentially from 38.6%, even though management had pointed to improvement in Q2. The EBITDA margin targets from earlier calls were not repeated: mid-teens for 2026, a 20% run rate by year-end, and later high teens. Several projects are running late:
- AMC/NCM lobby network completion has moved to mid-summer 2027, after Q1 commentary placed most of that $6-7 million in 2026.
- Albertsons sits at 6,000+ screens versus roughly 10,000 envisioned for 2026, although management said the rollout remains on track for completion by the end of Q2 2027.
The reaffirmed target of more than $100 million in 2026 revenue requires about $36 million in Q4 after $64 million through nine months. That is a roughly 37% sequential jump that depends on seasonality, stadium work and new installations. Management also acknowledged that onboarding volume is stressing internal processes. Remote CMS conversions carry little upfront hardware revenue, which sets up tougher 2027 comparisons.
The balance sheet remains a constraint. Cash fell to $1.8 million from $10.7 million at the end of Q2 as the company used proceeds from its equity raise to cut debt to $40.0 million. That reduces interest expense but leaves a thin liquidity cushion. Diluted shares rose to about 13.5 million from 10.5 million, and preferred dividends add another drag on common shareholders.
The market had already priced in skepticism. Shares fell 33.1% from the open after the August report to $2.02 just before this release. That puts the stock 37.4% below its 200-day moving average and only 3.9% above a 52-week low of $1.94 set on November 5. The stock has also given back all of its post-report spike to $3.56 in mid-August. Investor sentiment improved meaningfully, from -0.78 to -0.42, but remains firmly negative. The Earnings Whispers trend signals are mostly negative, with price and AVWAP readings weak, although momentum has turned positive.
The bottom line is that Creative Realities is winning business faster than it is converting that business into margin, cash, or on-time delivery. The customer wins and the 2027 SaaS outlook preserve a credible growth story, and the sequential improvement in EBITDA is real. Still, the dropped margin targets, slipping project timelines, thin cash and a demanding Q4 revenue requirement explain why the stock entered the report near its lows. Q4 execution against the $100 million target is now the key test of management credibility.
Read our earnings preview for Creative Realities, Inc.: https://www.earningswhispers.com/article/CREX/23054
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| 14 hours | |
| Nov-12 | |
| Nov-10 | |
| Nov-08 | |
| Nov-03 | |
| Oct-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-04 | |
| Jul-29 | |
| Jun-29 | |
| Jun-29 | |
| Jun-10 |
