Barfresh Must Show Its Milk Plant Repairs Are Working After A Guidance Cut Sank Shares 67%
Three months ago, Barfresh Food Group told investors that the acquisition meant to transform it was instead draining it. The ARPS dairy facility proved costlier and slower to ramp than diligence suggested, gross margin turned negative, and management swapped a positive full-year EBITDA target for a loss. The third-quarter report, due after the close on November 16, is the first real test of whether that reset marked the bottom or only the beginning of the repair work.
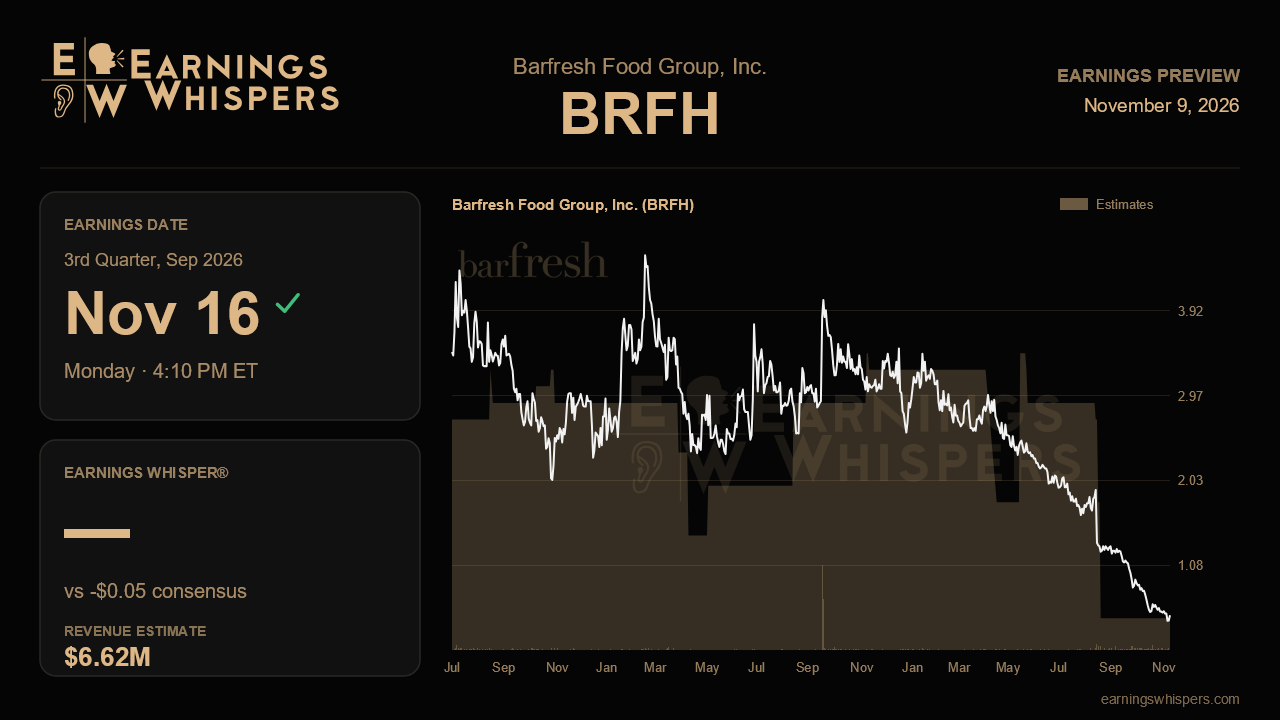
The Street is looking for a loss of about $0.05 per share on revenue near $6.6 million. That revenue figure would be roughly 56% above the $4.2 million posted a year ago and a sharp step up from the $4.7 million reported last quarter. The EPS estimate is worse than the $0.02 loss of a year earlier, but it would be a meaningful improvement on last quarter's $0.12 loss. In other words, analysts are betting on both a sequential revenue jump and a substantial recovery in unit economics at the same time. The ambition shows up in the annual numbers too. Management cut its 2026 revenue outlook to $23 million to $26 million from $28 million to $32 million, yet full-year consensus still sits around $28.5 million, above the top of the new range. Some of those estimates may simply be stale, but the gap means the quarterly bar could be set higher than the company itself implied.
The timing does offer a plausible path to stronger sales. Management pointed to new education district wins ramping for the 2026-27 school year, along with the multiyear contract from a large district, and the third quarter is when that business should start flowing. Evidence of those wins converting into orders, plus a recovery in the legacy frozen beverage line that management said was delayed, would support the revenue side of the story. A shortfall there would suggest the guidance cut was not conservative enough.
Margins matter even more. Gross margin slid from 37% a year ago to 18% in the first quarter and then to negative 3.2% in the second. Management attributed the damage to roughly $1.8 million of excess ARPS processing costs, about $0.8 million from ice cream mix production that had to be pulled because of equipment limits, higher material costs, and freight and cold-storage savings that never arrived. It described most of these as fixable, citing weekly throughput gains at the old plant. A return to clearly positive gross margin, any sign the ice cream business is coming back, and lower per-case processing costs would validate that claim. Another quarter near breakeven gross margin would undercut it badly. Updates on the new 44,000 square foot Defiance facility also carry weight, since construction costs rose and the mortgage and equipment financing were not finalized, with management conceding the economics might need rethinking. Paying off the Defiance mortgage and the $2.4 million grant help, but they do not fund the build.
The market has already rendered a harsh verdict. Shares have fallen 67% since the last report, against a 5.3% decline in the S&P 500, and at $0.46 they sit near the $0.42 low of the post-earnings range and far below the 200-day average of about $2.01. Last quarter's range of $1.63 to $2.53 now looks distant. Sentiment has nonetheless swung from bearish to strongly bullish, suggesting some traders see the selloff as overdone and are positioned for relief.
That sets up an unusual split: a stock priced for distress against estimates that assume a fairly quick recovery. The central question is whether gross margin has turned back up and whether management can reaffirm the lowered targets with credible financing for Defiance. If the plant fixes are showing up in the numbers, the in-housing thesis survives. If not, investors will likely conclude the second-quarter reset was only the first adjustment.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-09 | |
| Nov-05 | |
| Sep-08 | |
| Aug-24 | |
| Aug-19 | |
| Aug-19 | |
| Aug-17 | |
| Aug-14 | |
| Aug-13 | |
| Jul-31 | |
| Jul-27 | |
| Jul-08 | |
| May-18 |
