Barfresh Posts An Operational Recovery Quarter, But A Second Guidance Cut And A Revenue Miss Keep The Burden Of Proof High
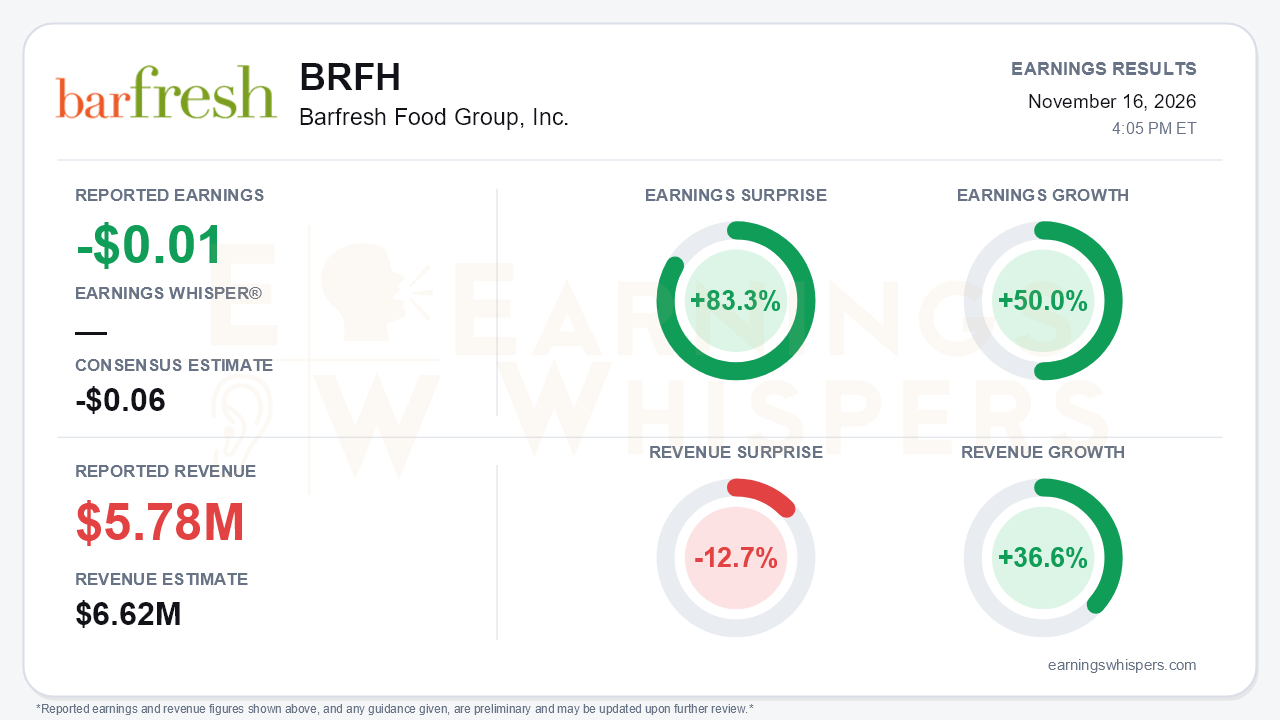
Barfresh Food Group delivered a quarter of two very different halves. On the bottom line, the company lost just $0.01 per share, beating the -$0.06 consensus by 83.3% and improving 50.0% year over year. It also produced operating income of $120,000 against a $260,000 operating loss a year ago. The top line told another story. Revenue of $5.78 million rose 36.6% but missed the $6.62 million consensus by 12.7%. Management then cut full-year 2026 revenue guidance for the second consecutive quarter, to $20 million to $22 million from $23 million to $26 million. That range was $28 million to $32 million as recently as the first-quarter call. That is the central tension: the plant is finally working better, but the revenue base it is supposed to serve keeps shrinking in management's own forecasts.
The quality of the beat deserves scrutiny. G&A fell to $329,000 from $844,000. The largest driver was a $201,000 non-cash reversal of stock compensation tied to forfeited awards from employees who left during the quarter, plus a small acquisition-expense credit. Strip out that reversal and the reported operating profit essentially disappears. Interest expense jumped to $344,000 from $30,000 because of the March convertible note, which kept the company at a $224,000 net loss. Adjusted EBITDA was a $15,000 loss, worse than the $153,000 profit a year ago. The headline growth is also almost entirely acquired. Arps Dairy milk sales contributed $2.5 million, while the legacy frozen beverage and food segment fell 23% to $3.2 million as previously lost menu placements have not come back. With Arps anniversarying in early October, the acquisition tailwind that drove 83% nine-month growth is about to fade. Subtracting nine-month revenue of $16.1 million from the new guidance implies fourth-quarter revenue of roughly $3.9 million to $5.9 million, with the low end well below what Barfresh just reported.
The sequential operating improvement is nonetheless real, and it is the strongest part of the bull argument. Gross margin recovered to 21% from -3.2% in the second quarter and 18% in the first. That is still far below the 37% of a year ago, reflecting lower-margin milk sales and an inefficient plant. Adjusted EBITDA improved from roughly a $1.2 million loss in the second quarter to near breakeven. The Arps facility now produces 100% of frozen beverage volume, up from about half in the first quarter, and recently hit its weekly production target. Commercial traction appears to be returning: Barfresh added 50 Ohio school districts and returned to the nation's fourth-largest school district with carton smoothies for the 2026-27 year. Management's tone was steadier than last quarter. The CEO said the quarter "came in as we expected," and positive fourth-quarter adjusted EBITDA was reiterated. Notably, however, no full-year adjusted EBITDA figure was restated after earlier guidance swung from a $3.2 million to $3.8 million profit to a $1 million to $2 million loss.
The forward story now rests on the 44,000-square-foot Defiance facility, and its timeline has slipped again, from the fourth quarter of 2026 to early-to-mid 2027. The USDA extended the $2.47 million grant deadline to April 30, 2027. The landlord will also let the existing plant operate penalty-free through June 2027, which buys time. Barfresh is talking with three banks about a mortgage of roughly $4.2 million to $4.5 million plus $2 million to $3 million of equipment financing to cover about $6.2 million of remaining costs. Management expects that package to avoid an equity raise, but none of it is finalized. With only $2.4 million of cash and receivables, the margin for further delay is thin. Bears also have legitimate ammunition beyond the numbers: the old plant still suffers frequent breakdowns, the ice cream mix business remains suspended, and the controller rather than the CFO presented the financials.
Investor sentiment moved sharply the other way. It swung from mildly negative before the report to the top of the scale, a reversal that likely reflects relief at near-breakeven results and clearer financing paths. The tape has been far less forgiving. Shares have fallen 67.1% since opening at $1.40 after the August report. They sit 76.3% below the 200-day moving average and just 9.8% above the $0.42 52-week low set on November 5. The Earnings Whispers trend signals remain mostly negative, with price momentum and AVWAP still deteriorating.
The bottom line is that Barfresh showed its manufacturing problems are becoming manageable. Investors, however, must now underwrite a smaller revenue base, a declining legacy segment, a delayed new plant, and financing that is still under negotiation. The earnings beat leaned on a one-time compensation reversal, while the revenue miss and guidance cut reflect ongoing commercial damage. Until bank financing closes and frozen beverage sales stop shrinking, the improved quarter is more stabilization than turnaround.
Read our earnings preview for Barfresh Food Group, Inc.: https://www.earningswhispers.com/article/BRFH/23067
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-09 | |
| Nov-05 | |
| Sep-08 | |
| Aug-24 | |
| Aug-19 | |
| Aug-19 | |
| Aug-17 | |
| Aug-14 | |
| Aug-13 | |
| Jul-31 | |
| Jul-27 | |
| Jul-08 | |
| May-18 |
