Teamshares Faces A Proof Test After Halving: Can Acquired Revenue Narrow The Losses?
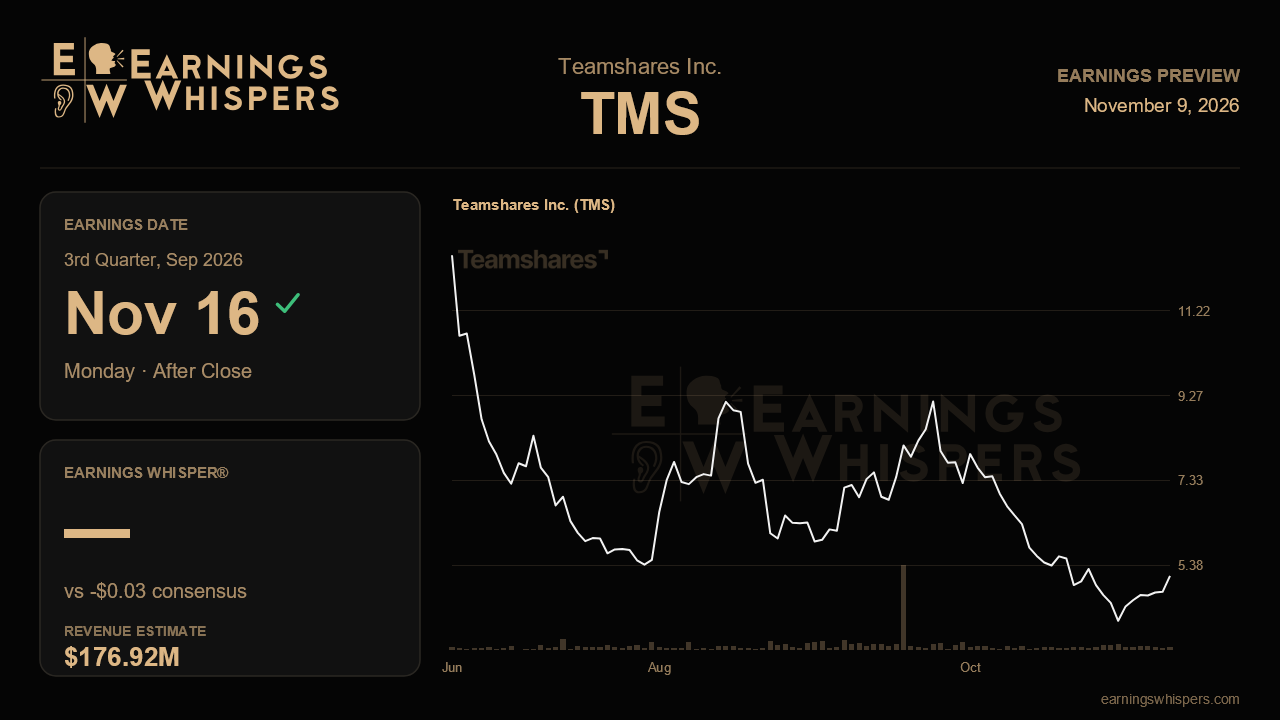
Few stocks arrive at an earnings report with as much to prove as Teamshares. Shares of the acquirer of small and midsize businesses have lost roughly half their value since the last report, falling 49% while the S&P 500 slipped about 5.6%. Yet the Street is modeling a quarter that looks like clear progress on paper, with revenue jumping and losses shrinking sharply. When results land after the close on November 16, the key question is whether the business is actually improving or whether a falling share price has been signaling doubts the consensus model has not yet absorbed.
Analysts expect a loss of 3 cents a share on revenue of about $176.9 million. That compares with a loss of 11 cents on $148.7 million in the prior quarter, which implies roughly 19% sequential revenue growth and a loss cut by more than two thirds. For a company built on buying businesses from retiring owners and holding them permanently, a step-up of that size is most likely tied to the pace and timing of acquisitions rather than to organic demand alone. That distinction matters. Acquired revenue proves Teamshares can put capital to work. It does not, by itself, prove that the companies it buys run better under its ownership, which is the core of the tech-enabled pitch.
With no formal guidance on record and little management commentary to anchor expectations, the report itself becomes the main source of evidence. A result near the revenue consensus paired with a loss at or below 3 cents would suggest that the portfolio is reaching enough scale to absorb the corporate overhead of a young public company. That is the operating leverage story investors need to see. A revenue figure that meets estimates while the loss stays near the prior quarter's level would challenge the narrative, because it would imply that each new acquisition is adding sales without adding much to the bottom line. Investors should look past the headline totals toward whatever the company discloses about same-store performance at businesses it has owned for a full year, margins at the operating company level, and how it is financing new deals. Dilution or rising debt costs could easily eat into any per-share improvement.
The mood has soured noticeably. Sentiment heading into the prior report leaned bullish, at roughly two-thirds positive, but it has flipped to modestly bearish this time. Combined with the price collapse, that suggests the market is no longer extending the benefit of the doubt that often accompanies newly listed companies. The chart tells a similar story. At $4.77, the stock trades at well under half its 200-day moving average of $11.70 and sits toward the bottom of its post-earnings range, which stretches from a low of $3.89 to a high of $9.79. That leaves it far from any breakout and closer to retesting its lows than reclaiming lost ground.
There is a contrarian angle here. If the consensus figures are achievable, the stock is priced for something worse than what analysts are actually modeling, and a clean quarter could ease some pressure. But the bar is less about beating by a penny and more about credibility. Teamshares needs to show that the sharp narrowing in losses is real and repeatable, driven by a portfolio of acquired businesses generating dependable profit, rather than a one-time lift from deal timing. If it can demonstrate that the acquisition engine produces earnings, not just revenue, the investment case remains intact. If it cannot, the market's verdict over the past three months may prove to have been early rather than excessive.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-19 | |
| Sep-23 | |
| Sep-02 | |
| Aug-14 | |
| Jul-24 | |
| Jun-30 | |
| Jun-23 |
