Teamshares Misses Badly On The Headline But Funds Its Acquisition Engine; Expensive Preferred Capital And Year-End Deal Timing Are Now The Story
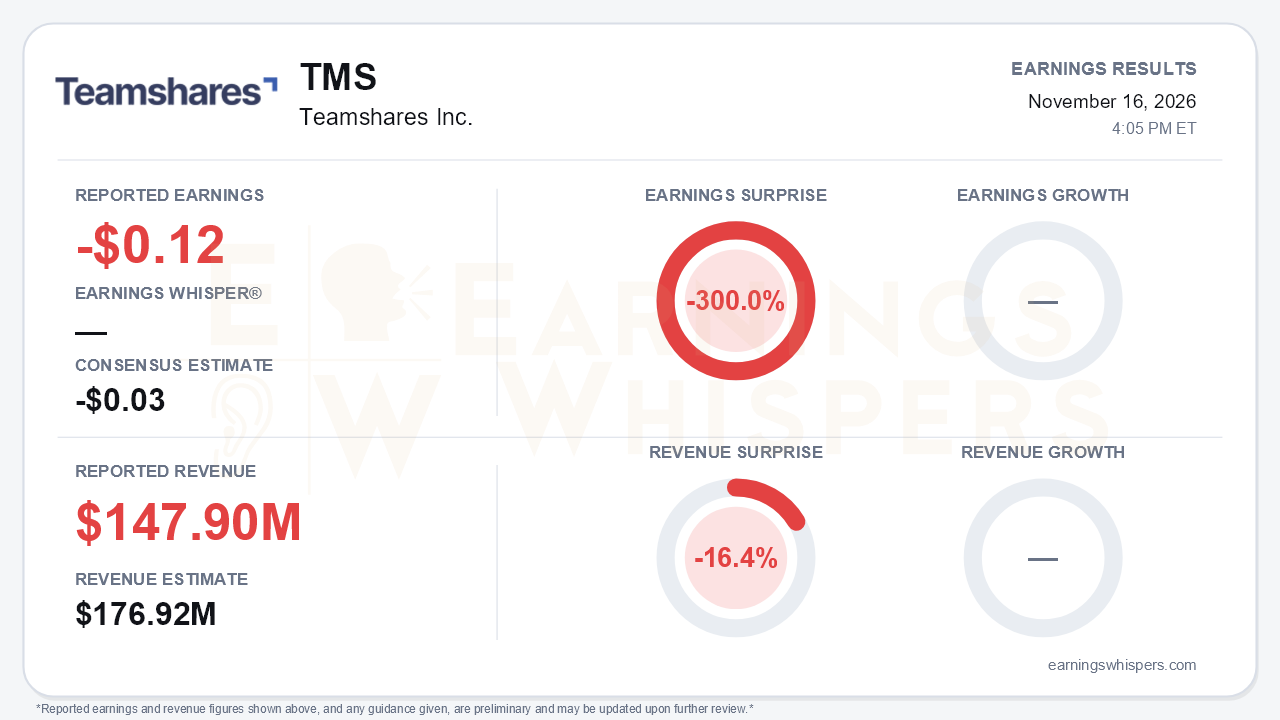
Teamshares (NASDAQ: TMS) missed expectations in its third quarter. It reported a loss of $0.12 per share against a consensus loss of $0.03, a 300.0% negative surprise. Revenue of $147.9 million fell 16.4% short of the $176.92 million consensus.
One reconciliation point matters. The company's GAAP statement shows a basic and diluted loss of $0.14 per share attributable to common stockholders. That figure includes $0.8 million of preferred dividends and accretion. The normalized $0.12 loss is the basis for the comparison with estimates.
Either way, the miss contrasts sharply with what management emphasized. Revenue rose 24% year over year, faster than the 20% pace in the second quarter. Adjusted EBITDA jumped to $4.9 million from $0.7 million. The size of the revenue shortfall against consensus suggests expectations assumed more acquired revenue than the deal-closing timeline delivered. That is our inference; the company did not say so. That gap between Street modeling and the actual pace of closings is the central tension.
The quality of the quarter deserves scrutiny. Segment-level results were strong:
- SME segment EBITDA rose 62% to $17.8 million, up from 47% growth in the second quarter.
- Gross profit grew 28%, faster than revenue.
The GAAP picture moved the other way:
- Net loss widened to $9.3 million from $6.4 million.
- The operating line swung to a $3.2 million loss from $2.1 million of operating income.
The prior-year comparison is flattered by a $6.9 million gain on asset dispositions that did not recur. A $7.5 million non-cash fair-value gain on earnout shares cushioned the current quarter. Net interest expense of $9.3 million still consumed nearly twice the quarter's Adjusted EBITDA. Corporate expenses rose $2.3 million year over year, which management tied to public-company compliance costs and financing options it did not pursue. Year-to-date free cash flow improved to negative $22.4 million from negative $39.1 million, but it remains negative.
The call preserved a credible growth story, but organic trends are not the engine. Third-quarter organic revenue growth was 3.6%. Organic segment EBITDA growth improved to 2.3% from 0.4% in the second quarter. On a year-to-date basis, however, organic EBITDA growth slipped to 3.7% from 4.6%, and organic revenue growth eased to 4.0% from 4.2%. Management cited consumer strength offsetting softness in some end markets.
The real change was execution on deals. Acquired EBITDA year to date reached roughly $20 million, compared with about $2.6 million at the second-quarter call. That total includes six businesses closed after quarter end that are expected to contribute $13.2 million annually. Seller notes now make up about 33% of purchase consideration, versus a historical 10-20%. Management sounded more confident and specific than it did in August.
The balance sheet was reshaped:
- **Preferred stock:** Teamshares raised $225 million of perpetual preferred and ended September with $267 million in cash.
- **Refinancing:** It retired its $150 million legacy facility using a new $130 million term loan.
- **Debt reduction:** It repaid $27.2 million of debt in the quarter and $16.2 million of 18% mezzanine debt afterward. The company expects these moves to cut annual interest by roughly $11.5 million combined.
- **Leverage:** Management cited a pro forma blended rate of about 10.5%, down from 14.6% at end-2024. It is targeting gross senior leverage of 3-4x by year-end, versus 14x at year-end 2025.
Bears have legitimate ammunition, however. The preferred carries a 16% cash dividend, roughly $36 million a year. That exceeds LTM Pro Forma Adjusted EBITDA of $23.1 million. A payment-in-kind (PIK) option would instead grow the obligation.
Guidance was reaffirmed, not raised. Full-year Pro Forma Adjusted EBITDA of $60 million still assumes $40 million or more of acquired EBITDA. Management explicitly conditions that on timely closing of the LOI pipeline. The signed LOI backlog now stands at more than $20 million, down from about $30 million mostly because deals converted to closings. Much of that must close within weeks. One LOI was already dropped after diligence revealed materially lower numbers. Executive Madhuri Kommareddi will also depart in March 2027. Management referenced a $100 million pro forma EBITDA projection for year-end 2027, which raises the stakes on programmatic execution.
The market setup is harsher than the operating narrative. Investor sentiment collapsed from 0.67 after the August report to -0.18. That shift from clearly positive to modestly negative reflects a genuine reversal in expectations. Shares fell 44% from the $9.34 post-report open to $5.23 ahead of this release. They sit about 54% below the 200-day moving average and touched a 52-week low of $3.89 on October 29. The stock has since rebounded roughly 35% off that low, but it remains far below the $9.79 inter-earnings high. AVWAP readings remain negative, consistent with the damage holders have absorbed since August.
The bottom line is that Teamshares delivered a clear headline miss alongside real progress on the things its model depends on: capital access, lower debt costs, and acquisition closings. Organic growth is modest, GAAP losses widened, and the new preferred is costly relative to current EBITDA. The investment case now hinges on converting the LOI backlog quickly enough to hit the $60 million target and grow into that capital structure. With sentiment and price already badly damaged, year-end closing announcements are likely to matter more than this quarter's numbers.
Read our earnings preview for Teamshares Inc.: https://www.earningswhispers.com/article/TMS/23075
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-09 | |
| Nov-03 | |
| Nov-03 | |
| Oct-29 | |
| Oct-19 | |
| Sep-23 | |
| Sep-02 | |
| Aug-14 | |
| Jul-24 | |
| Jun-30 | |
| Jun-23 |
