Thryv Misses Badly As SaaS EBITDA Guidance Is Cut Again, Overshadowing A $142 Million Print Sale And A Fast Growth Platform Start
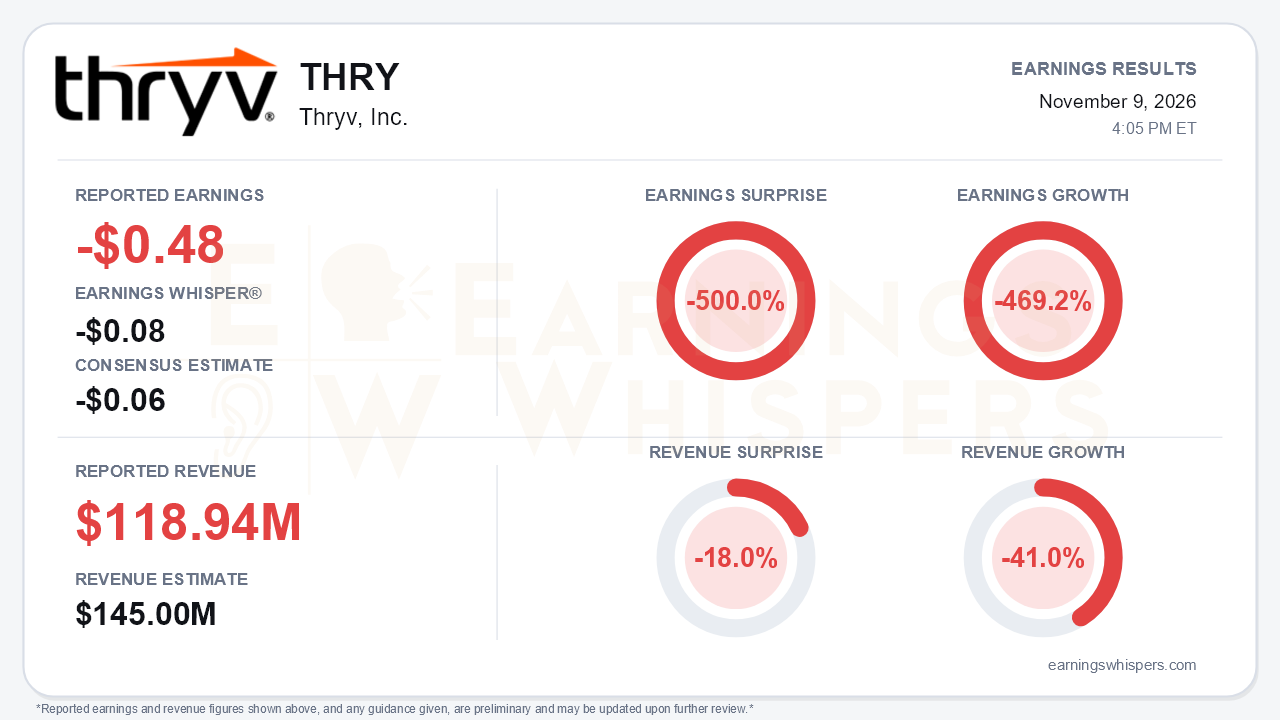
Thryv (NASDAQ: THRY) reported a third-quarter loss of $0.48 per share, far worse than the -$0.06 consensus and the -$0.08 Earnings Whisper number. That is a 500.0% shortfall, and earnings fell 469.2% from a year ago. Revenue of $118.94 million missed the $145.0 million consensus by 18.0%, and the company issued revenue guidance below estimates. The headline miss is partly mechanical, but the more important story is not. For the second straight quarter, management sharply reduced its SaaS profitability outlook. Full-year SaaS adjusted EBITDA guidance is now $16.5 to $17.5 million, down from $42 to $44 million in August and $70 to $75 million at the start of the year. That repeated reset is the central tension of the quarter.
The reported numbers need context. On a GAAP basis, the continuing-operations loss was $2.61 per share, or $116.0 million. That figure includes a $94.8 million non-cash goodwill impairment worth roughly $2.13 per share. Excluding the impairment brings the loss to the normalized $0.48. The revenue comparisons also carry an accounting distortion. Thryv agreed to sell its print directories business and now reports it as discontinued operations. The release shows consolidated continuing-operations revenue down 13.5% from a recast $137.4 million. The 41.0% normalized decline and the consensus figure appear to reflect a pre-recast base that still included print, which explains much of the gap. Even on the cleaner recast basis, though, the trend is negative. SaaS revenue fell 3.3% to $112.0 million, and the remaining Marketing Services revenue collapsed 67.9% to $6.9 million.
The quarter itself was not a disaster against management's own targets. SaaS revenue landed at the top of the $111 to $112 million guide. SaaS adjusted EBITDA of $9.5 million topped the original $8.5 to $9.5 million range and beat the recast like-for-like range of $2.9 to $3.9 million by more than $5 million. SaaS adjusted gross margin recovered to 69.3% from 66.6% in Q2, subscribers rose to 98,000 from 95,000, and quality customers reached 72% of SaaS revenue. Beneath that, however, the growth engine is clearly slowing:
- Growth-product revenue rose 16%, down from 21% in Q2 and 34% in Q4 2025.
- ARPU growth slowed to 2% from 12% and 15% over the same periods.
- Seasoned net revenue retention slipped to 89% from 90% and 94%.
Those are the metrics a SaaS-only story depends on, and every one of them weakened.
Guidance turns the qualitative concern into numbers. Thryv expects Q4 SaaS revenue of $110 to $111 million, roughly 7% below the $119.0 million of a year ago. It also guided Q4 SaaS adjusted EBITDA to a loss of $4.5 to $5.5 million, and management itself called the coming quarter "messy" and "ugly." Some of the pressure is accounting: about 94% of shared costs now fall on the SaaS segment once print moves out. Part is self-inflicted, as Thryv exits CRM, payments, and payroll products to simplify, and engineering cuts shift capitalized R&D into expense. Still, full-year SaaS revenue guidance of $453 to $454 million now sits below 2025's $461 million. The $40 to $50 million free cash flow target set earlier in the year was not reiterated, and year-to-date free cash flow totals just $16 million.
The bull case rests on a few genuine catalysts:
- **Print sale.** The $142 million cash sale to Carolwood carries no earn-out and is expected to close in Q4, with proceeds directed to debt.
- **Balance sheet need.** Leverage climbed to 2.5x from 1.7x at year-end as EBITDA shrank, and cash stood at just $8.8 million against $52.6 million of current debt and ABL borrowings. Net debt did edge down to $236 million.
- **Growth Platform.** The Thryv Growth Platform has sold about 1,500 units since its August launch, roughly 190% of internal plan.
- **Cost savings.** Restructuring savings of about $60 million run-rate are expected to lift margins beginning in early 2027.
The market had already braced for trouble. Shares fell 65.5% from $3.41 at the open after the August report to $1.18 before this release. That left the stock 60.5% below its 200-day moving average of $2.98 and just 7.8% above a fresh 52-week low of $1.09 set on November 6. Investor sentiment deteriorated meaningfully, from -0.20 to -0.53, and the Earnings Whispers trend signals are uniformly negative. Expectations were low, but the second guidance cut gives bears legitimate ammunition.
The bottom line is that Thryv delivered a quarter that met its own recast targets and secured a clean print exit. But it again slashed SaaS profitability guidance while its core growth and retention metrics decelerated. The pure-play SaaS thesis now depends on a promising but very early product launch and on restructuring savings that are not expected until 2027. Until ARPU, retention, and EBITDA stop sliding, the deleveraging story is doing most of the work.
Read our earnings preview for Thryv, Inc.: https://www.earningswhispers.com/article/THRY/22193
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Oct-29 | |
| Oct-28 | |
| Oct-20 | |
| Oct-15 | |
| Sep-29 | |
| Sep-14 | |
| Sep-03 | |
| Aug-25 | |
| Aug-08 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
