Clearway Energy Clears A Low Whisper As GAAP EPS Plunges; 2027 Guidance And A New 2031 Target Shift The Focus To Growth
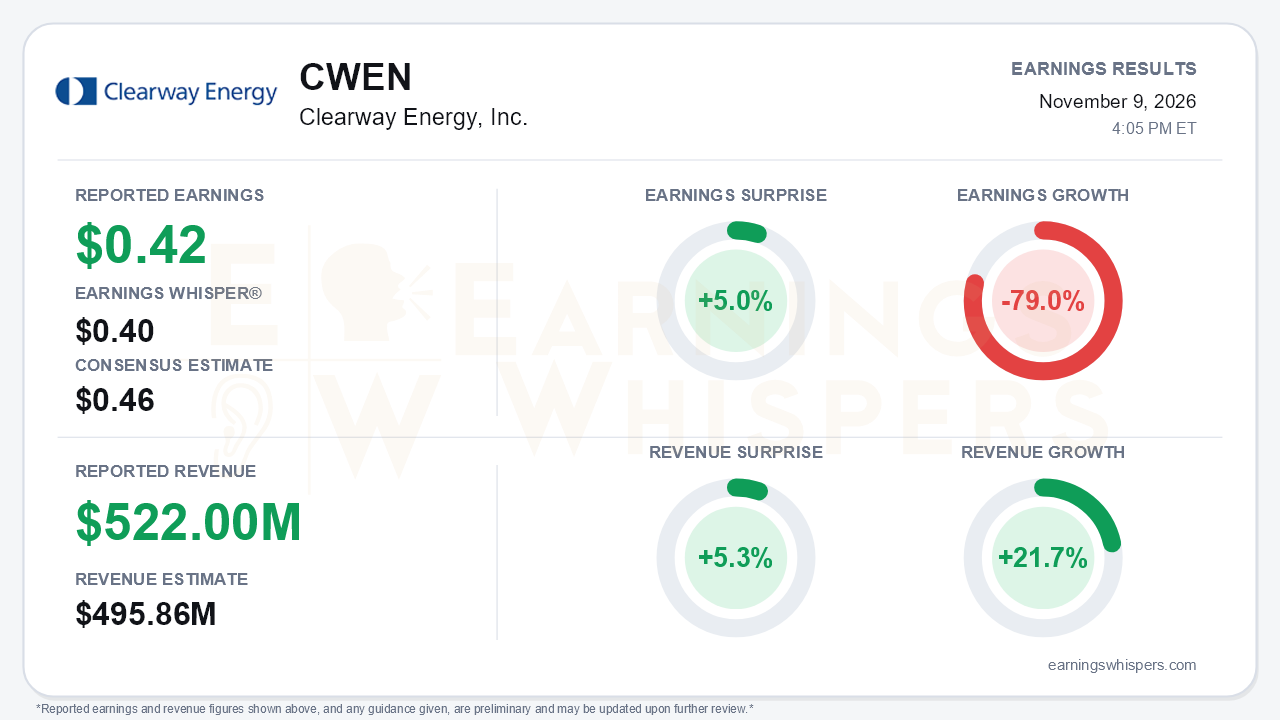
Clearway Energy (NYSE: CWEN) reported third-quarter earnings of $0.42 per share on revenue of $522.0 million. That topped the $0.40 Earnings Whisper number by 5.0%, but it fell short of the $0.46 consensus estimate. The mixed EPS comparison and the 79.0% year-over-year decline both need context. Revenue was cleaner: it beat the $495.86 million consensus by 5.3% and grew 21.7%. The more important story is that management stopped defending a weather-damaged 2026 and started selling a longer, better-funded growth runway. It initiated 2027 CAFD guidance and introduced a 2031 CAFD-per-share target of $3.20 to $3.40.
The quality of the quarter looks better than the EPS decline implies, but it is not as strong as the revenue line suggests. Consolidated net income roughly doubled to $123 million from $60 million. Net income attributable to Clearway shareholders, however, fell to $51 million from $232 million. The reason is the allocation to noncontrolling interests, which swung from a $172 million loss a year ago to $72 million of income. In other words, the prior-year EPS comparison was artificially high, and the collapse in per-share earnings largely reflects partnership accounting rather than operating erosion. GAAP results also benefited from interest-rate swap marks, which helped cut reported interest expense to $43 million from $98 million. On the cash metrics that matter most for a yieldco, Adjusted EBITDA rose 13% to $435 million, driven by growth investments. CAFD, however, rose only to $173 million from $166 million. Cash interest paid jumped to $137 million from $102 million, and principal amortization climbed as well, so much of the EBITDA gain never reached distributable cash. That is the central tension: the asset base is growing quickly, but financing costs are absorbing a meaningful share of the uplift.
Operationally, the quarter was solid. Renewables & Storage generation rose 12%, and solar output increased to 3.4 million MWh from 2.9 million. Flexible Generation availability improved to 93.8%. Sequentially, Adjusted EBITDA and CAFD rose from $409 million and $167 million in the second quarter. The bigger shift was in contracting. Management extended flex-gen tenors from roughly three years to 8-10 years through two deals:
- a Walnut Creek tolling agreement running through 2034 and ramping to 500 MW;
- a 274 MW contract running from 2028 through 2037.
That converts a historically merchant-exposed segment into something closer to contracted infrastructure. Management also committed to the Swan Solar and Honeycomb Phase 2 drop-downs, which are expected to add about $24 million and $12 million of annual CAFD, respectively. It received a Heartland offer at a roughly 10.5% CAFD yield and lifted identified opportunities to 6.4 GW from 4.9 GW.
The guidance picture is constructive but not a clean upgrade. The 2027 CAFD range of $520 million to $590 million has a midpoint equal to about $2.70 per share. That matches, rather than exceeds, a target management has repeated for several quarters, and the range embeds persistent El Niño resource conditions. The 2026 range stays at the $430 million to $470 million level set when it was cut in the second quarter, with no recovery. Bears also have legitimate ammunition elsewhere in the call:
- The co-located digital infrastructure pipeline is now shown at about 12 GW versus 17 GW, a change management described as a reclassification.
- Load service at the Wilcox data center has slipped to 2029-2030 from an earlier 2028 target.
- Equity needs grew by about $300 million for 2030, on top of $500 million to $1 billion over 2026-2029.
- The CFO role changed hands.
- Management fielded questions on tariffs, inverter restrictions, data-center permitting and rising 10-year yields. Higher yields could squeeze the 10-11% drop-down yield spread.
Investor sentiment remained negative heading into the report but improved meaningfully, rising from -0.26 to -0.14. The price action tracks that thaw. Shares hit a 52-week low of $28.57 on October 1, then rallied 19.4% to $34.10. That price is up 4.9% since the open after the August report. The stock entered earnings about 5% below its November 5 inter-earnings high, but it remains 4.1% below its 200-day moving average of $35.58. The positive AVWAP reading reflects that recovery, while price and momentum trends are only neutral. The market has moved from capitulation toward cautious repair, not into outright confidence.
The bottom line is that Clearway's headline EPS is a poor guide to this quarter. Partnership accounting distorted the year-over-year comparison, and the cash results were steady rather than spectacular as higher interest costs absorbed EBITDA growth. What changed is the forward setup. Longer flex-gen contracts, a larger committed pipeline and a 2031 target give the growth story more visible building blocks. Rising capital needs, softer data-center timing and a 2027 outlook that only meets prior commitments keep the stock short of a full rerating case.
Read our earnings preview for Clearway Energy, Inc.: https://www.earningswhispers.com/article/CWEN/22618
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-23 | |
| Oct-20 | |
| Sep-08 | |
| Aug-18 | |
| Aug-05 | |
| Aug-03 | |
| Jul-16 | |
| May-15 | |
| May-07 | |
| Apr-29 | |
| Apr-16 | |
| Apr-15 |
