Vista Gold's 65% Rally Raises The Bar For Mt. Todd Permitting And Cash Discipline
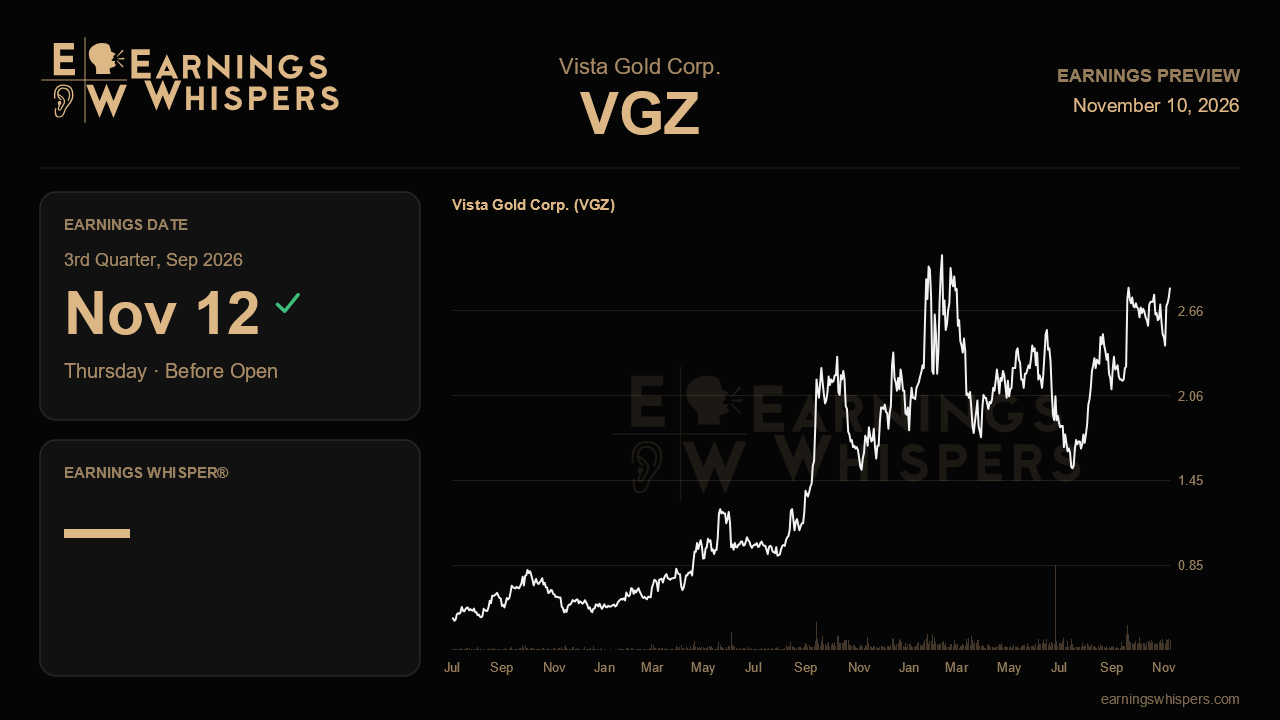
Vista Gold heads into its September-quarter report with its stock up nearly 65% since the last update, a move that has left the S&P 500's 2.3% gain far behind. For a company with no revenue and a steady quarterly loss, that kind of rerating rests almost entirely on confidence that Mt. Todd, the largest known undeveloped gold project in Australia, is moving from study to shovel on schedule. The upcoming release is less about the income statement than about whether the milestones management laid out last quarter are arriving on time and whether the cost of getting there is under control.
There is no meaningful revenue or earnings consensus to anchor the report, which suits a pre-production developer. The useful reference points are historical. Vista lost $0.02 per share last quarter, up from $0.01 in the year-ago period, and net loss for the June quarter widened to $3.0 million from $2.4 million. Management has not issued formal financial guidance. Its operating roadmap has stayed fixed across four consecutive calls: detailed engineering is set to begin in 2027, followed by roughly 27 months of construction and commissioning. Any slippage in that timeline would matter far more than a penny of variance in the loss.
The last call made two things clear. First, the strategy has narrowed. Management stopped presenting a joint venture or corporate transaction as live alternatives and said plainly that it is developing Mt. Todd on its own. Second, de-risking is advancing. Vista received authorization for certain permit modifications and said more approvals should come in the second half of 2026, with final approvals in 2027. The metallurgical program was described as entering its final stages, the west pit wall geotechnical work was nearly done, and the search for an Australia-based managing director was well advanced. This report falls squarely inside that second-half permitting window. Evidence of additional approvals, a completed metallurgical program and a named managing director would confirm that the standalone plan has real momentum. Silence on any of these, or vaguer language than last quarter, would suggest progress is lagging the narrative.
The costs are the counterweight. A wet season roughly 50% above normal left far more water on site than expected. That forced a multi-phase dewatering program at the Batman Pit and tailings facility, which management said would run into later 2026. Pumping drove up power costs, and the Australian team build-out pushed exploration, holding and administrative expenses higher. Cash fell to $49.5 million from $52.7 million in a single quarter after the March raise. The key test is whether holding costs stabilize as dewatering progresses, or whether the burn rate keeps climbing as staffing expands ahead of engineering. A clean, debt-free balance sheet buys time, but a standalone developer eventually needs a credible funding path, and the pace of cash consumption shapes how much leverage Vista will have in those talks.
Sentiment has barely shifted. Roughly two-thirds of readings lean bearish, essentially unchanged from before the prior report, even as the shares surged. That gap suggests the rally reflects gold-price enthusiasm and the project's leverage to it more than broad conviction in execution. At $2.82, the stock sits well above its 200-day moving average of $2.28 and within about 2.5% of its post-earnings high of $2.89, so it is testing a breakout. It has also left behind last quarter's $1.49 to $2.66 range. The rally narrows the gap between share price and management's $14.89 per-share NAV estimate, which leans heavily on elevated gold assumptions in a market management itself called volatile.
Ultimately, this report has to show that Mt. Todd's de-risking is outrunning its costs. Fresh permits, a finished metallurgical program and a leadership hire alongside stabilizing water and power spending would justify the stock's run. More delays and a faster cash burn would leave a sharply rerated stock leaning on the gold price alone.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 9 hours | |
| Nov-09 | |
| Sep-22 | |
| Sep-21 | |
| Aug-17 | |
| Jul-31 | |
| Jul-29 | |
| Jul-29 | |
| Jun-10 | |
| Jun-08 | |
| May-13 | |
| May-03 | |
| Apr-30 | |
| Apr-30 | |
| Apr-28 |
