Vista Gold's Wider Loss Takes A Back Seat To The Artemis Sale, Which Caps Mt Todd Upside Well Below Management's Old NAV
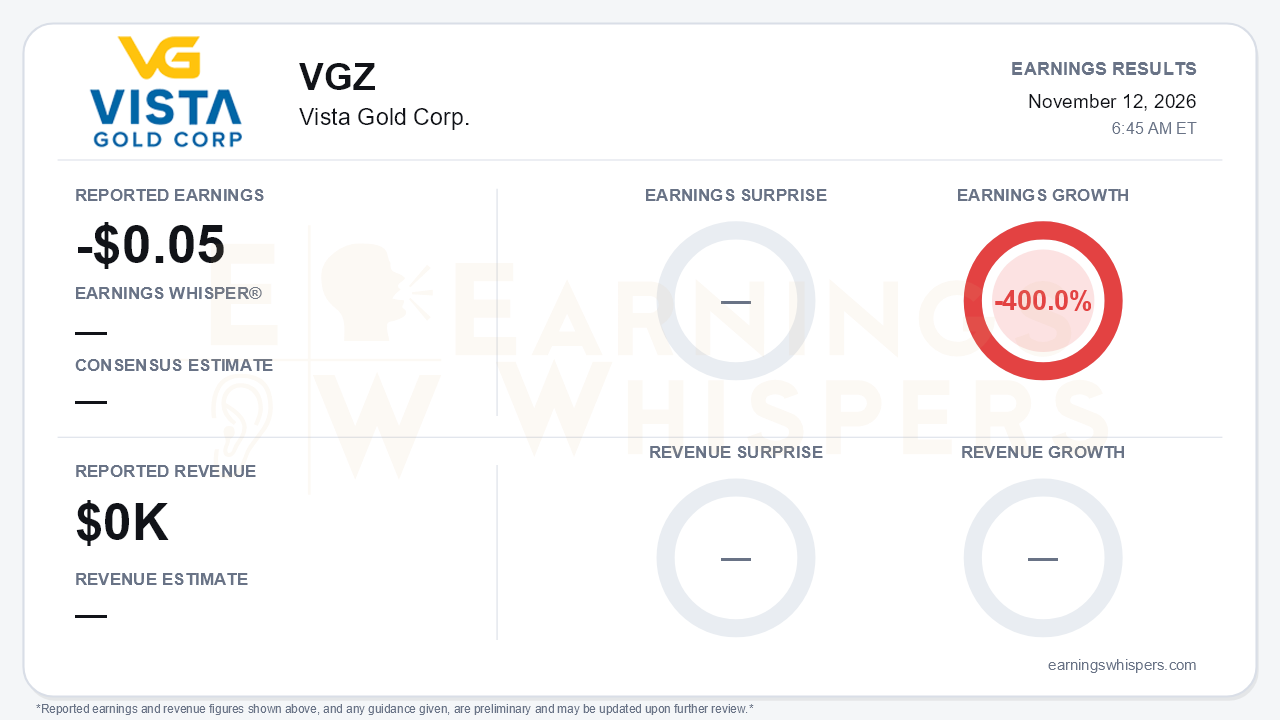
Vista Gold's third-quarter loss of $0.05 per share was five times the $0.01 loss a year earlier, an earnings decline of 400.0% year over year. There was no revenue and no consensus estimate to measure against. The numbers matter less than what happened during the quarter. On September 20, Vista agreed to be acquired by Artemis Gold for 0.0966 Artemis shares per Vista share, roughly $2.83 per share or about $427 million in equity value at announcement. That turned a development-execution story into a deal-completion story. That is the central tension of the report: the company kept de-risking Mt Todd while effectively selling that progress at a price far below the value management promoted only one quarter earlier.
The wider loss is mostly a deal artifact, but it still costs cash. Net loss rose to $6.4 million from $3.0 million in the second quarter and $3.1 million in the first. Corporate administration jumped to $4.2 million from $0.85 million in Q2, and $3.2 million of that was arrangement costs. Exploration, property and holding costs were flat at $2.5 million, reflecting the build-out of the Australian team and heavier water-management spending. Interest income of $434,000, up from $134,000 a year ago, offset only a small part of the increase. Cash fell to $43.5 million from $49.5 million at the end of Q2 and $52.7 million at the end of Q1. Working capital was $40.1 million and the company has no debt. The balance sheet is far stronger than the $13.6 million Vista held at the end of 2025, but that improvement came from the roughly $44.85 million March equity raise, not from operations.
On the ground, the quarter delivered real permitting progress:
- A waste discharge permit was authorized in September, allowing treated water to be discharged from the Batman pit.
- Management expects approval of an environmental mining license variation later in November, with conversion to an operations license to follow.
- Four high-efficiency evaporators, adding about 1.2 GL per year of capacity, are due in early December, and four more are under consideration. They are needed because the pit holds about 6.7 GL of water after a record wet season.
- Final metallurgical results are expected later in the fourth quarter and geotechnical results in December.
- A managing director and a financial controller were added in Australia.
The problem is that the standalone path has been shelved. Management had repeated the same plan on the prior three calls: detailed engineering in 2027 followed by a roughly 27-month build. Under the transaction covenants, site-layout refinements, execution planning, and the EIS, EPBC and operations license amendment filings are now on hold.
The swing in management's tone is the most telling change. On the second-quarter call, management cited a feasibility NAV of $14.89 per share at $3,300 gold and described it as about nine times the share price. This quarter, management was defending a sale at roughly one-fifth of that figure. Management's case rests on three points:
- a 25% premium to the September 18 close and 29% to the 20-day VWAP;
- exposure to Artemis's Blackwater expansion;
- a well-capitalized owner that intends to evaluate Mt Todd at 50,000 tonnes per day, versus Vista's 15,000-tonne-per-day feasibility case.
That is a coherent argument. Still, bears have legitimate ammunition. One investor on the call criticized the price as a deep discount to project NPV, particularly after shareholders funded the March raise. Holders will end up owning only about 5% of Artemis, so most of any 50,000-tonne-per-day upside will accrue to Artemis's existing shareholders.
Completion risk is now the key variable:
- The deal needs approval from two-thirds of votes cast, plus FIRB, Northern Territory Ministerial Consent and TSX-V approval.
- The special meeting is expected in January 2027, with closing targeted for the first quarter.
- Because the exchange ratio is fixed, the value Vista holders receive will move with Artemis shares and the gold price.
- Denver management is not expected to continue after closing.
- If the deal fails, Vista returns to a standalone plan that has been paused for months, with a smaller cash cushion and transaction costs already spent.
The stock has traded like a deal stock. Shares are up 59.6% from the $1.71 open after the July report to $2.73. They peaked at $2.89 on September 22, just after the announcement, and now sit 5.5% below that high, 64.0% above the July 31 low, and about 19.6% above the 200-day moving average. That price leaves shares modestly below the roughly $2.83 implied at announcement, consistent with the market pricing in some combination of completion risk and Artemis share-price exposure. Price and AVWAP trends are positive, but they largely reflect the premium being absorbed. Investor sentiment stayed firmly negative and was essentially unchanged, moving from -0.643 to -0.654. The takeover premium has not converted skeptical holders, which fits the valuation pushback heard on the call.
The bottom line is that Vista's quarterly loss is noise. The real event is that Mt Todd's long-promised standalone value has been exchanged for a modest premium and a small slice of Artemis. Permitting and water-management progress make the asset more valuable to its next owner. For current holders, the investment question has narrowed to whether the deal closes on schedule, how Artemis shares perform until then, and whether shareholders accept a price far below the NAV management itself championed.
Read our earnings preview for Vista Gold Corp.: https://www.earningswhispers.com/article/VGZ/23082
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-09 | |
| Sep-22 | |
| Sep-21 | |
| Aug-17 | |
| Jul-31 | |
| Jul-29 | |
| Jul-29 | |
| Jun-10 | |
| Jun-08 | |
| May-13 | |
| May-03 |
