QXO Faces A Scale Test As Street Expects A 78% Revenue Surge But Thinner Per-Share Earnings
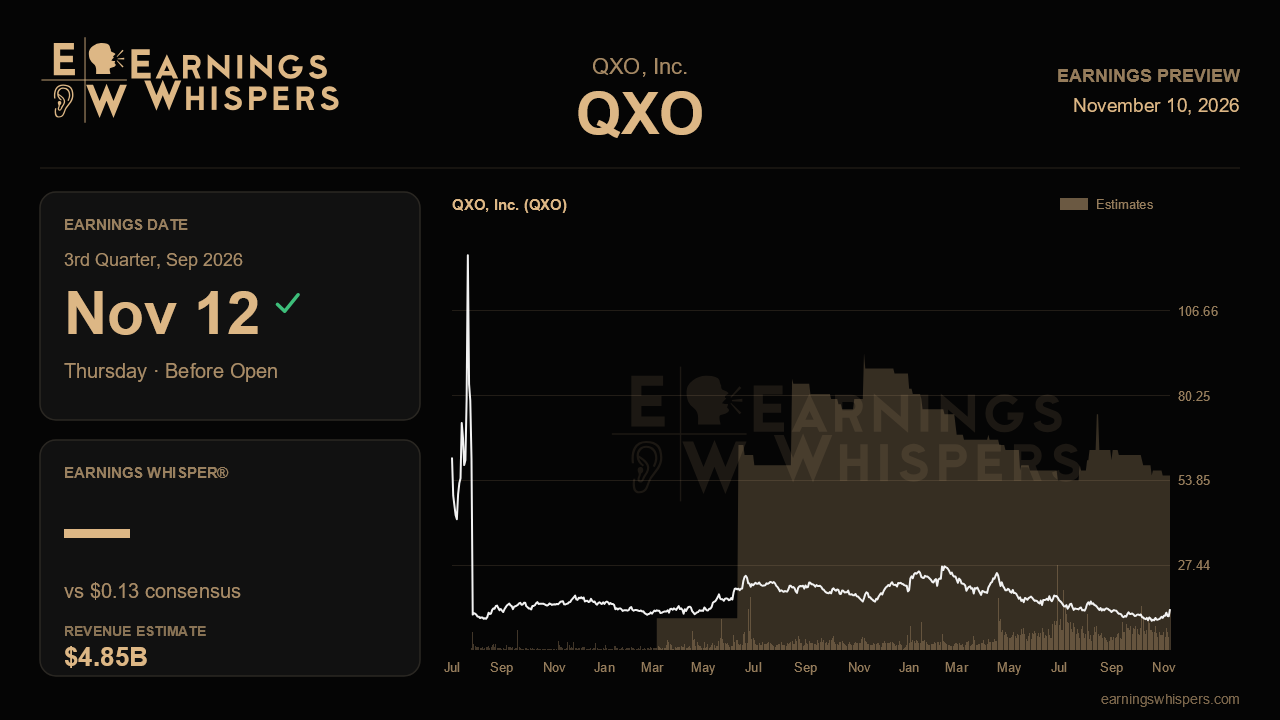
QXO heads into its September-quarter report with a revenue figure that is set to jump and an earnings line that is not. Wall Street expects sales of about $4.85 billion, up roughly 78% from a year ago, yet consensus calls for earnings of just $0.13 a share, slightly below the $0.14 earned in the same period last year. That gap between top-line growth and bottom-line output is the story. A company that has nearly doubled its revenue base has yet to show that the extra dollars translate into extra profit for each shareholder, and this report is the next chance to prove it can.
The sequential math is equally striking. Last quarter QXO posted $3.25 billion in revenue and $0.08 in earnings per share. The consensus now implies roughly 49% more revenue in a single quarter and a per-share profit improvement of about 60%. A move of that size over three months points to a business whose footprint has expanded dramatically rather than one simply riding a seasonal upswing in building products demand. That makes the quality of the revenue as important as the quantity. The release should show whether the larger operation is being run with the gross margin discipline and cost control that justify its new scale, or whether integration costs, interest expense and a heavier share count are absorbing most of the gains.
Without a fresh management outlook to anchor the numbers, the Street is effectively setting the bar on its own, which leaves more room for interpretation on the day. Three things would validate the bullish case. First, revenue landing at or above $4.85 billion would confirm that the expanded business is performing at the expected run rate in a quarter that typically benefits from late-season construction and repair activity. Second, any evidence of improving operating margins, whether through purchasing leverage, branch productivity or overhead reductions, would suggest the earnings line can eventually catch up to sales. Third, commentary on cash generation and debt reduction would help investors judge how quickly per-share earnings can recover toward and beyond year-ago levels. The opposite outcomes, a revenue shortfall, flat margins, or rising one-time charges, would challenge the idea that bigger is automatically better here.
Sentiment has warmed modestly even as the stock has struggled. Earnings Whispers readings sit at 12.9% bearish, a clear improvement from 28.4% bearish ahead of the prior report, which suggests investors are less pessimistic than they were three months ago, though still not bullish. The share price tells a harsher story. QXO has fallen 9.9% since its last report, trailing the S&P 500 by 6.6 percentage points. At $13.78, the stock trades well below its 200-day moving average of $16.96, and its post-earnings range of $10.04 to $16.17 sits noticeably lower than the prior quarter's $13.18 to $18.60 band. Shares have rebounded meaningfully from the recent low but remain well short of challenging the top of the range, so there is no breakout setup here, only a recovery that still needs confirmation.
That combination of softer bearishness and a damaged chart creates an interesting asymmetry. Expectations embedded in the price appear subdued, so a clean quarter with visible margin progress could be rewarded. But the stock's underperformance also signals that patience with the integration story is thinning, and a miss on earnings despite strong revenue would reinforce the worry that growth is coming at the expense of profitability.
Ultimately, the November 12 report hinges on one question: can QXO show that its much larger revenue base is starting to produce proportionally larger earnings? Hitting the sales number is necessary but not sufficient. Investors need to see a credible path from a near-doubling of revenue to per-share profit growth, and the margin and cash flow details in this release will determine whether that narrative strengthens or slips further.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 11 hours | |
| Nov-11 | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Oct-23 | |
| Oct-08 | |
| Oct-07 | |
| Oct-07 | |
| Oct-06 | |
| Sep-22 | |
| Sep-21 | |
| Aug-24 |
