Duos Technologies Must Prove Its AI Data Center Pivot Is Producing Revenue After Stock Halves
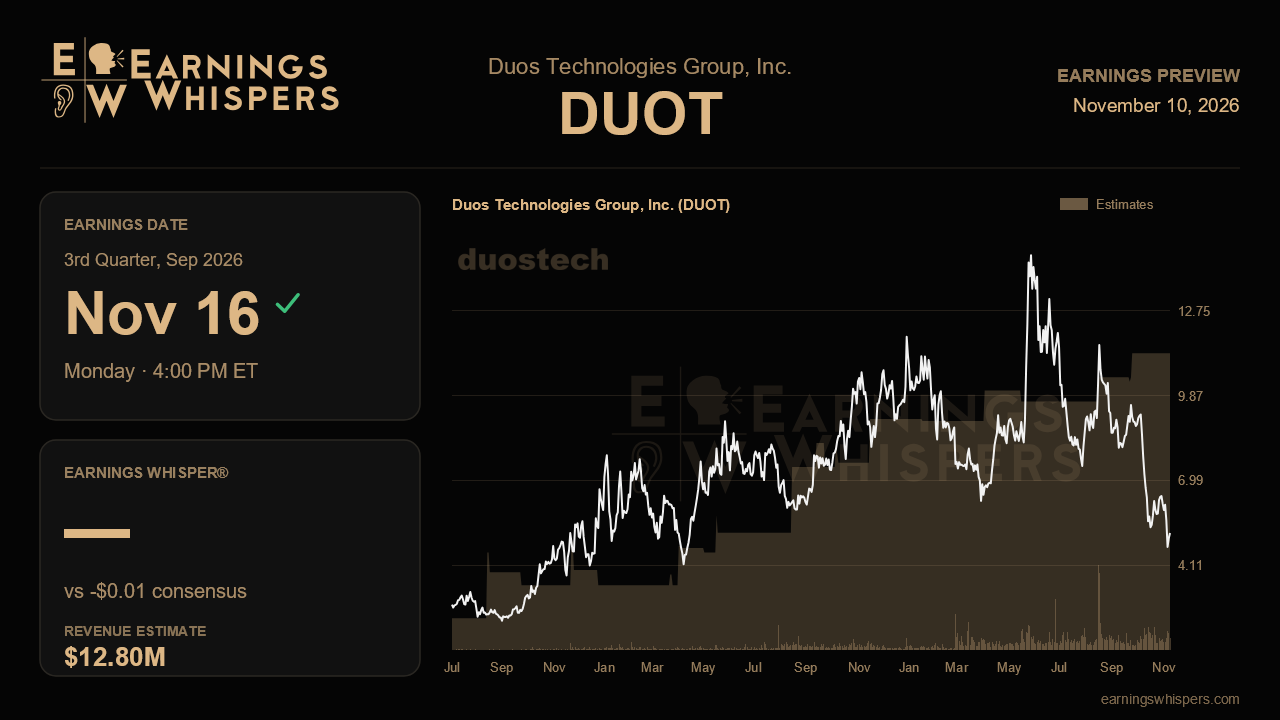
Three months ago, Duos Technologies told investors its transformation from a rail-inspection vendor into an AI-infrastructure operator was essentially finished and fully funded. The market has since cut the stock by more than half. When the company reports third-quarter results after the close on November 16, the question is no longer whether the pivot makes strategic sense. It is whether contracted megawatts are starting to turn into recognized revenue fast enough to support management's back-half targets.
Wall Street expects a loss of about a penny per share on revenue of roughly $12.8 million. That would be an 86% jump from the $6.9 million posted a year ago and more than double the $6.2 million reported last quarter, with the loss narrowing from six cents a share. For a company whose first-half revenue actually slipped as legacy AMA pass-through work wound down, that is a sharp step change. It is also the first quarter in which the new business, rather than the old one, has to carry the top line.
The full-year math explains why this quarter matters. Management reaffirmed that 2026 revenue should exceed $50 million, and the Street sits at $55.5 million, comfortably above the floor. With only about $8.3 million booked in the first half, even hitting consensus this quarter leaves the company needing close to $30 million in the fourth quarter just to clear guidance, and more to reach the Street's number. Management has pointed to fourth-quarter recurring infrastructure revenue of $17 million to $18 million, implying an exit run rate above $70 million at margins over 70%, plus adjusted EBITDA of $8 million to $10 million. That leaves the plan heavily weighted to the final months of the year, so any sign that GPU energization or colocation start dates have slipped would ripple directly into the annual target and the newly introduced 2027 framework of at least $160 million.
Several pieces of evidence would validate last quarter's confidence. Investors should want concrete progress on the Columbus, Georgia facility and its 2,304 NVIDIA B300 GPUs, along with timing on the 55-megawatt Axe Compute expansion that carries more than $500 million in base payments over five years. Gross margin, which reached 55.8% last quarter as low-margin AMA revenue rolled off, should hold or improve as higher-value infrastructure revenue grows. Adjusted EBITDA, which turned modestly positive a quarter early, ideally stays in the black despite operating expenses that have been climbing with hiring and public-company costs. An update on the Technology Solutions backlog, which rose to $25 million, and on the Axe joint venture's up to $140 million equity commitment, still subject to approvals and financing, would also matter. Note that the rail divestiture closed in August, so GAAP figures may carry noise from one-time items, making operating metrics the cleaner read.
What would challenge the story is equally clear: a revenue shortfall that pushes more of the year into the fourth quarter, any softening of the fourth-quarter run-rate language, delays in the planned GPU senior debt financing, or new wrinkles around the Axe JV. Customer concentration in Axe and Hydrohost means a single counterparty hiccup carries outsized weight, and an ongoing CFO transition adds to the scrutiny on execution.
Sentiment has swung from mildly bullish heading into the last report to distinctly bearish now, and the price action matches. At $5.20, shares sit far below the 200-day average of $8.87 and near the $4.66 low of the post-earnings range, a long way from the $12.83 high. That setup lowers the bar for relief if deployments are on schedule, but it also signals deep skepticism. Ultimately, this report hinges on whether Duos can show that its contracted backlog is converting into recurring revenue on the timeline management promised, keeping the $70 million exit run rate credible.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 10 hours | |
| Nov-09 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-05 | |
| Sep-01 | |
| Aug-26 | |
| Aug-20 | |
| Aug-18 | |
| Aug-18 | |
| Aug-17 | |
| Aug-17 | |
| Aug-17 | |
| Aug-14 |
