Duos Misses Badly And Retreats On Profit Targets, Overshadowing A $400 Million Cloud Contract
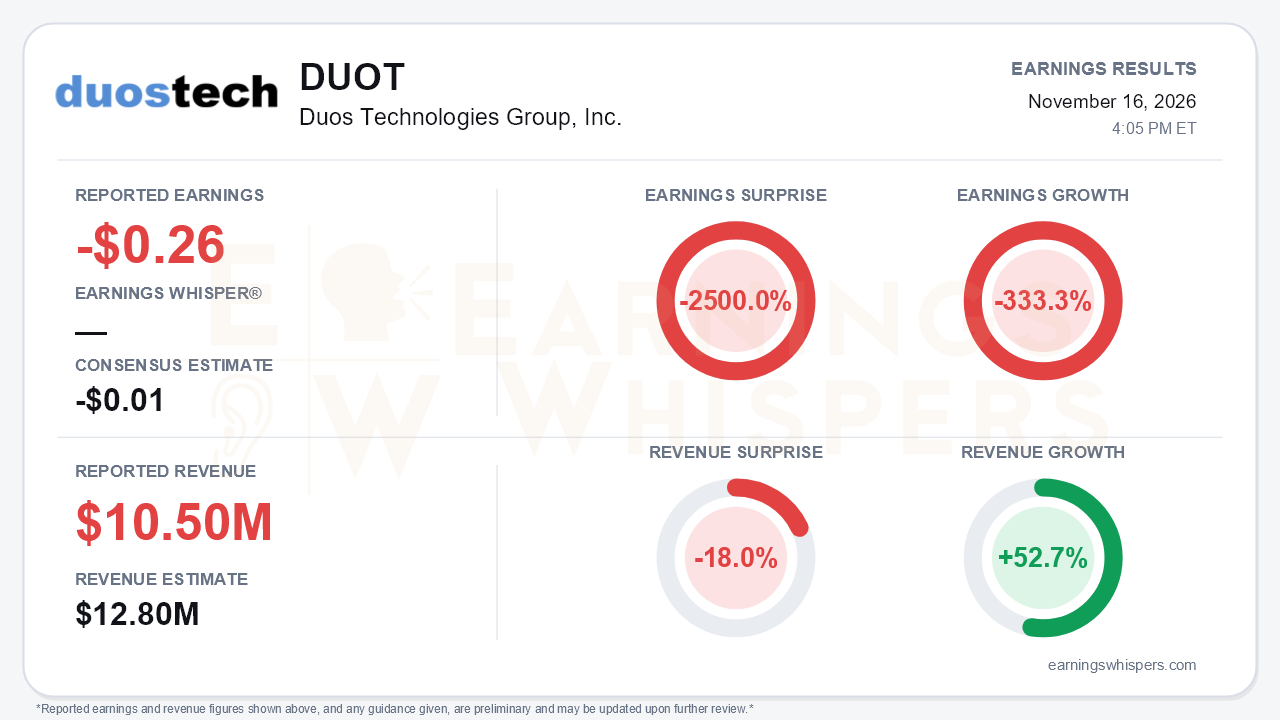
Duos Technologies (NASDAQ: DUOT) reported a third-quarter loss of $0.26 per share, far below the consensus estimate of a $0.01 loss. That is a 2,500.0% negative surprise, and earnings fell 333.3% from a year ago. Revenue of $10.5 million missed the $12.8 million consensus by 18.0%, although it grew 52.7% year over year on Earnings Whispers' normalized basis. The company's release cites 103% growth, so investors will see two very different growth figures depending on the source. The central tension is that Duos delivered its biggest commercial win to date while quietly lowering the economics and profitability path behind its new strategy. It signed a 10-year, 20 MW colocation agreement with a publicly traded cloud provider, worth more than $400 million.
The headline loss needs context. The -$0.26 is the per-share loss from continuing operations, and an $8.67 million income tax charge drove most of it. Including $10.0 million of income from discontinued operations, GAAP net income was $864 thousand, or $0.02 per share. Even the pretax line flatters the core business. The $0.49 million pretax loss relied on a $4.70 million gain from deconsolidating the GPU-as-a-Service unit, which more than offset a $2.82 million loss on debt extinguishment. At the operating level, the loss widened to $1.86 million from $0.89 million. Operating expenses jumped 140% to $6.22 million, including $2.30 million of stock-based compensation, while gross profit rose only $2.66 million. Adjusted EBITDA was a slim $493 thousand, essentially flat with the second quarter.
Beneath the surface, the revenue mix explains the margin story. Revenue is clearly accelerating, rising from $2.7 million in Q1 to $6.18 million in Q2 and $10.5 million in Q3. Technology Solutions reached $6.8 million and is now the largest line. But that hardware sourcing and integration business earns roughly a 15% gross margin. Gross margin compressed to 41.6% from 55.8% in Q2 and roughly 59% in Q1. Hosting and colocation, the business Duos says it is becoming, contributed just $49 thousand of revenue. The quarter's growth came from the lower-quality line, not the recurring infrastructure model the company is promoting.
The call did more damage than the numbers. On the Q2 call, management had guided Q4 adjusted EBITDA to $8 to $10 million. That target was replaced with only "positive adjusted EBITDA for full year 2026," because GPU rent now runs through cost of revenue. Several other commitments also slipped:
- **2027 EBITDA guidance**, promised for this call, was deferred.
- **Site payback** was restated from under three years to just under five.
- **All-in capex** is now about $6.5 million per megawatt, versus "under $6 million" in Q2.
- **The 10 MW Georgia project** slipped to Q2 2027 because of Georgia Power delivery timing.
- **The Axe expansion** of 55 MW is still searching for sites.
- **The 25 MW 2026 deployment goal and the >$70 million ARR exit-rate target** were not repeated.
The tone shifted from Q2's exuberance to a sober re-baselining. On the positive side, the FY26 revenue outlook of more than $50 million was reaffirmed, Q4 revenue was guided to at least $30 million, and the FY27 $160 million framework was reaffirmed. Revenue per billable megawatt was raised to $2 to $2.5 million, with power passed through to customers.
The forward story is credible but capital-hungry. The cloud contract doubles contract length relative to the five-year Axe deals. Columbus went from acquisition to full operation in about 75 days, and roughly 25 MW of a 100 MW powered-land pipeline is under contract. The GPU unit sale removed about $87.8 million of prospective debt. The balance sheet tells the other side:
- **Cash** fell to $44.8 million from $112.3 million in Q2, after nine-month property and equipment purchases of nearly $110 million.
- **Funding needs** for the next 75 to 100 MW are estimated at $480 to $650 million, with financing not finalized and equity not ruled out.
- **Dilution** is already real: shares outstanding rose to 32.6 million from 20.4 million at year-end.
- **The $42.9 million Axe receivable**, paid in $715 thousand monthly installments through September 2027, adds counterparty exposure.
- **Community pushback** against data centers is a live issue, with one large Ohio site still awaiting local buy-in.
The market had largely priced in disappointment before the report. Shares fell 56.4% from the $11.52 opening price after the prior report to $5.03. That leaves them 42.6% below the 200-day moving average and 60.8% below the inter-earnings high of $12.83, set the day after the August report. The stock is just 7.9% above the 52-week low of $4.66 set on November 5. Investor sentiment swung from mildly positive (0.12) to clearly negative (-0.32), a meaningful shift. The Earnings Whispers trend signals are mixed: sequential growth and momentum readings are positive, while price and AVWAP trends remain negative.
The bottom line is that Duos has a bigger customer, a longer contract, and a clearer strategy than it did three months ago, but a weaker profit outlook. Management lowered EBITDA expectations, lengthened payback assumptions, raised capex estimates, and pushed out timelines, all while cash was being consumed and a large financing need remains unresolved. Bulls can point to the $400 million contract and a Q4 revenue ramp. Bears have legitimate ammunition in the margin compression, the guidance walk-back, and dilution risk. Until Duos secures non-dilutive financing and shows colocation revenue actually scaling, the stock's depressed position looks more like a credibility discount than a mispricing.
Read our earnings preview for Duos Technologies Group, Inc.: https://www.earningswhispers.com/article/DUOT/23090
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-16 | |
| Nov-16 | |
| Nov-10 | |
| Nov-09 | |
| Oct-20 | |
| Oct-20 | |
| Oct-16 | |
| Oct-05 | |
| Sep-01 | |
| Aug-26 | |
| Aug-20 | |
| Aug-18 | |
| Aug-18 | |
| Aug-17 | |
| Aug-17 |
