Chicago Atlantic (REFI) Misses As Koach Income Props Up Dividend Coverage While Liquidity, Yield And Merger Timing Slip
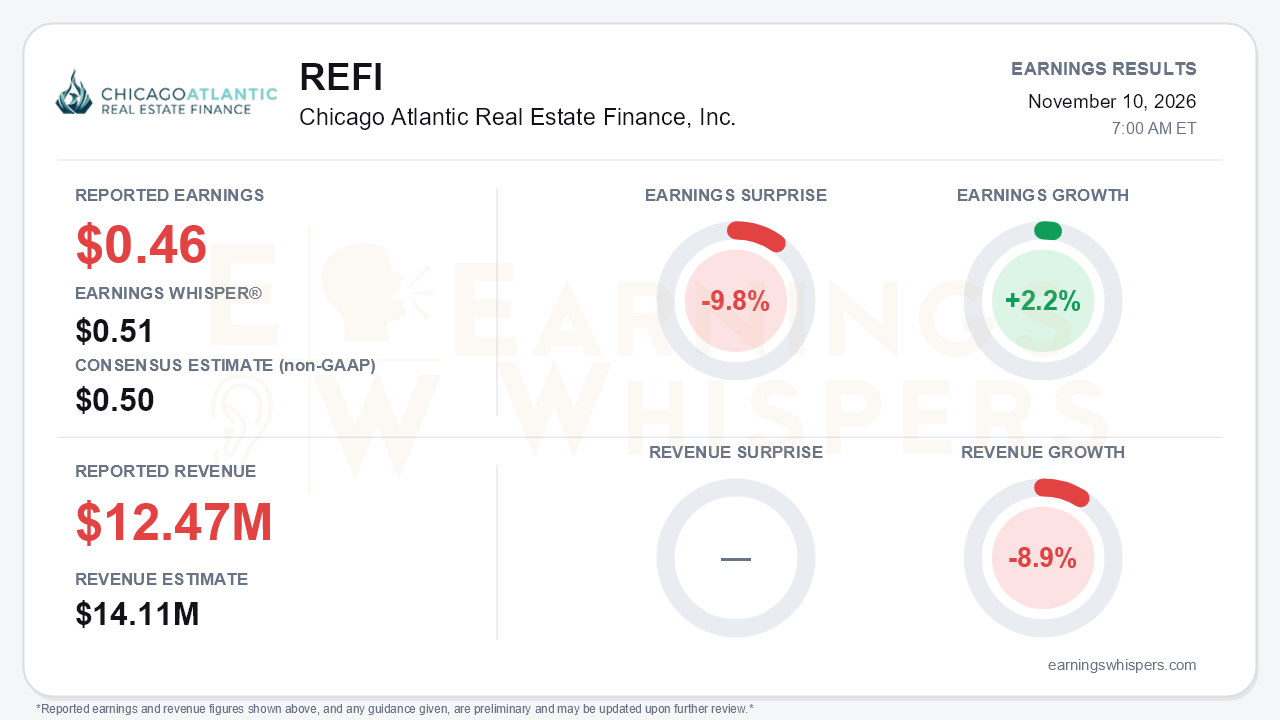
Chicago Atlantic Real Estate Finance posted third-quarter earnings of $0.46 per share, short of the $0.50 consensus and the $0.51 Earnings Whisper number, a 9.8% miss. Revenue of $12.47 million missed the $14.11 million consensus by 11.6%. Earnings grew 2.2% from a year ago, while revenue fell 8.9%. The company's own figure was better: it reported distributable earnings of $0.49 per diluted share, up from $0.43 in the second quarter. That covered the $0.47 regular dividend for the 18th consecutive quarter. The central tension is that the recovery depends heavily on a new, unconventional asset, while the core lending book is shrinking in yield, running short of funding and waiting on a merger that keeps getting pushed out.
The quality of the quarter deserves scrutiny. GAAP net income fell to $0.25 per share from $0.34 in the second quarter and $0.42 a year ago. The drop came largely from a $2.8 million credit-loss provision. Net interest income also declined, to $12.5 million from $12.8 million sequentially and $13.7 million a year earlier. Interest expense nearly doubled year over year as borrowings on the revolver rose to $94.4 million from $49.1 million at year-end.
The lift in distributable earnings came from a newly added adjustment of $2.6 million, roughly $0.10 per share. It reflects income on the Koach Notes. These are second-lien notes REFI received in July in exchange for 4.3 million new shares. Because the notes were issued for stock, GAAP records their income directly in equity rather than in net income. Management argues the income belongs in distributable earnings because it counts as REIT taxable income and the Koach shares collect dividends. That is a defensible argument, but investors should recognize that the sequential improvement is largely definitional and tied to one counterparty. Even with it, year-to-date diluted distributable earnings of $1.38 trail the $1.41 in dividends declared.
The call added both supporting and troubling detail. On the positive side, the Koach notes earned more than 18% annualized in the quarter, helped by about $0.9 million in fees from the first repayment on a Florida property sale. Management sees more opportunities to rotate into similar property-backed deals. Total principal, including Koach, climbed to $527.7 million from $453 million in the second quarter and $414 million in the first, and originations reached $85.1 million. Non-accruals fell to 3.1% of the portfolio, down from 11.1% at the end of 2025, although the dollar amount was unchanged. About 57% of the book carries variable rates, and the September Fed hike is worth roughly 1.5 cents of quarterly distributable earnings for each 25 basis points.
The weaker side of the story is harder to dismiss:
- The weighted average yield compressed to 14.8% from 15.8%.
- The credit-loss reserve rose to 2.9% of loans from 2.3%.
- Adjusted book value slipped again, to $14.12.
- Net liquidity has fallen to about $12 million from roughly $54 million in the first quarter, so management expects originations to slow in the fourth quarter.
- The cannabis pipeline secured by real estate shrank from $204 million to $174 million.
- Expected timing for the LIEN merger has moved from the fourth quarter of 2026, to late 2026 or early 2027, to simply "2027," and the deal remains under SEC review.
The Koach share issuance will also feed into the merger exchange ratio. The 50.5% pro forma ownership estimate for REFI holders is therefore stale.
Management's tone shifted toward defending the stock's de-rating alongside mortgage REITs. The broad regulatory optimism of the second quarter gave way to a narrower upside tied to elections in Pennsylvania, Texas and Georgia, which could expand medical or adult-use cannabis markets.
The market has been punishing the setup. Shares are down 12.4% since the open after the August report, at $8.86. That is 19.7% below the 200-day moving average and 21.8% below the September 18 high of $11.33. The stock set a 52-week low of $8.59 on November 3, just ahead of the report. Investor sentiment remains negative but improved meaningfully, to -0.33 from -0.79, suggesting expectations had already been heavily marked down. The Earnings Whispers price and AVWAP trend readings remain negative.
The bottom line is that REFI produced dividend coverage on the company's preferred measure but missed on the normalized figures, and the coverage leans on Koach income that GAAP keeps out of net income. Credit trends are stabilizing and higher rates help. However, falling yields, depleted liquidity, slower expected originations and a merger with a moving finish line give bears legitimate ammunition. Until the deal timing firms up or funding capacity is restored, the deeply discounted share price looks less like a mispricing than a reflection of real uncertainty.
Read our earnings preview for Chicago Atlantic Real Estate Finance, Inc.: https://www.earningswhispers.com/article/REFI/22707
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 15 hours | |
| Nov-03 | |
| Oct-20 | |
| Oct-16 | |
| Sep-16 | |
| Aug-13 | |
| Aug-11 | |
| Aug-11 | |
| Aug-10 | |
| Aug-04 | |
| Jul-21 | |
| Jul-13 | |
| Jun-25 | |
| Jun-17 |
