Octave Specialty Group Beats On A Narrower Loss, But Slowing Organic Growth Is The Number To Watch
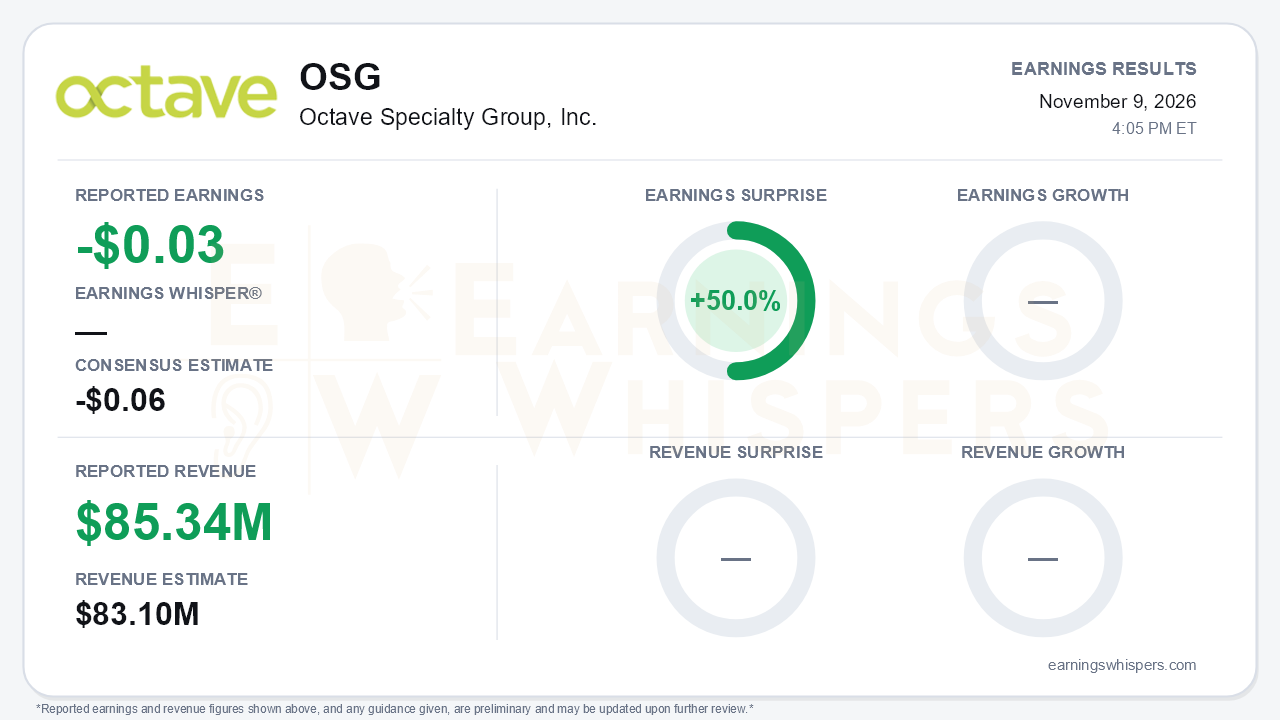
Octave Specialty Group (NYSE: OSG) reported an adjusted loss of $0.03 per share for the third quarter, half the $0.06 loss consensus expected, a 50.0% earnings surprise. Revenue of $85.34 million beat the $83.1 million estimate by 2.7% and rose 28% from a year ago. The adjusted loss also narrowed sharply from $0.21 a year earlier. On a GAAP basis, the loss from continuing operations improved to $0.31 per share from $0.65. Management signaled it will beat several full-year targets. That is the good news. The central tension is that organic growth in Insurance Distribution, the core of the bull thesis, slowed to 23% from 44% in the second quarter and 42% in the first, and fourth-quarter guidance calls only for 'double-digit' growth.
The quality of the improvement deserves scrutiny. Much of it came from cost structure and capital structure rather than revenue momentum:
- Interest expense fell to $2.7 million from $6.2 million.
- The Corporate net loss shrank to $10.8 million from $26.3 million, partly because last year's $8.9 million severance charge did not recur.
- Adjusted corporate expenses of $7.3 million were down more than 20%.
Within Insurance Distribution, the 35% revenue increase included $7.2 million of acquired ArmadaCare revenue. Profit and contingent commissions rose to $4.8 million from $1.9 million. Adjusted EBITDA to shareholders rose 39% to $8.3 million. However, the segment margin of 14.2% barely improved on the year-ago 13.9% and fell from 16.8% in the second quarter. Management attributed the decline partly to seasonality and a roughly $1.2 million drag from de novo operations. The segment still posted a $4.2 million net loss to shareholders after intangible amortization and minority interests.
Everspan, the insurance carrier, was the cleaner story. Net income was $1.3 million, compared with a small loss a year ago, and adjusted EBITDA reached $2.2 million. The combined ratio improved to 100.6% from 112.9%. The loss ratio fell to 57.1% from 84.5%, and the accident-year loss ratio improved 680 basis points to 54.5%. The offset is the expense ratio, which jumped to 43.5% from 28.4% on higher acquisition costs and legal costs tied to the sale of Providence Washington Insurance Company (PWIC). Gross premiums written rose just 2%, and management conceded full-year premiums may fall slightly short of its $410 million target. Commercial auto adverse development and social inflation remain live issues.
Guidance is where the call earned credit. Formal targets were left unchanged, but management now expects to:
- exceed its $45 million Insurance Distribution adjusted EBITDA target, with $43 million already earned year to date;
- comfortably top its 25%-plus organic growth target, with roughly 35% achieved so far;
- meet or beat the $6 million Everspan EBITDA target;
- land adjusted EPS in line with or above the $0.15–$0.20 range.
Investors should remember that the EPS range was cut from $0.50 last quarter, so 'beating' it resets a lowered bar. Forward catalysts are tangible:
- The PWIC sale is expected to bring a roughly $4 million gain and an $11 million boost to Everspan's tangible book value in early 2027.
- Net leverage has dropped below 3x.
- 2027 underwriting capacity is expected to be oversubscribed.
- ArmadaCare enters the organic growth base in the fourth quarter, which management expects to lift reported organic growth meaningfully by the first quarter of 2027.
Against that, the P&C market has seen a ninth straight quarter of commercial rate declines, with property down about 10%. CEO Claude LeBlanc expects market softening to continue into 2027. Bears also have the market concern that AI could disintermediate insurance distribution.
Investor sentiment improved substantially heading into the report, rising from -0.55 to -0.19. It remains negative but is far less pessimistic. The stock has done little to reflect the operational progress. At $5.27, shares are up only 3.1% from the $5.11 open after the August report and sit just 1.6% above the 200-day moving average of $5.19. Momentum and AVWAP trend readings have turned positive, while sequential growth is neutral. That mix suggests the market has stopped selling but has not yet committed to the recovery story.
The bottom line is that Octave delivered a credible beat-and-raise-in-spirit quarter, driven by lower interest costs, leaner corporate overhead and a markedly better Everspan loss ratio. The headline masks a sharp deceleration in organic distribution growth and a softening P&C pricing backdrop that management itself expects to persist. Whether ArmadaCare's entry into the organic base and strong 2027 capacity can re-accelerate growth is likely to determine whether improving sentiment turns into sustained share-price follow-through.
Read our earnings preview for Octave Specialty Group, Inc.: https://www.earningswhispers.com/article/OSG/22656
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-23 | |
| Oct-19 | |
| Oct-08 | |
| Sep-29 | |
| Sep-08 | |
| Aug-06 | |
| Aug-06 | |
| Aug-03 | |
| Jul-17 | |
| May-06 | |
| May-06 |
