Fubo's New CEO Must Pair A Credible Strategy With Proof That Profits Have Bottomed
When FuboTV reports fiscal fourth-quarter results before the bell on November 17, the numbers will share the stage with something investors have been waiting on since summer: new chief executive Elisa Bowen's first real roadmap. Last quarter she inherited a business that was stabilizing under Disney's wing but earning less in absolute terms, and she deferred the substantive strategy and any refreshed targets to this call. That makes this report less about one quarter and more about whether the combined company has a plan that justifies the patience.
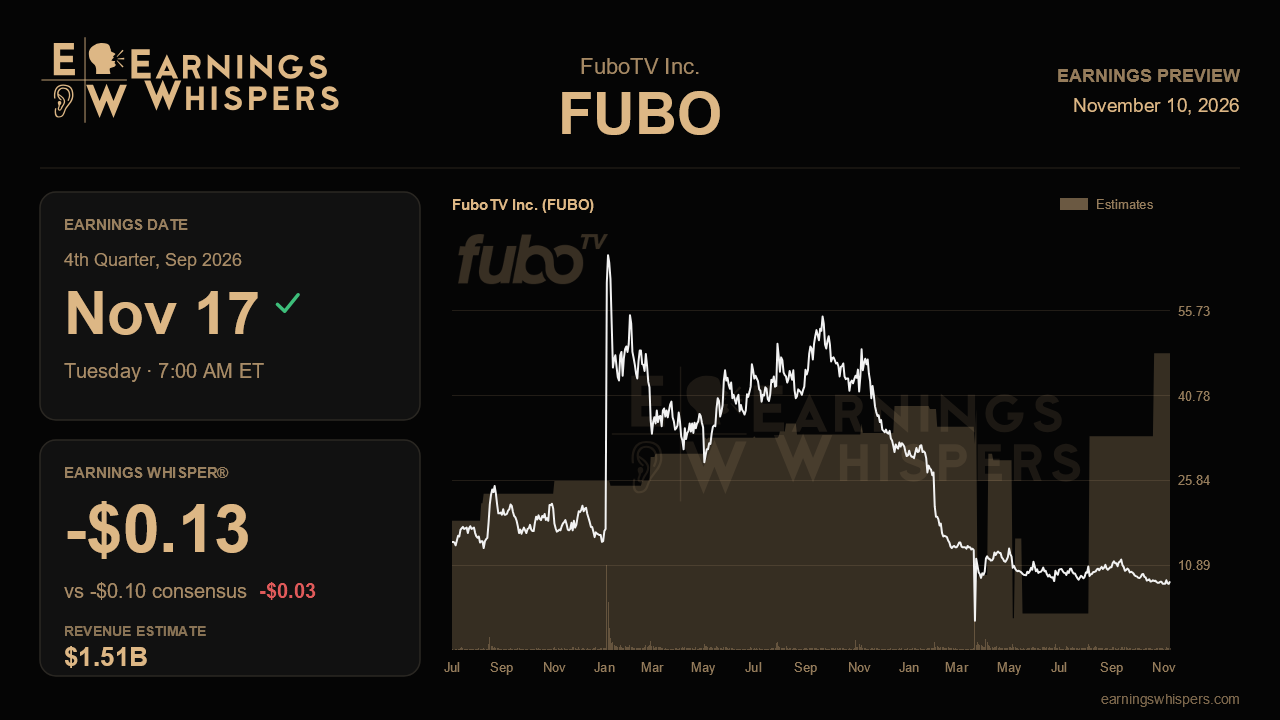
The Street is looking for revenue of about $1.51 billion and a loss of roughly $0.10 per share. The headline growth rate of around 300% is mostly a function of comparing the Hulu + Live TV combination with standalone Fubo's $377.2 million a year ago, so it says little about underlying momentum. The more honest yardstick is pro forma, where revenue was essentially flat year over year last quarter at $1.474 billion. Consensus implies a modest sequential step up from the prior quarter's $1.48 billion, which is reasonable but not demanding. The Earnings Whisper of a $0.13 loss sits a few cents below consensus, a sign that some market participants are braced for a slightly deeper loss than the published estimates suggest, though the gap is not large.
The cleaner test is profitability. Management lifted full-year pro forma adjusted EBITDA guidance to $90 million to $100 million and said it expected to land at the upper end of the original range. That raise came alongside a quarter in which adjusted EBITDA fell to $19.1 million, down from $37.7 million in the prior quarter and $31 million a year earlier. With fiscal 2026 now complete, this report shows whether the fourth quarter delivered enough to close the year near $100 million. A result toward the top of the range would suggest last quarter's dip was timing and seasonality; anything near the bottom would undercut the credibility of the raise and raise questions about the $300 million fiscal 2028 target management reaffirmed.
Advertising is where the bull case lives. Since the Disney ad server migration finished in June, CPMs and fill rates have climbed by double digits, and the finance chief described integration as ahead of plan with benefits stretching over several quarters. Continued double-digit ad gains, plus early read-through from Fubo's first inclusion in Disney's upfront, would validate that thesis. Persistent softness in entertainment advertising, flagged last quarter, is the counterweight. On subscribers, the pro forma gain of 25,000 against a 250,000 seasonal decline a year earlier was a genuine inflection, but World Cup programming helped. Holding those gains after the tournament ended is the real proof of durability, and updates on the ESPN Where to Watch link-out and the planned Hulu + Live TV integration into the Disney+ app at the end of calendar 2026 would show whether distribution advantages are maturing. The balance sheet, with management expecting more than $200 million of cash at year-end, should be a source of comfort rather than debate.
The market has not been generous in the meantime. Shares have fallen 6.9% since the last report, trailing the S&P 500 by about four points, and at $8.04 the stock sits roughly 30% below its 200-day moving average and not far above its post-earnings low of $7.44. Sentiment is mildly bullish and essentially unchanged from last quarter, suggesting investors are neither capitulating nor buying the turnaround yet. That leaves room for a relief move if the plan is concrete, but little tolerance if it is vague.
Ultimately, the narrative hinges on whether Bowen can present a strategy across pricing, content, distribution and technology that ties directly to rising EBITDA, while also addressing risks like a possible MLB work stoppage and the unresolved NBCU renewal. Proof that profitability bottomed last quarter, backed by sustained ad momentum, keeps the story intact. Another step down paired with a soft roadmap would challenge it.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Oct-26 | |
| Oct-22 | |
| Sep-29 | |
| Sep-28 | |
| Aug-27 | |
| Aug-26 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 | |
| Jul-21 | |
| Jul-13 | |
| Jul-13 | |
| Jul-09 | |
| Jul-09 |
