FuboTV Misses Badly On EPS As Strategic Reset Drops Subscriber Reporting And Pushes The Profit Story To FY2028
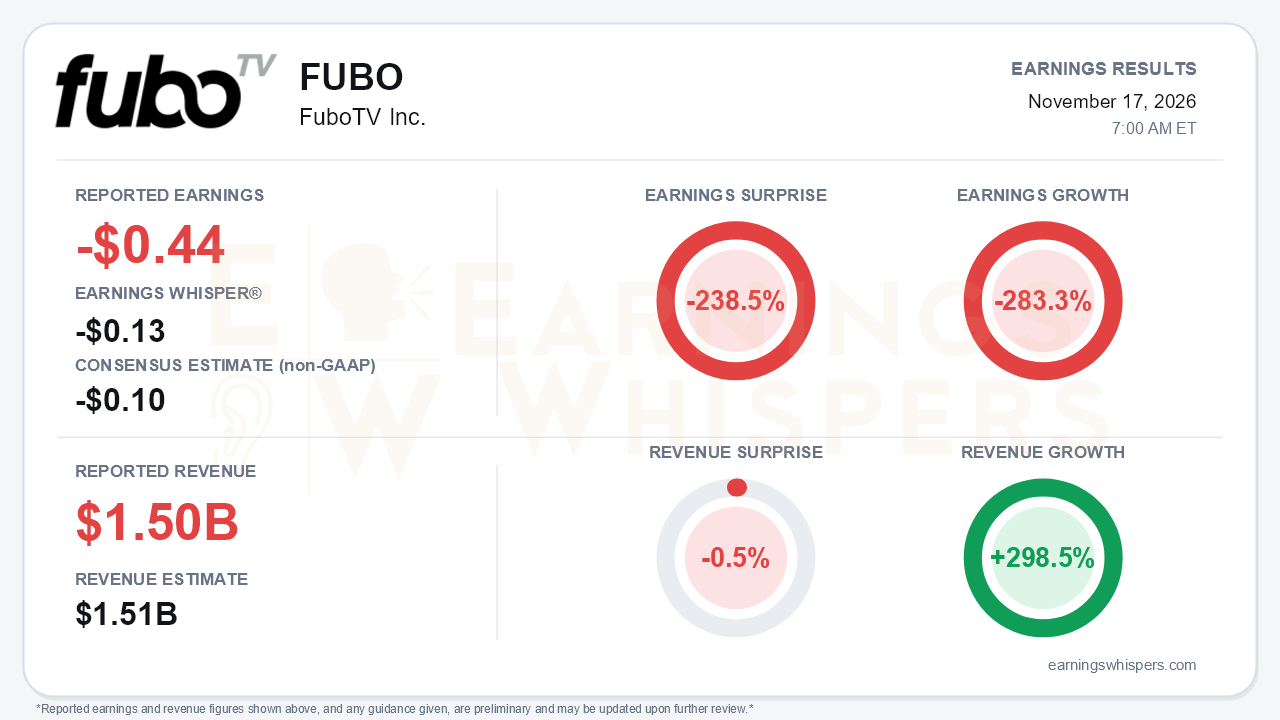
FuboTV's first full fiscal year as a combined Fubo and Hulu + Live TV business ended with a headline miss. The company reported a fiscal fourth-quarter loss of $0.44 per share, far worse than the -$0.10 consensus and the -$0.13 Earnings Whisper number. That is a 238.5% shortfall, and earnings fell 283.3% from a year ago. Revenue of $1.503 billion came in 0.5% below the $1.51 billion consensus. Reported revenue grew 298.5% year over year, but that figure mostly reflects the Hulu + Live TV combination. On a pro forma basis, quarterly revenue was essentially flat against $1.502 billion a year earlier. The central tension is that management beat its own full-year profitability and cash targets while removing the metric that best measured demand and declining to guide the next fiscal year.
The quality of the quarter deserves scrutiny. The GAAP net loss widened to $51.8 million from $38.8 million on an as-reported basis, although it narrowed from a $96.3 million pro forma loss. Consensus was set on a non-GAAP basis, while the reported loss absorbed $19.7 million of stock-based compensation, more than double the prior quarter. It also absorbed $8.4 million of legal and transaction costs, including severance tied to the former CEO and antitrust and data-privacy litigation. Those items help explain the gap but do not erase it.
Adjusted EBITDA of $12.3 million was the company's best-ever fourth quarter and well above the $4.1 million pro forma figure a year earlier. Sequentially, however, the trend went the wrong way through fiscal 2026:
- $41.4 million in the December quarter
- $37.7 million in March
- $19.1 million in June
- $12.3 million in September
Adjusted EBITDA margin compressed to just 0.8%. Investors should also note that prior quarters were labeled "as-revised" to correct purchase-price-allocation and other accounting errors, which management deemed immaterial.
The full-year picture is stronger. Pro forma adjusted EBITDA reached $110.6 million, nearly double the prior year's $58.5 million. That result cleared guidance of $90 to $100 million, a range already raised once from $80 to $100 million. Cash climbed $36 million in the quarter to $272.4 million, ahead of the more-than-$200 million target, on roughly $36 million of free cash flow. Advertising was the standout operating line. North American ad revenue rose 22% to $119.1 million on double-digit CPM gains and better fill after the migration to Disney's ad server. Fubo's CPMs have now largely converged with Hulu Live's, earlier than management indicated on the fiscal second-quarter call.
Demand is where bears have legitimate ammunition. North American subscribers ended at 5.75 million, flat sequentially and down from 6.01 million a year ago, after the prior quarter showed 2% annual growth. Rest-of-world subscribers slipped to 327,000. International operations are now under strategic review, which could lead to an exit or restructuring. Against that backdrop, the company will stop reporting total subscribers starting in fiscal 2027, arguing that broader packaging makes the count less meaningful. That may be partly true. Still, dropping the KPI right after it rolled over, while explicitly shifting away from lower-value subscribers, reduces visibility at exactly the wrong moment.
New CEO Alisa Bowen reframed the strategy around "profitable growth," replacing the prior regime's growth-first posture. Management reaffirmed its target of at least $300 million in adjusted EBITDA for fiscal 2028 and positive free cash flow in fiscal 2027 and 2028. It declined to give fiscal 2027 EBITDA guidance, saying the path will be non-linear and weighted toward fiscal 2028. Management is relying on several catalysts to bridge that gap:
- Disney+ and Hulu (with ads) included in Fubo Pro and Elite plans at no extra cost, though its economics were not disclosed
- Hulu Live integration into the Disney+ app by December
- An ESPN commerce flow and multi-view across platforms in the first half of calendar 2027
- Rate harmonization with several programmers
- An efficiency program that includes AI-driven engineering productivity
The market had already turned skeptical before the report. Shares entered earnings at $7.39, down 14.5% from the open after the August report. That price is 32.2% below the 200-day moving average and 41% below the inter-earnings high of $12.53 set in early September. The stock sat just 1.8% above the quarter's low, which was set the day before the release. Investor sentiment remained marginally positive but softened from 0.08 to roughly 0.05, a modest decline rather than a capitulation. The negative AVWAP trend fits a stock in which most recent buyers are underwater.
The bottom line is that FuboTV delivered on the cash and full-year EBITDA promises investors could verify, but the quarter itself showed a steep EPS miss, flat pro forma revenue, shrinking sequential EBITDA and declining subscribers. The decision to stop reporting subscribers and skip fiscal 2027 guidance asks investors to take more on faith just as the stock trades near its lows. Advertising momentum and the Disney bundle give the story credible levers. Until margins reverse their sequential slide, the $300 million fiscal 2028 target remains a promise rather than a trajectory.
Read our earnings preview for FuboTV Inc.: https://www.earningswhispers.com/article/FUBO/23097
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 49 min | |
| 1 hour | |
| 2 hours | |
| 3 hours | |
| 6 hours | |
| Nov-10 | |
| Oct-26 | |
| Oct-22 | |
| Sep-29 | |
| Sep-28 | |
| Aug-27 | |
| Aug-26 | |
| Aug-05 | |
| Aug-05 | |
| Jul-23 |
