Gladstone Capital's Credit Watch: Can Asset Growth Outrun Rising Non-Accruals?
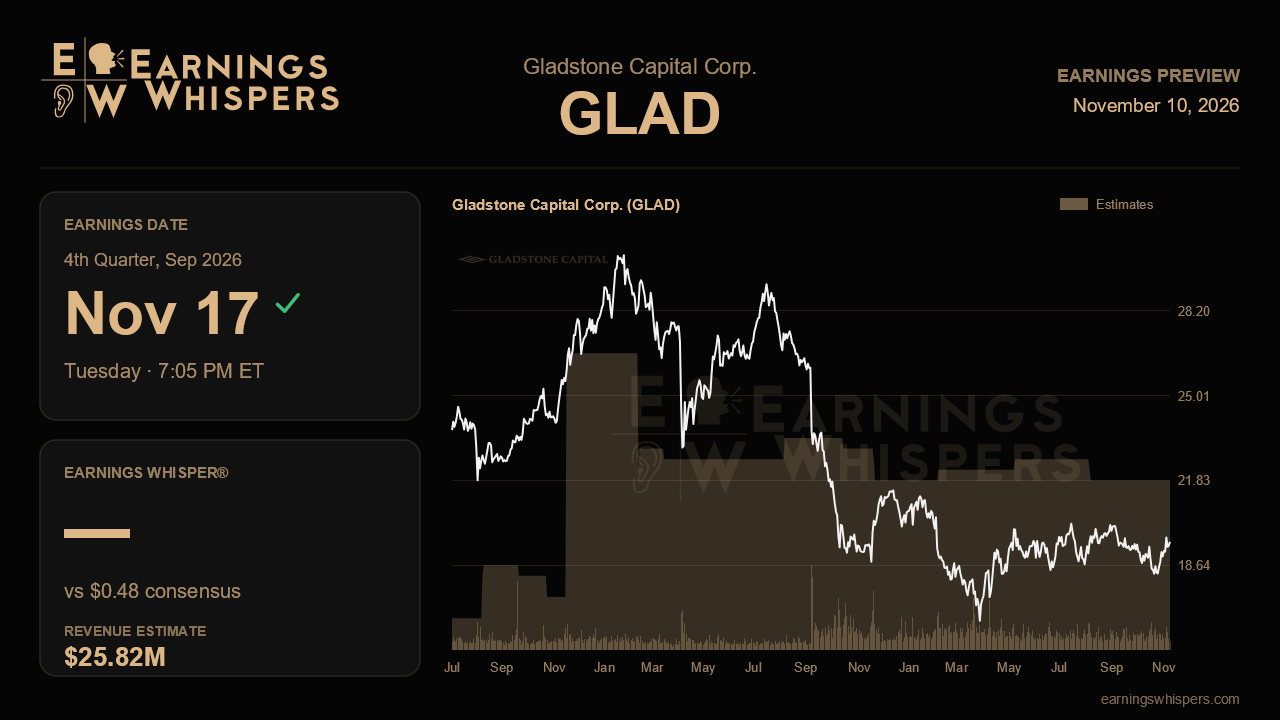
Gladstone Capital heads into its fiscal fourth-quarter report with a story that has two halves pulling in opposite directions. The lending engine looks healthy, with a growing portfolio, steady yields and a pipeline management called easy to fill. Credit quality, though, slipped noticeably last quarter, and the dividend cushion got thinner. The report due after the close on November 17 should show which half is winning.
Wall Street expects net investment income of $0.48 a share on revenue of about $25.8 million. That would be a 7.9% rise in revenue from a year ago but a 7.7% decline in per-share earnings from $0.52. The gap between the two is the setup in a nutshell. The top line is expected to benefit from a larger asset base, while per-share profit is squeezed by higher funding costs and the loss of one-time fee income. Leverage climbed to 100% of net asset value last quarter from about 92%, and the company issued $60 million of 7% notes due 2029. More borrowed money should lift interest income, but it also raises interest expense, so the Street is effectively betting that growth is largely offset by financing costs.
The dividend math matters more than usual. Management held the payout at a $1.80 annual run rate, or $0.45 a quarter, rather than raising it. Last quarter's $0.49 covered that by 109%, down from 116% the quarter before. Consensus of $0.48 implies coverage of roughly 107%. That is still adequate, but the cushion is shrinking. Management also warned that an upcoming prepayment would reduce payment-in-kind income in coming quarters. A result below consensus would push coverage toward levels that make income investors uneasy.
Credit is the bigger swing factor. Non-earning debt investments jumped to five names, at 3.1% of the debt portfolio at fair value, from three names and 1.6% in each of the prior two quarters. The newest additions, a circuit-board contractor and an Arizona quick-service restaurant operator that defaulted again, are both controlled by Gladstone and will need more capital. Management also flagged softer consumer spending pressuring restaurant borrowers and turned more cautious on reshoring, citing tariffs and high steel and copper prices. Stable or lower non-accruals and another quarter of rising net asset value, which reached $21.50 last quarter after three straight gains, would confirm last quarter's blip was contained. A sixth troubled credit, or markdowns that reverse the NAV trend, would suggest the softer tone was an early signal rather than a passing caution.
On the growth side, management pointed to roughly $75 million of quarterly originations as achievable, slower repayments, and new first-lien loans at spreads near 7% over SOFR with no yield compression. The weighted average debt yield held at 11.8%. Strong net originations at similar yields would support the revenue estimate and suggest that the pipeline, heavy with add-on deals for existing portfolio companies, is turning into earning assets. The post-quarter $12 million prepayment that ended oil and gas exposure tidies up the book but removes some income that needs replacing.
The market has been fairly forgiving. Shares are up 2.1% since the last report while the S&P 500 fell 1%, and at $19.52 the stock sits above its 200-day moving average but somewhat below its post-earnings high of $20.38, about 9% under book value. Sentiment has edged slightly more bearish, a sign of mild caution rather than alarm. The verdict will likely hinge on whether Gladstone can keep growing its portfolio at stable yields without more borrowers sliding into non-accrual. Clean credit and steady coverage would keep the income story intact; further deterioration would make last quarter's mixed picture look more like a turning point.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Oct-13 | |
| Sep-21 | |
| Aug-31 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-14 | |
| Jun-02 | |
| May-21 | |
| May-06 | |
| May-06 | |
| May-05 | |
| Apr-14 |
