Gladstone Capital Edges Past NII Estimates, But Thinning Dividend Coverage And A $0.73 NAV Drop Dominate The Quarter
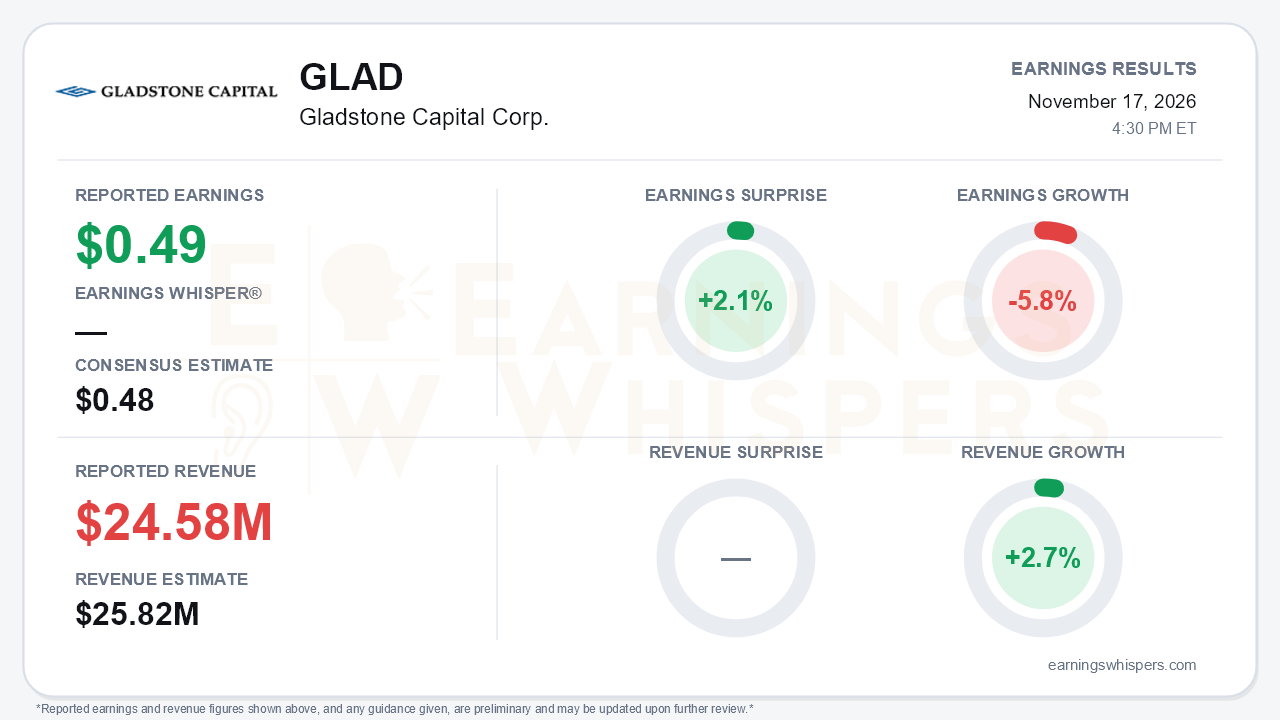
Gladstone Capital (NASDAQ: GLAD) cleared the earnings bar by a narrow margin, but the more important story sits below net investment income. The business development company reported fiscal fourth-quarter net investment income of $0.49 per share, beating the $0.48 consensus by 2.1%. Total investment income of $24.58 million missed the $25.82 million consensus by 4.8%. Earnings fell 5.8% year over year while revenue grew only 2.7%. NII per share was unchanged from the June quarter. The modest beat does little to offset a quarter in which net asset value per share fell $0.73 to $20.77 and coverage of the regular dividend shrank to exactly 100%. That is the central tension: earnings held steady, while the balance sheet and the cushion behind the distribution both weakened.
The quality of the beat deserves scrutiny. Total investment income rose just 0.3% sequentially because the average interest-bearing balance and yield were essentially flat. Net expenses rose 0.5% on higher interest costs and base management fees. Part of that increase was offset by a $0.5 million incentive fee credit from the Adviser. Without that credit, Q4 NII would not have fully covered the $0.45 per share of regular distributions. The full-year results show the same pattern of growth without per-share leverage. Total investment income rose 11.7% to $99.6 million on a 17.9% increase in average earning assets. However, expenses rose 24.0%, and NII per share slipped to $2.00 from $2.02. Portfolio growth has so far been absorbed by higher interest expense and fees rather than translated into shareholder earnings. CEO Bob Marcotte acknowledged this implicitly by naming that translation as the fiscal 2027 priority.
Credit is where the quarter turned. On a GAAP basis, net assets from operations fell $2.2 million, or $0.10 per share, driven by $13.6 million of net unrealized depreciation, including $9.2 million on control investments. Key markdowns included:
- a $5.5 million markdown on the loan to EGs, an Arizona quick-service restaurant operator whose revenue came in weaker than expected and which required additional capital;
- B&T, which was written to zero;
- $7.1 million of depreciation across three equity positions that fell short of plan.
Non-accrual fair value fell to 2.8% of debt investments from 3.6%, which looks better on the surface. That improvement came entirely from markdowns, not resolutions. At cost, non-earning assets have climbed from $28.8 million in the first half of the year to $46 million in Q3 and $52.9 million now.
The call also showed the earnings engine losing some momentum:
- **Coverage:** regular-dividend coverage after preferred dividends slid from 116% in Q2 to 109% in Q3 to 100% in Q4.
- **Yield:** weighted average yield eased to 11.7%, and the CEO said yields are likely at the top end of their range.
- **Originations:** net originations slowed to $13 million from $42 million in Q3.
- **Leverage and spillover:** leverage rose to 1.08x including preferred stock, prompting management to ration new capital. Spillover income declined to $5.5 million, or $0.24 per share.
- **Fee waivers:** management now openly raises incentive fee waivers as a lever to sustain coverage.
- **Tone:** the language shifted from Q3's upbeat framing to a more defensive emphasis on maintaining coverage.
There is a credible offset. Management said the mid-September rate increase of roughly 25 basis points should add about 6 cents per share of NII beginning in the December quarter. New-deal economics held up, with Q4 originations priced at SOFR plus 730 basis points. Two new precision-manufacturing investments totaling about $33 million are tied to aerospace, defense, data center and grid demand that management called the strongest it has seen. Portfolio company Viron carries more than a year of backlog, which could support a refinancing or sale. A possible sponsor sale of Dutch Gold Honey could produce equity gains in 2027, and the B&T exit is expected to carry no further NAV impact. Funding capacity also expanded through the larger $385 million credit facility and a $57 million preferred balance. On the risk side, management flagged a rising SOFR forward curve as a headwind for buyouts and noted repayment pressure as portfolio companies scale.
Investor sentiment remained negative but improved modestly, moving to -0.093 from -0.133. The market has treated the stock with indifference rather than alarm. Shares at $18.87 are down 1.3% since the open after the August report and sit 0.8% below the 200-day moving average of $19.01. The Earnings Whispers AVWAP trend remains negative. The stock trades below the newly reduced $20.77 NAV, so investors were already pricing in some credit skepticism before this report.
The bottom line is that GLAD delivered a technically clean NII beat that masks a weaker underlying trend. NAV eroded, non-earning assets at cost kept rising, and regular-dividend coverage now rests on a fee credit with no margin to spare. The rate tailwind and strong manufacturing deal flow give management a plausible path to rebuild that cushion in fiscal 2027. Until fee-supported coverage gives way to organic earnings growth and markdowns stabilize, bears have legitimate ammunition.
Read our earnings preview for Gladstone Capital Corp.: https://www.earningswhispers.com/article/GLAD/23114
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-17 | |
| Nov-17 | |
| Nov-16 | |
| Nov-10 | |
| Oct-13 | |
| Sep-21 | |
| Aug-31 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-03 | |
| Jul-14 | |
| Jun-02 | |
| May-21 |
