ZTO's Price-Over-Volume Bet Faces Its Real Test As Parcel Growth Slows
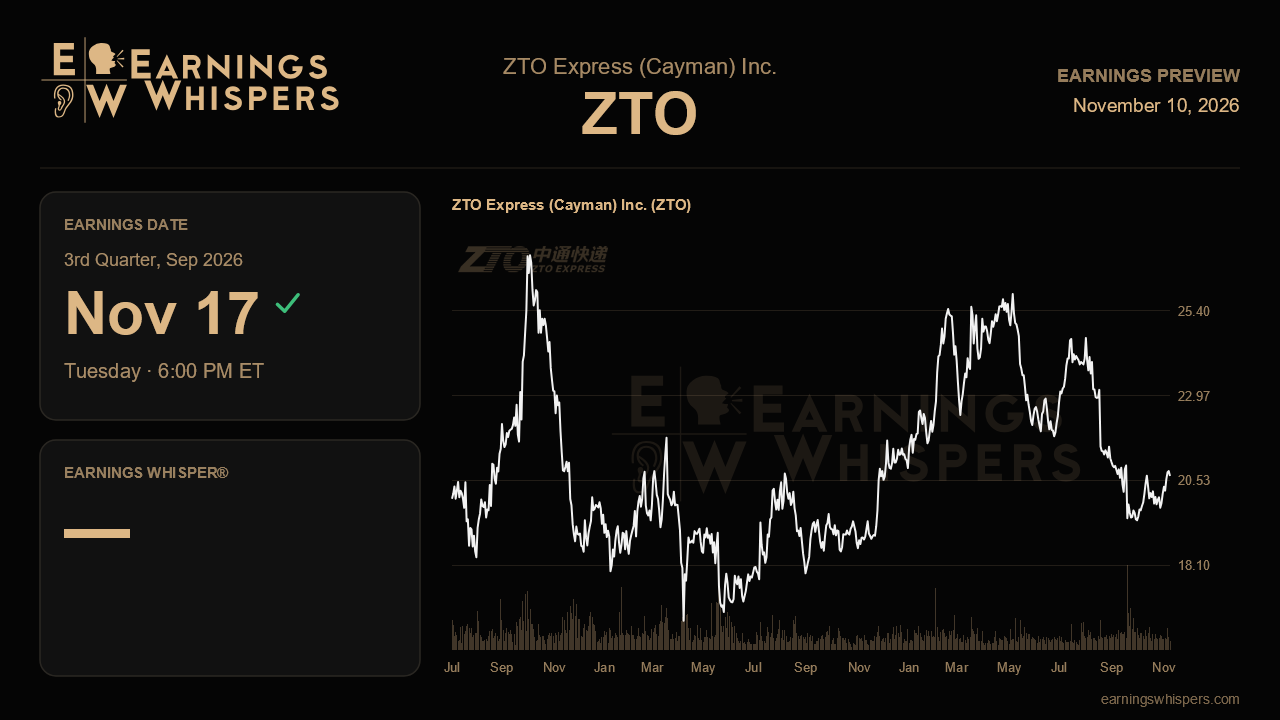
ZTO Express enters its third-quarter report with a question that will shape how the market values it: can rising prices and fatter margins keep compensating for parcel growth that is clearly losing steam? Last quarter the answer was a resounding yes. Adjusted net income jumped about 50% from a year earlier, a sharp acceleration from roughly 5% growth in the prior quarter. Yet management also cut its full-year volume outlook to 6% to 10% growth, down from the 10% to 13% range it had held since the start of the year. The November 17 release, due after the close, should show whether that tradeoff is a durable strategy or a one-quarter flourish.
A reliable consensus figure for the quarter is hard to pin down, so the year-ago results make the more useful yardstick. In the third quarter of last year ZTO earned $0.43 per share on $1.67 billion in revenue. The most recent quarter produced $0.56 on $2.14 billion, a level that shows how much pricing has lifted the top line. If the company can hold anything close to that run rate, it would post solid double-digit earnings growth against an undemanding comparison. That comparison is easier still because profit growth in the year-ago quarter was only about 5%.
Pricing is the engine to watch. Average selling price rose 15.5% last quarter, nearly double the first-quarter increase, helped by a richer mix of key-account and reverse-logistics parcels. Return-related volume reached about 9.8 million parcels a day, up roughly 80% year over year. The industry's push against destructive price competition gives ZTO room to charge more, but the same policy is squeezing low-priced e-commerce parcels out of the market. Industry volume growth slowed to 4.2% in the second quarter, and ZTO's own growth fell to 6.5% from 13.2%. The narrative holds if price gains stay in the mid-teens while volume stabilizes inside the reduced range. It weakens if pricing gains fade before volume recovers, or if parcel growth drifts toward the bottom of the new range and prompts another cut.
Costs are the second swing factor, and management already flagged the headwinds. Combined sorting and transport cost per parcel fell only 2 cents last quarter, compared with 6 cents in the first quarter, because diesel prices about 24% higher added roughly 2 cents per parcel. Management expects fuel to keep adding 1 to 2 cents through the second half. Mandatory social-security contributions for couriers are another looming expense. Against that, ZTO has started putting numbers on its AI efforts, including line-haul tools it says cut about 12% of first-half transport costs. Holding a gross margin near the 25.7% reached last quarter would suggest those savings are real. A slide back toward first-quarter levels would point to fuel and labor costs eating the pricing gains. Administrative spending, which fell 10.5% last quarter, is also worth checking for signs that the discipline was a timing benefit.
The market has not rewarded last quarter's profit surge. Shares are down 3.9% since the report, trailing the S&P 500 by 1.6 percentage points. At $20.66, the stock sits below its 200-day moving average of $22.81 and in the middle of a post-earnings range of $18.95 to $22.17. That range sits wholly below the prior quarter's $21.47 to $24.78 band. Sentiment has also turned slightly bearish after leaning bullish before the last report, so the bar heading in looks lower than it did three months ago. Cash generation and the commitment to return at least half of adjusted profit, backed by a $1.5 billion buyback, offer some cushion.
In the end, this report comes down to whether ZTO's profit per parcel can keep rising faster than its parcel count is slowing. Firm pricing, steady margins despite fuel costs and a volume outlook left intact would support management's argument that quality now matters more than scale. A second cut to volume guidance, or margin slippage, would suggest the market's skepticism was justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Oct-16 | |
| Sep-03 | |
| Aug-19 | |
| Aug-19 | |
| Aug-18 | |
| Jul-23 | |
| Jul-20 | |
| Jun-16 | |
| May-20 | |
| May-20 | |
| May-20 | |
| May-19 | |
| Apr-24 | |
| Apr-17 |
