ZTO Express Wins Share And Lifts Pricing, But A Slowing Industry And Pass-Through Revenue Make The Growth Less Than It Appears
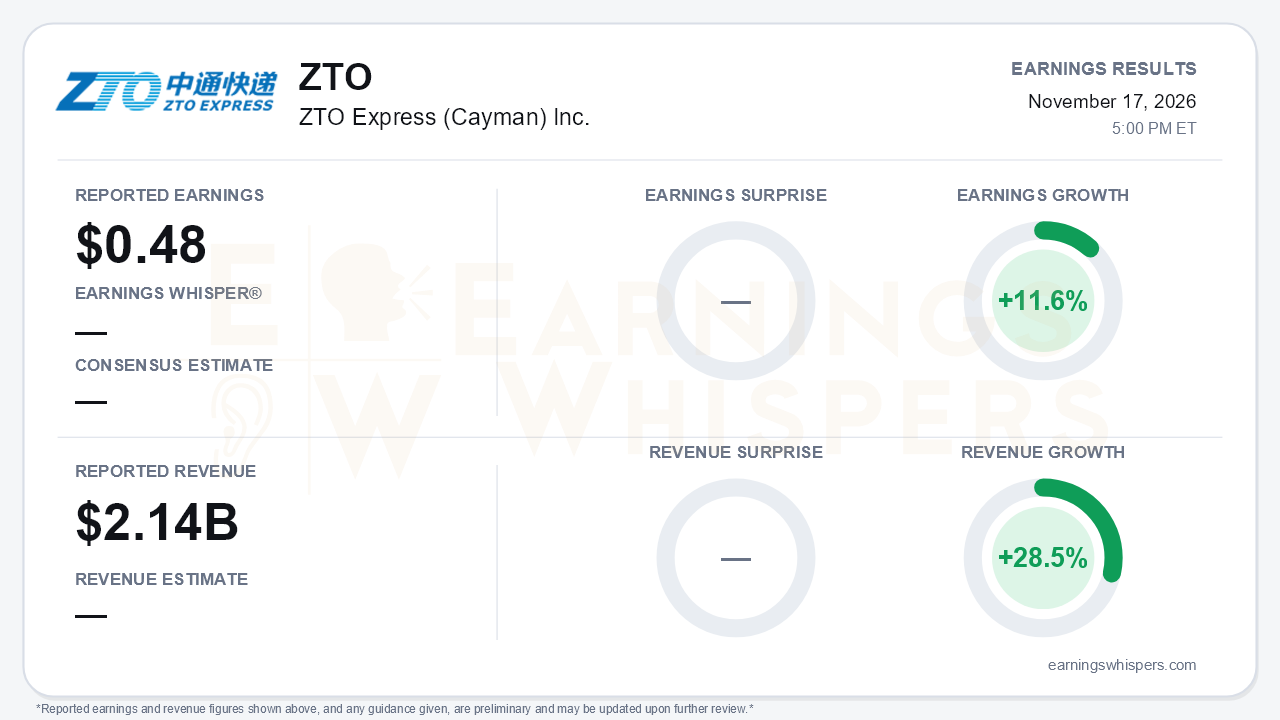
ZTO Express (NYSE: ZTO) reported third-quarter earnings of $0.48 per share on revenue of $2.142 billion. On the dollar basis Earnings Whispers uses, earnings grew 11.6% and revenue grew 28.5% year over year. No consensus estimate was available, so there is no surprise to measure. In renminbi the figures are more modest: revenue rose 21.0%, adjusted diluted EPS rose 4.6%, and GAAP diluted EPS rose 3.2%. Much of the gap reflects a stronger renminbi in the dollar translation. The central takeaway is that ZTO is executing well in a market that is losing momentum. The company is gaining share and raising unit pricing, but much of the revenue growth is low-margin, and the industry backdrop deteriorated again.
The quality of the top-line growth deserves scrutiny. Core express revenue rose 21.6% on 7.0% volume growth and a 13.7% increase in unit price. The pricing gain was driven mainly by mix. Key-account revenue jumped 68.3%, led by e-commerce return parcels. Those returns carry heavy pass-through costs: "other costs" rose 59.1%, including a RMB1.67 billion increase in pickup and dispatch payments to network partners. As a result, gross profit grew 19.5%, slower than revenue, and gross margin slipped to 24.6% from 24.9%.
The operating line looked better. Operating income rose 23.8% to RMB2.98 billion, and operating margin edged up to 20.7%. Leaner SG&A drove the improvement: excluding share-based compensation, SG&A fell to 4.2% of revenue from 5.3%. Below the operating line, the picture weakened. Interest income nearly halved, and last year's RMB376 million tax refund produced a tough comparison. Net income rose just 1.4%, and adjusted net income grew 2.6%. Management notes that adjusted net income would have grown 20.7% excluding the refund.
The call sharpened both sides of the story. ZTO's volume growth edged up to 7.0% from 6.5% in the second quarter, while industry growth slowed to 2.9% from 4.2% in the second quarter and 5.8% in the first. That gap lifted market share 0.7 points to 20.1%. Retail parcel growth re-accelerated to 57% from 47%, and management expects that trend to continue into the fourth quarter. Line-haul unit cost fell 5.8% despite roughly a cent of diesel headwind.
The sequential trend was weaker. Operating margin fell from 22.2% in the second quarter. Gross margin went from expanding 0.8 points to contracting. Sorting-cost improvement stalled at 0.25 as depreciation from new automation rose. Management also described slower industry growth as the new norm and characterized this year's peak season as less pronounced than in prior years.
The forward risks are concrete. Diesel costs are expected to weigh as much or more in the fourth quarter. Platform auctions are pressuring reverse-logistics pricing, which is the same business driving the ASP gains. Social insurance compliance adds near-term per-parcel cost, although management framed it as a possible catalyst for industry-wide price increases that ZTO could benefit from. Full-year volume guidance was held at 6% to 10%, the range already cut in the second quarter from 10% to 13%, rather than restored. Capital returns are a partial offset. Management cited roughly US$1.05 billion repurchased year to date and said buybacks will exceed 100% of last year's net profit. The release shows US$376.9 million of that executed under the new US$1.5 billion authorization. However, there will be no supplemental dividend this year.
The market had already cooled on the story going into the report. Investor sentiment slipped from 0.11 to -0.06, a modest swing from mildly positive to mildly negative rather than a capitulation. As of the pre-report snapshot, shares stood at $20.48:
- down 4.7% from the $21.50 open after the August report;
- about 10% below the 200-day moving average of $22.77;
- 7.6% below the inter-earnings high of $22.17, set on August 19;
- 8.1% above the September low of $18.95.
The trend readings are mixed, with price trend negative while AVWAP is positive. Overall, the stock is drifting rather than breaking down, but it has not attracted buyers despite share gains.
The bottom line is that ZTO delivered a competent quarter with genuine share gains, strong cost control, and solid cash generation of RMB3.7 billion in operating cash flow. However, the headline growth rates overstate the earnings power. Revenue is inflated by pass-through return volume, margins softened sequentially, and the industry is slowing more than expected. With guidance held at reduced levels and costs rising into the fourth quarter, ZTO looks like a share-taker in a maturing market, supported more by buybacks than by accelerating profit.
Read our earnings preview for ZTO Express (Cayman) Inc.: https://www.earningswhispers.com/article/ZTO/23120
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-17 | |
| Nov-17 | |
| Nov-17 | |
| Nov-10 | |
| Oct-16 | |
| Sep-03 | |
| Aug-19 | |
| Aug-19 | |
| Aug-18 | |
| Jul-23 | |
| Jul-20 | |
| Jun-16 | |
| May-20 | |
| May-20 | |
| May-20 |
