I3 Verticals Must Prove Its Twice-Cut Outlook Has Finally Found A Floor
After two straight guidance cuts and a trimmed growth bar for next year, i3 Verticals heads into its fiscal fourth-quarter report with a credibility problem rather than a demand mystery. The question is no longer whether the year was softer than planned. Management has already conceded that. The question is whether the lowered targets were set conservatively enough to be cleared, and whether the go-lives and fixes it promised are showing up on schedule.
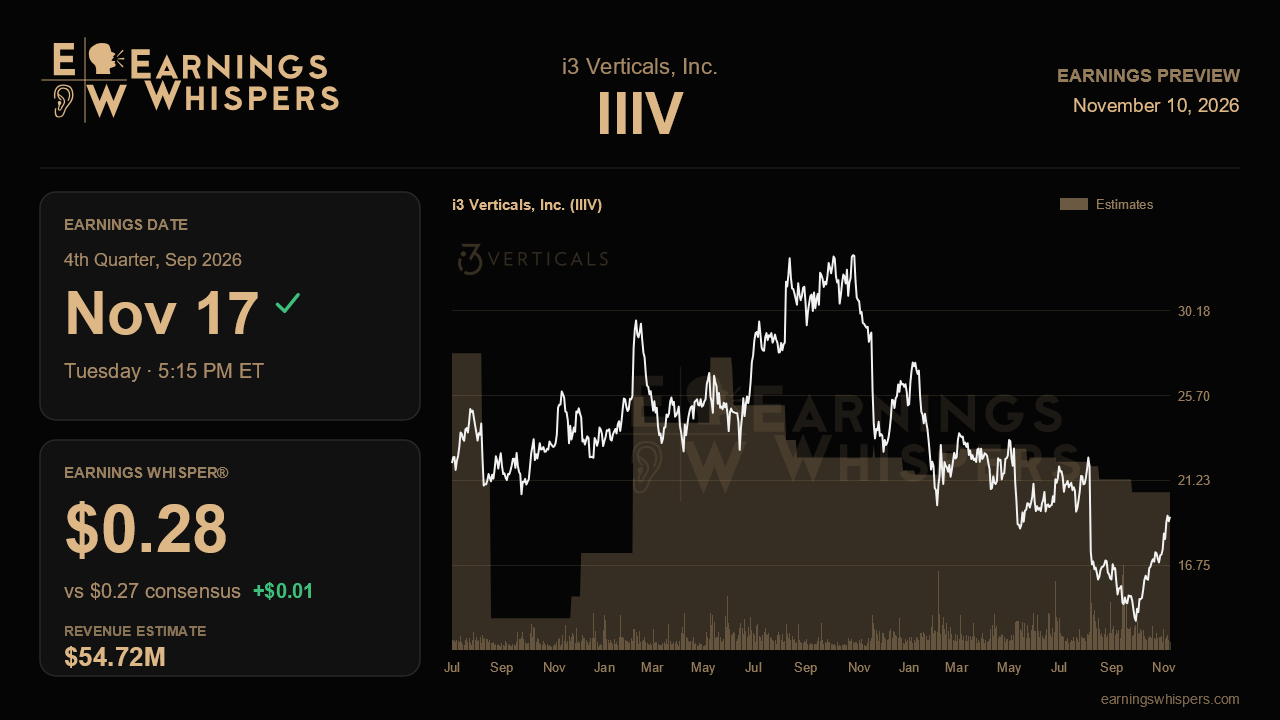
The Street is looking for adjusted earnings of $0.27 per share on revenue of about $54.7 million, essentially flat with the year-ago quarter's $54.9 million. The Earnings Whisper sits a penny higher at $0.28, a modest nudge that suggests some confidence in the margin story but hardly a call for a blowout. The revenue estimate implies roughly a 3% sequential step up from the $53.1 million reported last quarter, which is not trivial for a company whose organic revenue slipped 2% in the third quarter. Management's revised fiscal 2026 range of $1.08 to $1.12 in adjusted EPS and $216 million to $221 million in revenue is the more relevant anchor; full-year consensus figures that still sit above the top of that range look like they have not fully caught up with the latest cut, which could make headline comparisons noisier than usual.
The biggest swing factors are the ones management named when it lowered the outlook. Roughly $4.5 million of the reduction came from professional services, including about $3 million of utilities software projects pushed out, and the company warned that weakness would persist into this quarter. Another $1 million or more stemmed from elevated commercial card interchange squeezing payments take rates, with a processor data fix slipping into the fourth quarter. If that fix landed, payments margins should show it. If it slipped again, it becomes harder to treat the problem as merely timing. The Resolve court product, which underperformed on case throughput largely outside the company's control, is a third item where any further weakness would signal the guide cuts were not yet complete.
On the positive side, the evidence to look for is concrete. Two legacy transportation contracts began contributing recurring revenue this quarter, the Georgia statewide vehicle renewal program is fully live, and eight AI document extraction and redaction contracts across four states started going live. Annual recurring revenue growth decelerated to 8% from 12% last quarter, so a stabilization or rebound there would be the clearest sign that the reacceleration bridge into fiscal 2027 is real. SaaS growth near 38% and recurring revenue at 82% of the total should hold up, and adjusted EBITDA margin, which reached 25% last quarter, needs to remain firm given that management lifted its fiscal 2027 margin expansion target to 100 to 200 basis points on AI-driven development efficiency. Receivable reserves and rising usage-based AI costs are the risks that could blunt that leverage.
The market has already rendered a verdict on the last report. Shares have fallen 12% since then, trailing the S&P 500 by nearly 10 percentage points, and at $19.31 the stock sits just below its 200-day moving average of $19.74. It has, however, climbed well off its post-report low of $13.63, and sentiment has swung from mildly bearish ahead of the last report to mildly bullish now. That rebound means some of the capitulation has already been reversed, so a merely in-line print may not carry the stock much further.
Ultimately, this report hinges on fiscal 2027 commentary. Investors need to hear that the mid-single-digit growth outlook is holding, ideally with evidence that new go-lives are lifting recurring revenue. A third reset would turn a tolerable rough patch into a pattern.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-17 | |
| Nov-16 | |
| Nov-10 | |
| Nov-03 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jun-02 | |
| May-07 | |
| Apr-23 | |
| Feb-28 | |
| Feb-20 | |
| Feb-11 | |
| Feb-06 |
