I3 Verticals Beats And Guides Higher On Margins And Buybacks While Organic Growth Keeps Slowing
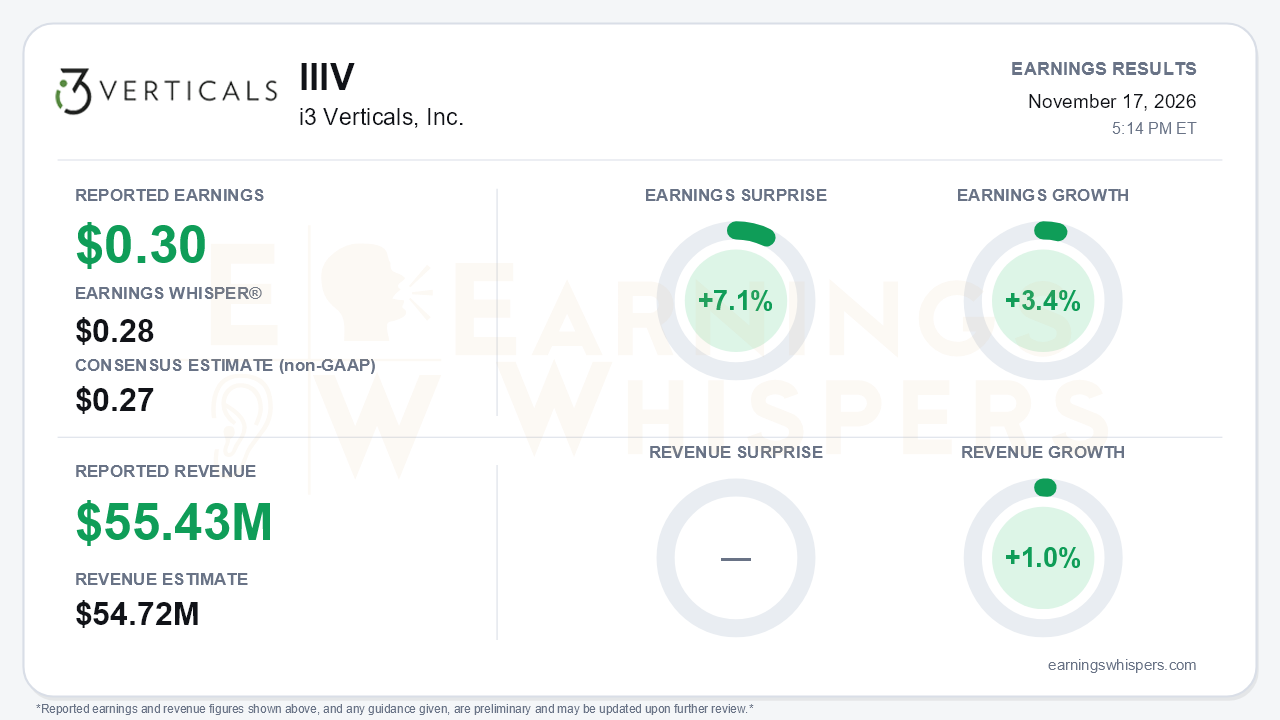
i3 Verticals delivered a clean-looking fiscal fourth-quarter beat, but most of it came from cost control and a shrinking share count rather than business momentum. Adjusted earnings of $0.30 per share topped the $0.27 consensus by 7.1% and edged past the $0.28 Earnings Whisper number. Revenue of $55.43 million beat the $54.72 million consensus by 1.3%. Growth was thin, though: earnings rose 3.4% year over year and revenue just 1.0%. The fiscal 2027 outlook landed above estimates, yet it relies on margin expansion and capital allocation, not a reacceleration in the top line. That is the central tension in the report.
The quality of the beat deserves scrutiny.
- **Profit dollars fell.** Adjusted net income from continuing operations declined to $7.8 million from $9.1 million a year earlier.
- **Share count did the work.** Per-share growth came from adjusted diluted shares falling to 26.4 million from 34.2 million.
- **GAAP swung to a loss.** The company posted a diluted loss of $0.17 per share from continuing operations, versus a $0.04 profit a year ago.
- **Charges drove the GAAP loss.** The quarter absorbed a $6.1 million contingent-consideration charge and a $3.0 million accrual for the State of Louisiana lawsuit settlement. Equity-based compensation also climbed to $5.1 million from $3.2 million.
- **The buyback was debt-funded.** Cash dropped to $3.7 million from $66.7 million over the year, and long-term debt rose to $118.5 million from zero. Additional paid-in capital fell by roughly $127 million.
Operating cash flow of $55.7 million shows the business generates real cash. Still, investors should recognize that this EPS story is increasingly financially engineered.
Margins are where the operating story improved. Adjusted EBITDA rose 5.5% to $15.2 million, and margin reached 27.4%, up from 26.2% a year earlier and 25.0% in the third quarter. Corporate expenses fell to 7.1% of revenue from 9.3% in Q2 and 8.2% in Q3. SaaS revenue grew 35%, extending a run of mid-to-high-30% growth.
Beneath that, the recurring engine is decelerating on several fronts:
- **ARR:** growth slowed to 7% ($177 million), down from 12% in Q2.
- **Net dollar retention:** fell to 100% from 104%.
- **Transaction revenue:** growth slid from 12% in Q1 to 7%, then 5%, and was flat in Q4. Management pointed to weak Resolve recovery rates and lower utility payment volumes.
The CEO's release language about "strong momentum" sits awkwardly next to his acknowledgment on the call that fiscal 2026 missed expectations. Revenue guidance was cut twice during the year, from $223–234 million to $216–221 million.
The fiscal 2027 guide reinforces that profitability, not revenue, is the story.
- **Revenue:** $220–235 million, roughly 4% growth at the midpoint. That is the low end of the mid-single-digit view set last quarter, which itself replaced a high-single-digit target held through Q2. License revenue is expected to decline, and the West Virginia ramp slips to late fiscal 2027 or 2028.
- **Adjusted EBITDA:** $61.25–68.75 million, implying about 11% growth and roughly 180 basis points of margin expansion. That is above the company's historical 50–100 basis-point framework.
- **Adjusted EPS:** $1.23–1.41, up from $1.11 in fiscal 2026. The width of the range reflects dependence on buyback pace.
Several catalysts support the margin case:
- **Cheaper financing:** an October refinancing into a $350 million all-revolver facility cut spreads by 50 basis points.
- **Payments fixes:** the commercial-card interchange fix is complete, and utilities attrition fully annualizes after Q1.
- **Commercial wins:** a competitive Northeast insurance-verification win, more than 1 million kiosk registration renewals, and AI document processing extended into land records.
Bears have legitimate ammunition elsewhere. Statewide payment-processor agreements are creating friction for payments attach, and retention has already softened to breakeven.
The market has not been rewarding the margin narrative. Shares opened at $21.94 after the August report and now sit at $18.71, down 14.7%. That leaves the stock about 4.7% below its 200-day moving average of $19.62. Investor sentiment, already negative, weakened modestly from -0.22 to -0.29. Investors entered the print skeptical and grew slightly more so, likely reflecting the guidance cuts and slowing recurring metrics. The Earnings Whispers trend readings are mixed, with AVWAP positive and price trend neutral, consistent with a stock that has stabilized without regaining momentum.
The broader shift is in how i3 Verticals asks to be valued. The company has moved from an organic-growth vertical-software pitch toward a margin-and-buyback compounding model funded by new leverage. That can produce double-digit EPS growth on 4% revenue growth, but it leaves less cushion if retention or transaction volumes keep eroding.
The bottom line is that i3 Verticals beat, expanded margins and issued above-consensus profit guidance, but the quarter reset expectations rather than repaired them. Revenue, ARR, retention and transaction growth all slowed. Earnings growth now leans heavily on cost discipline and a debt-funded share count reduction. Until recurring revenue growth stabilizes, the improved profit outlook is likely to be weighed against a top line that has yet to show it has found a floor.
Read our earnings preview for i3 Verticals, Inc.: https://www.earningswhispers.com/article/IIIV/23115
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| Nov-17 | |
| Nov-16 | |
| Nov-10 | |
| Nov-03 | |
| Aug-07 | |
| Aug-06 | |
| Jul-23 | |
| Jun-02 | |
| May-07 | |
| Apr-23 | |
| Feb-28 | |
| Feb-20 | |
| Feb-11 | |
| Feb-06 |
